1<!DOCTYPE html><html lang="en" data-dpl-id="dpl_ET3ut9gLNFT7gDBHfWE4Mt3A2d6U"><head><meta charSet="UTF-8" data-next-head=""/><meta name="viewport" content="width=device-width, initial-scale=1.0" data-next-head=""/><meta name="description" content="Articles from the Billplz team on payments in Malaysia: FPX, DuitNow QR, payment links, marketplace comparisons, and gateway reviews." data-next-head=""/><meta name="keywords" content="online payment Malaysia, payment gateway, secure payment, payment platform, fintech, Billplz" data-next-head=""/><link rel="icon" type="image/svg+xml" href="/assets/favicon/favicon.svg?v=1.1" data-next-head=""/><link rel="icon" href="/favicon.ico" data-next-head=""/><link rel="alternate icon" type="image/png" sizes="32x32" href="/assets/favicon/favicon-32.png?v=1.1" data-next-head=""/><link rel="alternate icon" type="image/png" sizes="16x16" href="/assets/favicon/favicon-16.png?v=1.1" data-next-head=""/><meta name="robots" content="index, follow" data-next-head=""/><link rel="canonical" href="https://main.billplz-sandbox.com/blog" data-next-head=""/><meta name="author" content="Billplz" data-next-head=""/><meta property="og:site_name" content="Billplz" data-next-head=""/><meta property="og:title" content="Billplz blog ⢠Payments in Malaysia, explained" data-next-head=""/><meta property="og:description" content="Articles from the Billplz team on payments in Malaysia: FPX, DuitNow QR, payment links, marketplace comparisons, and gateway reviews." data-next-head=""/><meta property="og:image" content="https://main.billplz-sandbox.com/assets/images/billplz/og-image.webp?v=1.1" data-next-head=""/><meta property="og:url" content="https://main.billplz-sandbox.com/blog" data-next-head=""/><meta property="og:type" content="website" data-next-head=""/><meta name="twitter:card" content="summary_large_image" data-next-head=""/><meta name="twitter:title" content="Billplz blog ⢠Payments in Malaysia, explained" data-next-head=""/><meta name="twitter:description" content="Articles from the Billplz team on payments in Malaysia: FPX, DuitNow QR, payment links, marketplace comparisons, and gateway reviews." data-next-head=""/><meta name="twitter:image" content="https://main.billplz-sandbox.com/assets/images/billplz/x-image.webp?v=1.1" data-next-head=""/><title data-next-head="">Billplz blog ⢠Payments in Malaysia, explained</title><link rel="preconnect" href="https://fonts.googleapis.com"/><link rel="preconnect" href="https://fonts.gstatic.com" crossorigin="anonymous"/><link rel="preload" href="https://fonts.googleapis.com/css2?family=Inter+Tight:wght@400;500;600&display=swap" as="style"/><link rel="preload" href="/_next/static/immutable/chunks/3xs64eipd7-el.css" as="style"/>
1<script type="application/ld+json" data-next-head="">{"@context":"https://schema.org","@type":"SoftwareApplication","name":"Billplz","applicationCategory":"FinanceApplication","operatingSystem":"Web","offers":{"@type":"Offer","lowPrice":"0","priceCurrency":"MYR","offerCount":"3"},"description":"Online payment gateway for Malaysian businesses with features for payment collection, management, and business growth."}</script>
1<script type="application/ld+json" data-next-head="">{"@context":"https://schema.org","@type":"WebSite","name":"Billplz","url":"https://main.billplz.com"}</script>
1<link href="https://fonts.googleapis.com/css2?family=Inter:ital,opsz,wght@0,14..32,100..900;1,14..32,100..900&family=Roboto+Serif:ital,opsz,wght@0,8..144,100..900;1,8..144,100..900&display=swap" rel="stylesheet"/><link href="https://fonts.googleapis.com/css2?family=Inter+Tight:ital,wght@0,100..900;1,100..900&display=swap" rel="stylesheet"/><link rel="stylesheet" href="/_next/static/immutable/chunks/3xs64eipd7-el.css" data-n-g=""/><noscript data-n-css=""></noscript>
1<script src="/_next/static/immutable/chunks/2l3_nl_7tsz5q.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/1-6o938ww4t9l.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/1sstd1oep4_0o.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/2zd406abgjdid.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/turbopack-0q8dwwx488_vp.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/1kmurcrwo5qd4.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/0-stpnhrec7j7.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/21a4fzlz-as7u.js" defer=""></script>
1<script src="/_next/static/immutable/chunks/turbopack-022ar67m_gru6.js" defer=""></script>
1<script src="/_next/static/build-TfctsWXpff2fKS/_buildManifest.js?dpl=dpl_ET3ut9gLNFT7gDBHfWE4Mt3A2d6U" defer=""></script>
1<script src="/_next/static/build-TfctsWXpff2fKS/_ssgManifest.js?dpl=dpl_ET3ut9gLNFT7gDBHfWE4Mt3A2d6U" defer=""></script>
1<script src="/_next/static/build-TfctsWXpff2fKS/_clientMiddlewareManifest.js?dpl=dpl_ET3ut9gLNFT7gDBHfWE4Mt3A2d6U" defer=""></script>
1</head><body class="antialiased"><div id="__next"><div class="layout page-blog"><header class="header-container"><div class="header-container__motion" style="transform:none"><div class="header"><div class="header__wrapper header__wrapper--billplz container"><a class="header__logo header__logo--billplz" aria-label="Billplz Home" href="/"><svg aria-hidden="true" width="75.7" height="16" viewBox="0 0 75.7 16"><use href="#logo"></use></svg></a><nav class="header__nav"><div class="header__nav-link" data-dropdown="dropdown-products" aria-expanded="false">Products<svg aria-hidden="true" class="icon-dropdown" style="transform:none"><use href="#dropdown"></use></svg></div><a class="header__nav-link" href="/pricing">Pricing</a><div class="header__nav-link" data-dropdown="dropdown-developers" aria-expanded="false">Developers<svg aria-hidden="true" class="icon-dropdown" style="transform:none"><use href="#dropdown"></use></svg></div><div class="header__nav-link" data-dropdown="dropdown-resources" aria-expanded="false">Resources<svg aria-hidden="true" class="icon-dropdown" style="transform:none"><use href="#dropdown"></use></svg></div><a class="header__nav-link" href="/support">Support</a></nav><div class="header__cta"><a class="button button--grey button--xs" href="https://dashboard.billplz-sandbox.com/">Log in</a><a class="button button--primary button--xs" href="https://dashboard.billplz-sandbox.com/enterprise/signup">Sign up</a></div><button class="header__mobile-trigger" aria-label="Toggle menu" aria-expanded="false" aria-controls="mobile-menu"><svg viewBox="0 0 24 24" width="24" height="24" aria-hidden="true"><path class="line line-1" d="M4 7h16" stroke="currentColor" stroke-width="2" stroke-linecap="round"></path><path class="line line-2" d="M4 17h16" stroke="currentColor" stroke-width="2" stroke-linecap="round"></path></svg></button></div></div></div><div id="mobile-menu" class="header__mobile-menu banner-active"><nav class="header__mobile-nav"><div class="header__mobile-title">Products<svg aria-hidden="true" class="icon"><use href="#chevron-right"></use></svg>Payments</div><a class="header__mobile-link" href="/collection">Collection</a><a class="header__mobile-link" href="/payment-order">
1Payment Order</a><a class="header__mobile-link" href="/pricing">Pricing</a><div class="header__mobile-title">Products<svg aria-hidden="true" class="icon"><use href="#chevron-right"></use></svg>E-commerce</div><a class="header__mobile-link" target="_blank" href="https://catalog.billplz-sandbox.com/link">Catalog Link<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://catalog.billplz-sandbox.com/">Catalog Store<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><div class="header__mobile-title">Products<svg aria-hidden="true" class="icon"><use href="#chevron-right"></use></svg>More</div><a class="header__mobile-link" href="/payment-methods">Payment methods</a><a class="header__mobile-link" href="/plugins">Plugins</a><div class="header__mobile-title">Developers</div><a class="header__mobile-link" href="/integrations">Integrations</a><a class="header__mobile-link" href="/plugins">Plugins</a><a class="header__mobile-link" target="_blank" href="https://www.billplz-sandbox.com/api">API documentation<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://www.billplz-sandbox.com/">Sandbox<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://github.com/billplz">Github<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://www.facebook.com/groups/billplzdevjam/">Dev Community<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><div class="header__mobile-title">Resources</div><a class="header__mobile-link" target="_blank" href="https://status.billplz-sandbox.com/">System status<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://check.billplz.com/">Transaction status<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" target="_blank" href="https://fpxstatus.billplz.com/">Bank status<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><a class="header__mobile-link" href="/customers">Customers</a><div class="header__mobile-title">Support</div><a class="header__mobile-link" href="/support">Help center</a><a class="header__mobile-link" href="/contact">Contact</a><a class="header__mobile-link" target="_blank" href="https://support.billplz.com/guide">Guide<svg aria-hidden="true" class="icon-external"><use href="#arrow-up-right"></use></svg></a><div class="header__mobile-title">Company</div><a class="header__mobile-link" href="/about">About</a><a class="header__mobile-link" href="/security">Security</a><a class="header__mobile-link" href="/referral">Referral</a><a class="header__mobile-link" href="/terms#agreement">Terms</a><a class="header__mobile-link" href="/terms#privacy">Privacy</a><a class="header__mobile-link" href="/blog">Blog</a><div class="header__mobile-cta"><a class="button button--grey " href="https://dashboard.billplz-sandbox.com/">Log in</a><a class="button button--primary " href="https://dashboard.billplz-sandbox.com/enterprise/signup">Sign up</a></div></nav></div></header><main class="main" id="main-content " role="main"><section class="hero hero--full-width hero--compact" aria-labelledby="hero-title"><div class="container"><div class="blog-hero-container"><h1 id="hero-title" class="hero__title">Payments in Malaysia, explained</h1><p class="blog-hero-subtitle">Comparisons, how-tos, and stories from the Billplz team.<!-- --> <a target="_blank" class="text-link" href="https://www.billplz.com/api">Looking for API docs?</a></p></div></div></section><section class="section blog-section" aria-label="Blog articles"><div class="container"><div aria-hidden="true"></div><div class="blog__sticky"><div class="blog__controls"><div class="blog__tabs" role="tablist" aria-label="Filter blog posts"><button type="button" role="tab" data-tab-id="" aria-selected="true" class="blog__tab blog__tab--active">All</button><button type="button" role="tab" data-tab-id="news" aria-selected="false" class="blog__tab ">News</button><button type="button" role="tab" data-tab-id="products" aria-selected="false" class="blog__tab ">Products</button><button type="button" role="tab" data-tab-id="insights" aria-selected="false" class="blog__tab ">Insights</button></div><div class="blog__view-toggle" role="group" aria-label="Toggle view"><button type="button" class="blog__view-button blog__view-button--active" aria-pressed="true" aria-label="Grid view">
1<svg width="16" height="16" viewBox="0 0 16 16" fill="none" xmlns="http://www.w3.org/2000/svg" aria-hidden="true"><rect x="1.5" y="1.5" width="5" height="5" rx="1" fill="currentColor"></rect><rect x="9.5" y="1.5" width="5" height="5" rx="1" fill="currentColor"></rect><rect x="1.5" y="9.5" width="5" height="5" rx="1" fill="currentColor"></rect><rect x="9.5" y="9.5" width="5" height="5" rx="1" fill="currentColor"></rect></svg></button><button type="button" class="blog__view-button " aria-pressed="false" aria-label="List view"><svg width="16" height="16" viewBox="0 0 16 16" fill="none" xmlns="http://www.w3.org/2000/svg" aria-hidden="true"><path d="M2 4h12M2 8h12M2 12h12" stroke="currentColor" stroke-width="1.5" stroke-linecap="round"></path></svg></button></div></div></div><div><div class=" blog-container news-container"><a href="/blog/fpx-vs-duitnow-malaysia"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/250928_01_01_0ae6610eea.webp" alt="FPX vs DuitNow: Malaysia's two payment rails explained" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>FPX vs DuitNow: Malaysia's two payment rails explained</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Sep 28, 2026</div></div></div></article></a><a href="/blog/accept-credit-card-payments-malaysia"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260922_01_01_97356128be.webp" alt="How to accept credit card payments in Malaysia (2026)" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>How to accept credit card payments in Malaysia (2026)</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Sep 22, 2026</div></div></div></article></a></div></div><div><div class=" blog-container regular-container"><a href="/blog/malaysia-payment-infrastructure-independence"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260914_01_01_8875dc5497.webp" alt="Malaysia built its own payment system. Here is what that took." loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Malaysia built its own payment system. Here is what that took.</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Sep 14, 2026</div></div></div></article></a><a href="/blog/digital-payments-malaysia-statistics-2025"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260908_01_01_f4e084d040.webp" alt="538 digital payments per person: Malaysia's 2025 cashless data" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>538 digital payments per person: Malaysia's 2025 cashless data</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Sep 8, 2026</div></div></div></article></a><a href="/blog/qr-interoperability-malaysia-duitnow"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260901_01_01_bc3d0257e1.webp" alt="Malaysia is phasing out proprietary QR codes: what merchants need to know" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Malaysia is phasing out proprietary QR codes: what merchants need to know</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Sep 1, 2026</div></div></div></article></a><a href="/blog/education-fee-collection-malaysia-fpx-duitnow"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260824_01_01_4d6b66be13.webp" alt="Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Aug 25, 2026</div></div></div></article></a><a href="/blog/zakat-religious-collection-malaysia"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260814_01_01_7f3a091b3a.webp" alt="Zakat and religious collection in Malaysia: how institutions accept payments online" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Zakat and religious collection in Malaysia: how institutions accept payments online</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Aug 14, 2026</div></div></div></article></a><a href="/blog/government-payment-collection-malaysia-fpx-duitnow"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_01_01_622bf144cf.webp" alt="How Malaysian government agencies collect payments online with FPX and DuitNow" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>How Malaysian government agencies collect payments online with FPX and DuitNow</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Aug 11, 2026</div></div></div></article></a><a href="/blog/insights/billplz-vs-hitpay-malaysia"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260715_01_01_bbba0db
11ce.webp" alt="Billplz vs HitPay: fees, settlement, and support compared" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Billplz vs HitPay: fees, settlement, and support compared</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Jul 29, 2026</div></div></div></article></a><a href="/blog/myinvois-e-invoicing-malaysia"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260720_01_01_8ad6f64370.webp" alt="MyInvois e-invoicing in Malaysia: what you need to know and how payments connect" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>MyInvois e-invoicing in Malaysia: what you need to know and how payments connect</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Jul 21, 2026</div></div></div></article></a><a href="/blog/is-billplz-safe"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_05_01_c77f5d315d.webp" alt="Is Billplz safe? The security and compliance stack" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Is Billplz safe? The security and compliance stack</h4></div><div class="blog-article-meta"><div class="blog-article-category">Insights</div><div class="blog-article-date">Jul 17, 2026</div></div></div></article></a><a href="/blog/products/merchant-discount-rate-guide"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_ffade2a5cd.webp" alt="Merchant Discount Rate: What is it & its impact on transactions" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Merchant Discount Rate: What is it & its impact on transactions</h4></div><div class="blog-article-meta"><div class="blog-article-category">Products</div><div class="blog-article-date">Dec 2, 2025</div></div></div></article></a><a href="/blog/products/stripe-vs-paypal-which-should-you-choose"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_e655957bb9.webp" alt="Stripe vs PayPal: Which payment gateway should you choose?" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Stripe vs PayPal: Which payment gateway should you choose?</h4></div><div class="blog-article-meta"><div class="blog-article-category">Products</div><div class="blog-article-date">Dec 2, 2025</div></div></div></article></a><a href="/blog/products/wise-vs-paypal-malaysia-payment-comparison"><article><div class="blog-container-article-image"><img src="https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_cb3b5dbf02.webp" alt="Wise vs PayPal: Which payment gateway should you choose?" loading="lazy"/></div><div style="width:100%"><div style="display:flex;align-items:start;justify-content:space-between;width:100%"><h4>Wise vs PayPal: Which payment gateway should you choose?</h4></div><div class="blog-article-meta"><div class="blog-article-category">Products</div><div class="blog-article-date">Dec 2, 2025</div></div></div></article></a></div></div><div class="blog-footer-container "><button class="button button--grey">Load More</button></div></div></section></main><footer class="footer"><div class="section section--no-background footer__hero"><div class="container"><h2 class="section-title section-title--inverted section-title--spaced-sm">Start accepting<br/>payments today</h2><div class="footer__hero-buttons"><a class="button button--primary button--inverted" href="https://dashboard.billplz-sandbox.com/enterprise/signup">Get started for free<svg aria-hidden="true" class="button--icon"><use href="#chevron-right"></use></svg></a><a class="button button--secondary button--transparent" href="/contact">Contact sales</a></div></div></div><div class="section-divider section-divider--dark"><div class="container"></div></div>
1<div class="section section--no-background footer__content"><div class="container"><div class="footer__left"><div class="footer__logo footer__logo--billplz"><svg aria-hidden="true"><use href="#logo"></use></svg></div><div class="footer__taglines"><div>Fastest.</div><div>Lowest.</div><div>Possible.</div></div></div><div class="footer__nav-container"><div class="footer__nav-section"><div class="footer__group"><div class="footer__group-title">Products</div><div class="footer__links"><a href="/collection">Collection</a><a href="/payment-order">Payment Order</a><a target="_blank" href="https://catalog.billplz-sandbox.com/link">Catalog Link</a><a target="_blank" href="https://catalog.billplz-sandbox.com/commerce">Catalog Store</a><a target="_blank" href="https://zakat.billplz-sandbox.com">Zakat</a><a href="/pricing">Pricing</a></div></div></div><div class="footer__nav-section"><div class="footer__group"><div class="footer__group-title">Developers</div><div class="footer__links"><a href="/integrations">Integrations</a><a target="_blank" href="https://www.billplz-sandbox.com/api">API docs</a><a href="/plugins">Plugins</a><a target="_blank" href="https://dashboard.billplz-sandbox.com/enterprise/signup">Sandbox</a><a target="_blank" href="https://www.facebook.com/groups/billplzdevjam/">Community</a></div></div></div><div class="footer__nav-section"><div class="footer__group"><div class="footer__group-title">Company</div><div class="footer__links"><a href="/about">About</a><a href="/security">Security</a><a href="/terms">Terms</a><a href="/brand">Brand</a><a href="/customers">Customers</a><a href="/referral">Referral</a><a href="/blog">Blog</a></div></div></div><div class="footer__nav-section"><div class="footer__group"><div class="footer__group-title">Support</div><div class="footer__links"><a href="/support">Help center</a><a target="_blank" href="https://support.billplz.com/guide">Guide</a><a target="_blank" href="https://www.youtube.com/@mybillplz">Tutorials</a></div></div></div><div class="footer__nav-section"><div class="footer__group"><div class="footer__group-title">Resources</div><div class="footer__links"><a target="_blank" href="https://status.billplz-sandbox.com/">System status</a><a target="_blank" href="https://check.billplz.com/">Transaction status</a><a target="_blank" href="https://fpxstatus.billplz.com/">Bank status</a></div></div></div></div><div class="footer__bottom"><div class="footer__info"><span aria-label="Copyright 2026 Billplz Sendirian Berhad">© <!-- -->2026<!-- --> Billplz Sdn Bhd</span></div><div class="footer__social"><a target="_blank" class="footer__social-link" aria-label="Visit Billplz on Facebook" href="https://www.facebook.com/mybillplz"><svg aria-hidden="true"><use href="#icon-facebook"></use></svg></a><a target="_blank" class="footer__social-link" aria-label="Visit Billplz on Twitter" href="https://x.com/billplz"><svg aria-hidden="true"><use href="#icon-twitter"></use></svg></a><a target="_blank" class="footer__social-link" aria-label="Visit Billplz on Linkedin" href="https://www.linkedin.com/company/billplz/"><svg aria-hidden="true"><use href="#icon-linkedin"></use></svg></a><a target="_blank" class="footer__social-link" aria-label="Watch Billplz's tutorials on Youtube" href="https://www.youtube.com/@mybillplz"><svg aria-hidden="true"><use href="#icon-youtube"></use></svg></a><a target="_blank" class="footer__social-link" aria-label="Visit Billplz on Github" href="https://github.com/billplz"><svg aria-hidden="true"><use href="#icon-github"></use></svg></a></div></div></div></div></footer><div class="floating-social floating-social--right"><button class="floating-social__toggle " aria-label="Open social menu" aria-expanded="false"><span class="floating-social__toggle-icon"><svg xmlns="http://www.w3.org/2000/svg" fill="none" viewBox="0 0 24 24" stroke-width="1.5" stroke="currentColor" class="floating-social__icon-chat"><path stroke-linecap="round" stroke-linejoin="round" d="M20.25 8.511c.884.284 1.5 1.128 1.5 2.097v4.286c0 1.136-.847 2.1-1.98 2.193-.34.027-.68.052-1.02.072v3.091l-3-3c-1.354 0-2.694-.055-4.02-.163a2.115 2.115 0 0 1-.825-.242m9.345-8.334a2.126 2.126 0 0 0-.476-.
1095 48.64 48.64 0 0 0-8.048 0c-1.131.094-1.976 1.057-1.976 2.192v4.286c0 .837.46 1.58 1.155 1.951m9.345-8.334V6.637c0-1.621-1.152-3.026-2.76-3.235A48.455 48.455 0 0 0 11.25 3c-2.115 0-4.198.137-6.24.402-1.608.209-2.76 1.614-2.76 3.235v6.226c0 1.621 1.152 3.026 2.76 3.235.577.075 1.157.14 1.74.194V21l4.155-4.155"></path></svg><svg xmlns="http://www.w3.org/2000/svg" fill="none" viewBox="0 0 24 24" stroke-width="1.5" stroke="currentColor" class="floating-social__icon-close"><path stroke-linecap="round" stroke-linejoin="round" d="M6 18 18 6M6 6l12 12"></path></svg></span></button></div></div></div>
1<script id="__NEXT_DATA__" type="application/json">{"props":{"pageProps":{"newsArticles":[{"id":590,"documentId":"q9hpi7q4yh0ecztjmm31vvht","title":"FPX vs DuitNow: Malaysia's two payment rails explained","slug":"fpx-vs-duitnow-malaysia","createdAt":"2026-09-28T05:13:56.123Z","updatedAt":"2026-09-28T05:47:44.931Z","publishedAt":"2026-09-28T05:47:45.018Z","publishDate":"2026-09-28T05:13:56.123Z","cover":{"id":162,"documentId":"txniuzjrau9bkug4sdpz3dnu","name":"250928_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_250928_01_01_0ae6610eea.webp","hash":"large_250928_01_01_0ae6610eea","mime":"image/webp","name":"large_250928_01_01.webp","path":null,"size":22.4,"width":1000,"height":556,"sizeInBytes":22402},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_250928_01_01_0ae6610eea.webp","hash":"small_250928_01_01_0ae6610eea","mime":"image/webp","name":"small_250928_01_01.webp","path":null,"size":9.27,"width":500,"height":278,"sizeInBytes":9266},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_250928_01_01_0ae6610eea.webp","hash":"medium_250928_01_01_0ae6610eea","mime":"image/webp","name":"medium_250928_01_01.webp","path":null,"size":15.5,"width":750,"height":417,"sizeInBytes":15496},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_250928_01_01_0ae6610eea.webp","hash":"thumbnail_250928_01_01_0ae6610eea","mime":"image/webp","name":"thumbnail_250928_01_01.webp","path":null,"size":3.36,"width":245,"height":136,"sizeInBytes":3356}},"hash":"250928_01_01_0ae6610eea","ext":".webp","mime":"image/webp","size":52.54,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/250928_01_01_0ae6610eea.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-28T05:43:23.733Z","updatedAt":"2026-09-28T05:43:23.733Z","publishedAt":"2026-09-28T05:43:23.733Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":317,"metaTitle":"FPX vs DuitNow: Malaysia's two payment rails explained","metaDescription":"FPX and DuitNow are both operated by PayNet but do different jobs. Compare Malaysia's two payment rails, and find out whether FPX is being discontinued.","metaKeywords":"FPX vs DuitNow Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/250928_01_01_0ae6610eea.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"url":"https://main.billplz.com/blog/fpx-vs-duitnow-malaysia","@type":"Article","author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"FPX vs DuitNow: Malaysia's two payment rails explained","keywords":["FPX vs DuitNow","FPX Malaysia","DuitNow QR","FPX meaning","DuitNow Online Banking Wallets","DOBW","FPX sunset","PayNet payment rails"],"publisher":{"url":"https://main.billplz.com","logo":{"url":"https://main.billplz.com/images/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"inLanguage":"en-MY","description":"FPX and DuitNow are both operated by PayNet but do different jobs. Compare Malaysia's two payment rails, and find out whether FPX is being discontinued.","dateModified":"","datePublished":"","articleSection":"Insights"},{"@type":"FAQPage","mainEntity":[{"name":"Is DuitNow replacing FPX?","@type":"Question","acceptedAnswer":{"text":"Progressively, not in a single switchover. DuitNow Online Banking/Wallets is replacing FPX as the online checkout method, but FPX remains the standard at checkout today and no end date has been announced. For merchants, the payment gateway handles the transition, so there is nothing to migrate.","@type":"Answer"}},{"name":"Can I use both FPX and DuitNow QR on my payment page?","@type":"Question","acceptedAnswer":{"text":"Yes. They are separate payment methods that can appear together on the same payment page. On Billplz, DuitNow QR appears alongside FPX once it is enabled on your collection, and the customer chooses which to use.","@type":"Answer"}},{"name":"What is DuitNow Online Banking/Wallets?","@type":"Question","acceptedAnswer":{"text":"DuitNow Online Banking/Wallets (DOBW) is the online checkout service running on PayNet's Real-time Retail Payments Platform, covering both bank accounts and e-wallet apps. The flow is close to FPX: choose your bank or wallet, get redirected, authorize the payment. The main difference is that DOBW approves the payment inside the banking or wallet app without a one-time password. Banks have adopted it on their own schedules rather than on a common date.","@type":"Answer"}},{"name":"Which payment method do Malaysian consumers prefer?","@type":"Question","acceptedAnswer":{"text":"It depends on where they are paying. Bank-login payments remain the default for online checkout and bill payments, while DuitNow QR dominates in-person payments, reaching 3 billion transactions in 2025 according to Bank Negara Malaysia's Annual Report 2025. Malaysia recorded 18.4 billion e-payment transactions in total that year.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"FPX vs DuitNow: Malaysia's two payment rails explained","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"FPX and DuitNow are both operated by PayNet but do different jobs. Compare Malaysia's two payment rails, and find out whether FPX is being discontinued.","dateModified":"2026-09-28T05:47:43.432Z","datePublished":"2026-09-28T05:13:56.123Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/fpx-vs-duitnow-malaysia","@type":"WebPage"}}},"blocks":[{"id":564,"body":"FPX is Malaysia's online banking payment system. DuitNow is the country's newer instant payment platform. Both are operated by [PayNet](https://paynet.my), and they are not competing standards. FPX moves money bank to bank when someone pays online or settles a bill. DuitNow powers QR payments, instant transfers by phone number, and cross-border payments. Most Malaysian providers, including Billplz, support both. FPX is not being switched off either, and no end date has been announced. If you are deciding which to offer, the short answer for most businesses is both, and this article explains why.\n\n## What is FPX\n\nFPX stands for Financial Process Exchange. It launched in 2004 and has been the backbone of online banking payments in Malaysia ever since.\n\nThe flow is familiar to anyone who has bought something online in Malaysia. At checkout, the customer picks their bank, gets redirected to their own online banking login, authorizes the payment, and returns to the merchant's site. Funds move directly from the buyer's bank account to the merchant's account. No card is involved.\n\nPersonal accounts can pay up to MYR 30,000.00 per transaction, and corporate accounts up to MYR 1,000,000.00. Either way, the customer's own internet banking limit applies if it is lower.\n\nMore than 20 banks participate, which is why FPX coverage feels close to universal.\n\n## What is DuitNow\n\nDuitNow is not one product. It is an umbrella covering several services that all run on PayNet's Real-time Retail Payments Platform.\n\n### DuitNow Transfer\n\nInstant transfers using a proxy ID instead of a bank account number: a mobile number, an IC number, or a business registration number. This is primarily a transfer service rather than a checkout method.\n\n### DuitNow QR\n\nInteroperable QR code payments. One QR code accepts payment from any participating bank or e-wallet app, which ends the old problem of merchants displaying a wall of different QR codes. DuitNow QR reached [3 billion transactions in 2025](https://www.bnm.gov.my/publications/ar2025), double the 1.5 billion in 2024, across nearly 3 million registered touchpoints. It also works in person, which FPX does not.\n\n### DuitNow Online Banking/Wallets\n\nUsually shortened to DOBW. This is the online checkout service running on the DuitNow rail, and it covers both bank accounts and e-wallet apps. The flow is close to FPX: pick your bank or wallet, get redirected, authorize. The difference customers notice is authentication, because DOBW approves the payment inside the banking or wallet app without a one-time password.\n\nBanks have moved to it on their own schedules rather than a common date. Maybank switched its checkout interface in March 2025, and Fiuu became the first merchant acquirer to migrate FPX traffic to DOBW in May 2026.\n\n### DuitNow Request\n\nRequest-to-pay. The merchant sends a payment request that lands in the customer's banking app for approval.\n\n### Cross-border DuitNow\n\nDuitNow QR is linked with PromptPay in Thailand, QRIS in Indonesia, and PayNow in Singapore, so visitors can pay Malaysian merchants from their home banking apps. Cross-border payment linkages grew 179% in 2025.\n\n## FPX vs DuitNow: key differences\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003c/td\u003e\u003ctd\u003eFPX\u003c/td\u003e\u003ctd\u003eDuitNow\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eWhat it is\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eOnline banking payment system\u003c/td\u003e\u003ctd\u003eInstant payment platform (QR, transfer, request)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eOperated by\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003ePayNet\u003c/td\u003e\u003ctd\u003ePayNet\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eLaunched\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2004\u003c/td\u003e\u003ctd\u003e2018 (DuitNow Transfer); QR expanded 2019 to 2022\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eHow the customer pays\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eSelects bank, logs in, authorizes\u003c/td\u003e\u003ctd\u003eScans a QR code, approves a request, or uses a proxy ID\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eAuthentication\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBank login, OTP where the bank requires it\u003c/td\u003e\u003ctd\u003eIn-app approval, no OTP on DOBW\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTransaction limit\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eUp to MYR 30,000.00 (personal); up to MYR 1,000,000.00 (corporate)\u003c/td\u003e\u003ctd\u003eVaries by service and by bank\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eWorks in store\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNo, online only\u003c/td\u003e\u003ctd\u003eYes, via DuitNow QR\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCross-border\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNo\u003c/td\u003e\u003ctd\u003eYes, linked with Thailand, Indonesia, and Singapore\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eAcceptance points\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eOnline merchants\u003c/td\u003e\u003ctd\u003eOnline and physical, nearly 3 million QR touchpoints\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSettlement on Billplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNext business day\u003c/td\u003e\u003ctd\u003eNext day\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## Where they overlap\n\nThe overlap is narrower than the names suggest, and sits in one place: online banking checkout.\n\nDuitNow Online Banking/Wallets is progressively replacing FPX for that flow. Both give the customer the same redirect-and-authorize experience, so the change is not something a shopper would notice beyond a different login screen. FPX remains the standard at checkout today.\n\nOutside that one overlap, the two do genuinely different jobs. FPX has no in-store equivalent. DuitNow QR has no bank-login flow. They are complements, not substitutes.\n\n## Is FPX being discontinued?\n\nNo end date has been announced. PayNet still lists FPX and DuitNow as separate, active services, and no switch-off date has been published.\n\nWhat is happening is a gradual migration rather than a cutoff. Banks are moving their checkout flow to DOBW on their own schedules, starting with Maybank in March 2025. On the acquirer side, Fiuu became the first to migrate FPX traffic to DOBW in May 2026.\n\nIf you accept payments through a gateway, none of this needs action from you. The gateway handles which rail a transaction runs on, and your integration does not change.\n\n## Which should your business use\n\nIt depends on where your customers pay you, and for most businesses it ends up being both.\n\n**Selling online.** Bank-login payments are the primary method for Malaysian e-commerce, whether they run on FPX or DOBW. Customers know the flow and trust it.\n\n**Taking payments in person.** DuitNow QR is the only one of the two that works here. FPX is online-only.\n\n**Billing and invoicing.** FPX is well established here, where the payer is settling a specific amount.\n\n**Serving visitors from Thailand, Indonesia, or Singapore.** DuitNow QR, through the cross-border links with PromptPay, QRIS, and PayNow.\n\n**A mix of the above.** Offer both and let the customer choose. A gateway presents the available methods on one page, so supporting both is a configuration decision rather than two integrations.\n\nThere is no winner here. A business that only sells online and one that also runs a physical counter will reach different c
1onclusions, and both will be right.\n\n## FPX and DuitNow on Billplz\n\nBillplz is a certified PayNet system integrator and supports both rails. On the Billplz payment page, the customer picks from the methods you have enabled: FPX, Wallet, Card, and Instalments. DuitNow QR appears alongside FPX once it is enabled on your collection, so adding a method is a setting rather than a development project. For what is available, see [payment methods](https://main.billplz.com/payment-methods), and for settlement timing see [pricing](https://main.billplz.com/pricing).\n\nFor the wider picture, [Malaysia is phasing out proprietary QR codes](https://main.billplz.com/blog/qr-interoperability-malaysia-duitnow) covers the regulatory shift behind DuitNow QR, and [Malaysia's 2025 cashless data](https://main.billplz.com/blog/digital-payments-malaysia-statistics-2025) has the full volume breakdown.\n\n---\n\n## FAQs\n\n### Is DuitNow replacing FPX?\n\nProgressively, not in a single switchover. DuitNow Online Banking/Wallets is replacing FPX as the online checkout method, but FPX remains the standard at checkout today and no end date has been announced. For merchants, the payment gateway handles the transition, so there is nothing to migrate.\n\n### Can I use both FPX and DuitNow QR on my payment page?\n\nYes. They are separate payment methods that can appear together on the same payment page. On Billplz, DuitNow QR appears alongside FPX once it is enabled on your collection, and the customer chooses which to use.\n\n### What is DuitNow Online Banking/Wallets?\n\nDuitNow Online Banking/Wallets (DOBW) is the online checkout service running on PayNet's Real-time Retail Payments Platform, covering both bank accounts and e-wallet apps. The flow is close to FPX: choose your bank or wallet, get redirected, authorize the payment. The main difference is that DOBW approves the payment inside the banking or wallet app without a one-time password. Banks have adopted it on their own schedules rather than on a common date.\n\n### Which payment method do Malaysian consumers prefer?\n\nIt depends on where they are paying. Bank-login payments remain the default for online checkout and bill payments, while DuitNow QR dominates in-person payments, reaching 3 billion transactions in 2025 according to Bank Negara Malaysia's Annual Report 2025. Malaysia recorded 18.4 billion e-payment transactions in total that year.\n\n---\n\n## Why most businesses need both\n\nFPX and DuitNow are two rails from the same operator, built for different moments. FPX is how Malaysians pay online from a bank account. DuitNow is how they pay by QR, by phone number, and across borders. Neither is going away this year. The question is not which one wins, but which your customers need, and for most businesses that is both.","__component":"shared.rich-text"}]},{"id":587,"documentId":"pdsa2du1b1ih9d56xlbfhk2o","title":"How to accept credit card payments in Malaysia (2026)","slug":"accept-credit-card-payments-malaysia","createdAt":"2026-09-22T05:56:23.774Z","updatedAt":"2026-09-22T06:28:40.799Z","publishedAt":"2026-09-22T06:28:40.890Z","publishDate":"2026-09-22T05:56:23.774Z","cover":{"id":161,"documentId":"qobd4vzso5ta0o625hjydhoq","name":"260922_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260922_01_01_97356128be.webp","hash":"large_260922_01_01_97356128be","mime":"image/webp","name":"large_260922_01_01.webp","path":null,"size":9.51,"width":1000,"height":556,"sizeInBytes":9514},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260922_01_01_97356128be.webp","hash":"small_260922_01_01_97356128be","mime":"image/webp","name":"small_260922_01_01.webp","path":null,"size":3.52,"width":500,"height":278,"sizeInBytes":3524},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260922_01_01_97356128be.webp","hash":"medium_260922_01_01_97356128be","mime":"image/webp","name":"medium_260922_01_01.webp","path":null,"size":5.97,"width":750,"height":417,"sizeInBytes":5974},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260922_01_01_97356128be.webp","hash":"thumbnail_260922_01_01_97356128be","mime":"image/webp","name":"thumbnail_260922_01_01.webp","path":null,"size":1.57,"width":245,"height":136,"sizeInBytes":1572}},"hash":"260922_01_01_97356128be","ext":".webp","mime":"image/webp","size":44.04,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260922_01_01_97356128be.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-22T06:26:49.826Z","updatedAt":"2026-09-22T06:26:49.826Z","publishedAt":"2026-09-22T06:26:49.826Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":314,"metaTitle":"How to accept credit card payments in Malaysia (2026)","metaDescription":"A step-by-step guide to accepting credit card payments in Malaysia. Learn what you need, the costs involved, and how to set up card payments for your business.","metaKeywords":"accept credit card payments Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260922_01_01_97356128be.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"@id":"https://main.billplz.com/blog/accept-credit-card-payments-malaysia#article","@type":"Article","image":{"url":"","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"How to accept credit card payments in Malaysia in 2026","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"A step-by-step guide to accepting credit card payments in Malaysia. Learn what you need, the costs involved, and how to set up card payments for your business.","dateModified":"","datePublished":"","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/accept-credit-card-payments-malaysia"},{"@id":"https://main.billplz.com/blog/accept-credit-card-payments-malaysia#howto","name":"How to accept credit card payments in Malaysia","step":[{"name":"Register your business","text":"You need an SSM-registered business (sole proprietor, partnership, or Sdn Bhd), or equivalent registration for NGOs and associations.","@type":"HowToStep"},{"name":"Choose a payment gateway or card terminal","text":"For online card payments, sign up with a payment gateway. For in-store payments, get a card terminal from your bank or a terminal provider.","@type":"HowToStep"},{"name":"Complete KYB verification","text":"Your payment provider will require Know Your Business verification: SSM certificate, director IC, bank statement, and a business description.","@type":"HowToStep"},{"name":"Enable card payments","text":"Once verified, enable Visa and Mastercard on your payment gateway or terminal. Card payments will appear as an option for your customers.","@type":"HowToStep"}],"@type":"HowTo"},{"@id":"https://main.billplz.com/blog/accept-credit-card-payments-malaysia#faq","@type":"FAQPage","mainEntity":[{"name":"How long does it take to receive credit card payment settlements?","@type":"Question","acceptedAnswer":{"text":"Settlement timing depends on your payment provider and the payment method. For online card payments through Billplz, settlement is T+2 business days. FPX settles next business day. Check your provider's pricing page for their specific timelines.","@type":"Answer"}},{"name":"Do I need to be PCI DSS certified to accept credit card payments?","@type":"Question","acceptedAnswer":{"text":"If you use a payment gateway, the gateway handles PCI DSS compliance on your behalf. Billplz is PCI DSS Level 1 certified, the highest level of payment card security compliance. You never see or store raw card numbers when using a payment gateway.","@type":"Answer"}},{"name":"Can I accept international credit cards?","@type":"Question","acceptedAnswer":{"text":"Yes. Most Malaysian payment gateways accept international Visa and Mastercard payments. International card transactions typically carry a higher merchant discount rate than domestic cards. Check your provider's pricing page for international card rates.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"How to accept credit card payments in Malaysia (2026)","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"A step-by-step guide to accepting credit card payments in Malaysia. Learn what you need, the costs involved, and how to set up card payments for your business.","dateModified":"2026-09-22T06:28:39.439Z","datePublished":"2026-09-22T05:56:23.774Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/accept-credit-card-payments-malaysia","@type":"WebPage"}}},"blocks":[{"id":561,"body":"To accept credit card payments in Malaysia, you need a registered business, a payment gateway (for online) or card terminal (for in-store), and KYB verification from your payment provider. Costs are based on the merchant discount rate (MDR), typically 1% to 3% per transaction depending on the payment method. This article walks through each step: what you need, how it works, what it costs, and how to get set up.\n\n## Why accept credit card payments\n\nAccepting card payments means accepting both credit and debit cards on the same infrastructure. The same terminal or payment gateway handles both.\n\nCard payments are crossing a milestone. Point-of-sale card transactions are projected to overtake ATM cash withdrawals in Malaysia for the first time, with POS accounting for 50.2% of total card transaction value compared to 49.8% for ATM cash (GlobalData, 2025 forecast).\n\nThe numbers behind that shift:\n\n* 9.9 million credit cards in circulation in Malaysia (BNM)\n* Debit card transactions grew 20.5% year on year, credit card transactions 10.9% (BNM Annual Report 2025)\n* Contactless payments reached 2 billion transactions in 2025, up 20.3% (BNM Annual Report 2025)\n* The average debit card transaction is MYR 69.00, meaning consumers are using cards for everyday spending, not just large purchases\n\nCredit card acceptance is not reserved for large businesses. Any SSM-registered Malaysian business can accept card payments through a payment gateway or terminal provider. International customers also expect it: for tourists and cross-border buyers, card payment is often the fallback when local methods are unavailable.\n\n## What you need to get started\n\n### A registered business\n\nYou need an SSM registration: sole proprietor, partnership, or Sdn Bhd. NGOs, associations, and government agencies can also accept card payments through their equivalent registrations. Your registration documents are part of the verification process with any payment provider.\n\n### A payment gateway for online payments\n\nA payment gateway handles card processing, security, and settlement for online transactions. When a customer enters their card details on your payment page, the gateway routes the transaction through the card network (Visa or Mastercard), authenticates it, and settles the funds to your bank account.\n\nPayment gateways vary by pricing model, settlement speed, and supported payment methods. Look for one that supports the methods your customers use: FPX for bank transfers, Card for Visa and Mastercard, and Wallet for e-wallets.\n\n### A card terminal for in-store payments\n\nIf you accept payments in person, you need a physical card terminal. Banks and terminal providers offer POS devices that accept tap-and-go (contactless), chip-and-PIN, and swipe transactions. Terminal costs typically include device rental and a per-transaction fee.\n\n### KYB verification\n\nEvery payment provider requires Know Your Business (KYB) verification before enabling card payments. The typical documents:\n\n* SSM certificate (or equivalent registration)\n* Director IC (identification card)\n* Bank statement\n* Business description\n\nVerification timelines vary. Some providers complete it within a few business days; others take longer depending on the business type.\n\n## Understanding the costs\n\nCard payment costs in Malaysia are built from several components. The headline number is the merchant discount rate (MDR), but it is not the full picture.\n\n### Merchant discount rate (MDR)\n\nThe MDR is the percentage fee charged per transaction. In Malaysia, MDR for card payments typically ranges from 1% to 3%, depending on:\n\n* Card type: debit cards are generally cheaper than credit cards\n* Card origin: domestic cards are cheaper than
1international cards\n* Payment method: FPX (bank transfer) is typically the lowest-cost method, followed by Wallet, then Card\n\nThe MDR is deducted from each transaction before settlement.\n\n### Per-transaction flat fees\n\nSome providers charge a fixed amount per transaction on top of the MDR. For small transactions, this flat fee can matter more than the percentage. If your average transaction is below MYR 50.00, compare the flat fee carefully across providers.\n\n### Setup and monthly fees\n\nSome payment gateways charge setup fees or monthly platform fees. Others offer a free plan with no upfront cost but a higher per-transaction rate. The trade-off: free plans suit businesses with lower transaction volumes, while paid plans with lower per-transaction rates save money at higher volumes.\n\n### Hidden costs to ask about\n\nBefore signing up with any provider, ask about:\n\n* Currency conversion markup on international card transactions\n* Chargeback fees\n* Refund processing fees\n* Minimum monthly transaction requirements\n\nThese costs are not always listed on the headline pricing page but can add up.\n\n## Online vs in-store card payments\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003c/td\u003e\u003ctd\u003eOnline\u003c/td\u003e\u003ctd\u003eIn-store\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eSetup\u003c/td\u003e\u003ctd\u003ePayment gateway integration\u003c/td\u003e\u003ctd\u003eCard terminal lease or purchase\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHow the customer pays\u003c/td\u003e\u003ctd\u003eEnters card details on a payment page\u003c/td\u003e\u003ctd\u003eTaps or inserts card at a terminal\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eSecurity\u003c/td\u003e\u003ctd\u003ePayment gateway handles PCI DSS compliance\u003c/td\u003e\u003ctd\u003eTerminal provider handles compliance\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eSettlement\u003c/td\u003e\u003ctd\u003eVia payment gateway to your bank account\u003c/td\u003e\u003ctd\u003eVia terminal provider to your bank account\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eBillplz\u003c/td\u003e\u003ctd\u003eYes (online card payments)\u003c/td\u003e\u003ctd\u003eNo (Billplz is online-only)\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\nMany businesses use both. Online handles your website, invoices, and payment links. In-store handles walk-in customers.\n\n## Security and compliance\n\n### PCI DSS\n\nAny business that processes, stores, or transmits card data must comply with the Payment Card Industry Data Security Standard (PCI DSS). In practice, if you use a payment gateway, the gateway handles PCI DSS compliance for you.\n\n[Billplz is PCI DSS Level 1 certified](https://main.billplz.com/security), the highest level of payment card security compliance. When your customers pay through Billplz, their card details are processed in a PCI DSS Level 1 environment. You never see or store raw card numbers.\n\n### 3D Secure\n\n3D Secure adds an authentication step for online card payments. The customer's bank verifies the transaction through a one-time password or biometric check. This reduces fraud and shifts liability away from the merchant. Payment gateways handle 3D Secure automatically.\n\n## How to accept credit card payments with Billplz\n\nBillplz is an online payment gateway for Malaysian businesses. It handles online card payments only. If you need in-store card acceptance, get a terminal from your bank or a terminal provider. Here is how online card payments work on the platform:\n\n1. Sign up at [main.billplz.com](https://main.billplz.com)\n2. Complete KYB verification with your business documents\n3. Once verified, enable Visa and Mastercard on your dashboard\n4. Card payments appear on your Billplz payment page alongside FPX, Wallet, and Instalments\n\nCard payments are available on all plans, including Basic. Supported networks are Visa and Mastercard, and settlement is T+2 business days. Billplz handles PCI DSS compliance, 3D Secure authentication, and settlement. Your customers see a clean payment page with all available methods. For developers, the integration works the same way regardless of payment method: one API, consistent callbacks and webhooks.\n\nFor current rates and plan details, see [Billplz pricing](https://main.billplz.com/pricing). For a full list of supported payment methods, visit [payment methods](https://main.billplz.com/payment-methods). For a breakdown of how card fees work, read the [merchant discount rate guide](https://main.billplz.com/blog/products/merchant-discount-rate-guide).\n\n---\n\n## FAQs\n\n### How long does it take to receive credit card payment settlements?\n\nSettlement timing depends on your payment provider and the payment method. For online card payments through Billplz, settlement is T+2 business days. FPX settles next business day. Check your provider's pricing page for their specific timelines.\n\n### Do I need to be PCI DSS certified to accept credit card payments?\n\nIf you use a payment gateway, the gateway handles PCI DSS compliance on your behalf. Billplz is PCI DSS Level 1 certified, the highest level of payment card security compliance. You never see or store raw card numbers when using a payment gateway.\n\n### Can I accept international credit cards?\n\nYes. Most Malaysian payment gateways accept international Visa and Mastercard payments. International card transactions typically carry a higher merchant discount rate than domestic cards. Check your provider's pricing page for international card rates.","__component":"shared.rich-text"}]}],"regularArticles":[{"id":584,"documentId":"bg39su92m8jyofzdmj69ft9k","title":"Malaysia built its own payment system. Here is what that took.","slug":"malaysia-payment-infrastru
1cture-independence","createdAt":"2026-09-14T04:14:20.255Z","updatedAt":"2026-09-14T07:40:49.300Z","publishedAt":"2026-09-14T07:40:49.419Z","publishDate":"2026-09-14T04:14:20.255Z","cover":{"id":160,"documentId":"r6cm26p12sghi6la0xqa3ssh","name":"260914_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260914_01_01_8875dc5497.webp","hash":"large_260914_01_01_8875dc5497","mime":"image/webp","name":"large_260914_01_01.webp","path":null,"size":3.1,"width":1000,"height":556,"sizeInBytes":3104},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260914_01_01_8875dc5497.webp","hash":"small_260914_01_01_8875dc5497","mime":"image/webp","name":"small_260914_01_01.webp","path":null,"size":1.43,"width":500,"height":278,"sizeInBytes":1426},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260914_01_01_8875dc5497.webp","hash":"medium_260914_01_01_8875dc5497","mime":"image/webp","name":"medium_260914_01_01.webp","path":null,"size":2.29,"width":750,"height":417,"sizeInBytes":2286},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260914_01_01_8875dc5497.webp","hash":"thumbnail_260914_01_01_8875dc5497","mime":"image/webp","name":"thumbnail_260914_01_01.webp","path":null,"size":0.55,"width":245,"height":136,"sizeInBytes":548}},"hash":"260914_01_01_8875dc5497","ext":".webp","mime":"image/webp","size":6.78,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260914_01_01_8875dc5497.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-14T05:38:25.465Z","updatedAt":"2026-09-14T05:38:25.465Z","publishedAt":"2026-09-14T05:38:25.466Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":311,"metaTitle":"Malaysia built its own payment system. Here is what that took.","metaDescription":"From foreign colonial banks to 538 digital payments per person per year. The story of how Malaysia built a world-class payment infrastru
1cture, and what happened to the companies on top of it.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260914_01_01_8875dc5497.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"@id":"https://main.billplz.com/blog/malaysia-payment-infrastructure-independence#article","@type":"Article","image":{"url":"","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Malaysia built its own payment system. Here is what that took.","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"inLanguage":"en-MY","description":"From foreign colonial banks to 538 digital payments per person per year. The story of how Malaysia built a world-class payment infrastructure, and what happened to the companies on top of it.","dateModified":"","datePublished":"","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/malaysia-payment-infrastructure-independence"}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Malaysia built its own payment system. Here is what that took.","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"From foreign colonial banks to 538 digital payments per person per year. The story of how Malaysia built a world-class payment infrastructure, and what happened to the companies on top of it.","dateModified":"2026-09-14T07:40:47.532Z","datePublished":"2026-09-14T04:14:20.255Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/malaysia-payment-infrastructure-independence","@type":"WebPage"}}},"blocks":[{"id":558,"body":"When Malaya gained independence in 1957, the banking system was built for export, not for Malaysians. The dominant names were British institutions: Chartered Bank, Eastern Bank, Mercantile Bank. Their primary business was financing tin and rubber trades. For most people in the newly independent nation, the financial system meant one thing: cash.\n\nSix years later, Sabah, Sarawak, and Singapore joined Malaya to form Malaysia. The financial system that would serve the new federation still had to be built.\n\nBank Negara Malaysia had been established in 1959, and over the following decades the country built its own banking sector and grew local financial institutions. But for payments, Malaysia remained largely cash-based well into the 1990s. Paying a bill meant a counter visit. Buying goods meant cash or cheques. Nearly four decades would pass between independence and the first shared electronic payment infrastru
1cture.\n\nSixty-three years after the federation was formed, every Malaysian makes an average of 538 digital payments per year. More than one per day. All of it running on infrastructure designed, built, and operated by Malaysians. This is the story of how that happened, and what happened to the companies built on top of it.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eYear\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eMilestone\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e1959\u003c/td\u003e\u003ctd\u003eBank Negara Malaysia established\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e1963\u003c/td\u003e\u003ctd\u003eMalaysia formed\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eâ 33 years â\u003c/td\u003e\u003ctd\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e1996\u003c/td\u003e\u003ctd\u003eMEPS: first interbank ATM network\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2000\u003c/td\u003e\u003ctd\u003eIBG: electronic account-to-account transfers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2002\u003c/td\u003e\u003ctd\u003eDomestic PIN-based debit cards\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2004\u003c/td\u003e\u003ctd\u003eChip card migration complete (first in the world)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2004\u003c/td\u003e\u003ctd\u003eFPX goes live\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2011\u003c/td\u003e\u003ctd\u003eBNM Financial Sector Blueprint (target: 200 e-payments/capita by 2020)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2015\u003c/td\u003e\u003ctd\u003eJomPAY launches\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2017\u003c/td\u003e\u003ctd\u003eMEPS + MyClear merge â PayNet\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2018\u003c/td\u003e\u003ctd\u003eDuitNow: instant transfers by phone number\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e2025\u003c/td\u003e\u003ctd\u003e538 e-payments per capita (target was 200)\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## Building the foundation (1996 to 2004)\n\nThe first piece of shared infrastructure arrived in 1996. The **Malaysian Electronic Payment System (MEPS)** launched the country's first interbank ATM network, connecting banks that had previously run separate, incompatible systems. A Maybank cardholder could now withdraw cash at a Public Bank terminal. It was a foundational step: shared infrastructure between competing banks required coordination, trust, and a central mandate. It set the pattern for everything that followed.\n\n**Interbank GIRO (IBG)** came in 2000, enabling electronic account-to-account transfers between banks without a branch counter visit. Domestic PIN-based debit cards arrived in 2002. The nationwide chip card rollout began in 2003.\n\nThen 2004 brought two firsts in a single year.\n\n**FPX (Financial Process Exchange)\u0026#x20;**\u0026#x77;ent live, creating a system for real-time internet-based bank payments. For the first time, a customer could pay a merchant online by logging into their bank, authorizing the transfer, and receiving confirmation within seconds. No card number required. FPX connected directly to the customer's bank account, making it fast, low-cost, and accessible to anyone with online banking. It would become the backbone of online payments in Malaysia.\n\nIn the same year, Malaysia completed the migration of every ATM and debit card in the country from magnetic stripe to chip. Every card, every terminal, nationwide. That required replacing millions of cards and thousands of ATM terminals across the country, coordinating across every issuing bank simultaneously. A single bank moving alone would have gained nothing; the entire network had to switch together. Malaysia was the first country in the world to finish this migration. The United Kingdom completed its chip-and-PIN rollout in 2006. The United States did not begin its chip transition in earnest until 2015, more than a decade later.\n\n## The infrastru
1cture matures (2011 to 2018)\n\nIn 2011, Bank Negara Malaysia published its Financial Sector Blueprint, a 10-year roadmap that identified electronic payments as one of nine strategic focus areas for the national financial system. The Blueprint set an ambitious target: 200 e-payments per capita by 2020.\n\n**JomPAY** launched in 2015, giving Malaysians a single system to pay bills across participating banks and billers. Utilities, telecoms, government fees: one reference number, any bank.\n\nThen on 1 August 2017, MEPS merged with MyClear, the country's electronic clearing house, to form **Payments Network Malaysia (PayNet)**. The merger consolidated Malaysia's payment infrastructure under one entity, fully owned by Bank Negara Malaysia and the country's financial institutions. The payment system was no longer spread across multiple operators.\n\n**DuitNow** followed in 2018: instant fund transfers by mobile number or IC number, across all participating banks and e-wallet providers. For the first time, a Malaysian could send money to anyone with a phone number, regardless of which bank either person used, and the transfer would arrive in seconds. The real-time payment network Malaysia had been building toward for two decades was live.\n\n## Where we are now\n\nThe numbers from 2025 tell the story of what Malaysia built.\n\nThe country recorded 18.4 billion electronic payment transactions, a 25% increase from 14.7 billion the year before. The average Malaysian made 538 digital payments, up from 432 in 2024. That is more than one digital payment per person per day.\n\nDuitNow QR transactions alone hit 3 billion, doubling from 1.5 billion in 2024. Nearly 3 million merchant touchpoints now accept DuitNow QR across the country. Point-of-sale card transactions are projected to overtake ATM cash withdrawals for the first time, with POS accounting for 50.2% of total card transaction value.\n\nThe infrastructure is connecting internationally too. Cross-border QR transactions surged 179% year on year, with 29 live instant payment connections now active across ASEAN. Tourists from Thailand, Singapore, and Indonesia can pay Malaysian merchants by scanning the same DuitNow QR code with their own banking apps. In October 2025, BNM launched RENTAS+, making Malaysia's real-time gross settlement system the first in ASEAN to operate 24/7.\n\nLooking ahead, BNM has mandated that all proprietary QR payment networks be phased out by June 2028, with all QR payments running on shared interoperable infrastructure. One QR code, accepted by every participating app.\n\nBNM's Financial Sector Blueprint had targeted 200 e-payments per capita by 2020. The country passed that mark in 2021, reaching 222. By 2025, it had nearly tripled it.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eYear\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eDigital payments per person (MYR)\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eBNM 2020 target (set 2011)\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e200\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003e2021 (target first exceeded)\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e222\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003e2024\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e432\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003e2025\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e538\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## The companies that grew on top\n\nAs the infrastructure matured, a wave of payment companies launched to connect merchants to these rails. They built the software layer: payment gateways, checkout pages, APIs, and merchant dashboards that let any business accept electronic payments.\n\niPay88, founded in 2000, was among the earliest Malaysian payment gateways, helping businesses accept online payments when e-commerce was still finding its footing in the country. MOLPay launched in 2005 and built a payment gateway presence across Southeast Asia. Billplz started processing payments in 2012. SenangPay entered the market in 2015 with a focus on small businesses and simplified onboarding. Curlec launched in 2018, starting with direct debit for recurring payments.\n\nThen the acquisitions began.\n\nIn 2015, iPay88 was acquired by NTT DATA, a Japanese IT services company. It was renamed NTT DATA eCommerce Solutions in 2025.\n\nIn 2018, MOLPay was absorbed into Razer Inc, a Singapore-headquartered company, as Razer Merchant Services. It later rebranded to Fiuu, operating as a Razer subsidiary.\n\nIn February 2022, Curlec's majority stake was acquired by Razorpay, an Indian fintech company. It now operates as Razorpay Curlec.\n\nAlso in 2022, SenangPay was acquired by DOKU, an Indonesian payments company.\n\nMost of the major Malaysian-founded payment gateways that grew on these rails were acquired by foreign companies between 2015 and 2022. **Billplz remains Malaysian-founded and majority Malaysian-owned**.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCompany\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eFounded\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eAcquired by\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eiPay88\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2000\u003c/td\u003e\u003ctd\u003eNTT Data (Japan), 2015\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eMOLPay\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2005\u003c/td\u003e\u003ctd\u003eRazer (Singapore), 2018. Now Fiuu.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2012\u003c/td\u003e\u003ctd\u003eâ\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSenangPay\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2015\u003c/td\u003e\u003ctd\u003eDOKU (Indonesia), 2022\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCurlec\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e2018\u003c/td\u003e\u003ctd\u003eRazorpay (India), 2022\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## Built here\n\nThe payment system Malaysians use every day was designed, built, and operated by Malaysians. From the first shared ATM network in 1996 to a
1system processing 18.4 billion transactions a year, every layer was made here. MEPS. FPX. PayNet. DuitNow.\n\nSelamat Hari Malaysia.","__component":"shared.rich-text"}]},{"id":574,"documentId":"xp72f9q9dvae059dmlylkqov","title":"538 digital payments per person: Malaysia's 2025 cashless data","slug":"digital-payments-malaysia-statistics-2025","createdAt":"2026-09-08T02:07:16.038Z","updatedAt":"2026-09-08T03:32:14.364Z","publishedAt":"2026-09-08T03:32:14.473Z","publishDate":"2026-09-08T02:07:16.038Z","cover":{"id":158,"documentId":"tfbkzpsaix17pgalp5jyhq5l","name":"260908_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260908_01_01_f4e084d040.webp","hash":"large_260908_01_01_f4e084d040","mime":"image/webp","name":"large_260908_01_01.webp","path":null,"size":42.91,"width":1000,"height":556,"sizeInBytes":42914},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260908_01_01_f4e084d040.webp","hash":"small_260908_01_01_f4e084d040","mime":"image/webp","name":"small_260908_01_01.webp","path":null,"size":19.01,"width":500,"height":278,"sizeInBytes":19006},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260908_01_01_f4e084d040.webp","hash":"medium_260908_01_01_f4e084d040","mime":"image/webp","name":"medium_260908_01_01.webp","path":null,"size":31.92,"width":750,"height":417,"sizeInBytes":31920},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260908_01_01_f4e084d040.webp","hash":"thumbnail_260908_01_01_f4e084d040","mime":"image/webp","name":"thumbnail_260908_01_01.webp","path":null,"size":7.32,"width":245,"height":136,"sizeInBytes":7324}},"hash":"260908_01_01_f4e084d040","ext":".webp","mime":"image/webp","size":85.29,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260908_01_01_f4e084d040.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-08T02:58:38.205Z","updatedAt":"2026-09-08T02:58:38.205Z","publishedAt":"2026-09-08T02:58:38.205Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":301,"metaTitle":"538 digital payments per person: Malaysia's 2025 cashless data","metaDescription":"Malaysia recorded 18.4 billion e-payment transactions in 2025. DuitNow QR doubled to 3 billion. Here are the key digital payment statistics for merchants.","metaKeywords":"digital payments Malaysia statistics 2025","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260908_01_01_f4e084d040.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"@id":"https://main.billplz.com/blog/digital-payments-malaysia-statistics-2025#article","@type":"Article","image":{"url":"","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"538 digital payments per person: how Malaysia went cashless in 2025","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Malaysia recorded 18.4 billion e-payment transactions in 2025. DuitNow QR doubled to 3 billion. Here are the key digital payment statistics for merchants.","dateModified":"","datePublished":"","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/digital-payments-malaysia-statistics-2025"},{"@id":"https://main.billplz.com/blog/digital-payments-malaysia-statistics-2025#faq","@type":"FAQPage","mainEntity":[{"name":"How many digital payments does the average Malaysian make per day?","@type":"Question","acceptedAnswer":{"text":"Based on BNM's Annual Report 2025, the average Malaysian made 538 digital payment transactions in 2025. That works out to roughly 1.5 e-payments per person per day.","@type":"Answer"}},{"name":"How many merchants accept DuitNow QR in Malaysia?","@type":"Question","acceptedAnswer":{"text":"By the end of 2025, there were nearly 3 million DuitNow QR merchant touchpoints across Malaysia, according to BNM's Annual Report 2025. As of 2023, approximately 80% of those merchants were small merchants registering monthly sales below MYR 5,000 (BNM, DuitNow QR: Fostering Inclusive Digital Payments, AR 2023 Box 6).","@type":"Answer"}},{"name":"Is DuitNow QR free for small merchants?","@type":"Question","acceptedAnswer":{"text":"DuitNow QR is not free, but it is designed to be affordable. According to BNM, smaller merchants enjoy a preferential Merchant Discount Rate (MDR) that is maintained at a low level, and DuitNow QR's MDR is competitive with or lower than that of the domestic debit card, MyDebit. There is no POS terminal rental cost for merchants using static QR codes.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"538 digital payments per person: Malaysia's 2025 cashless data","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Malaysia recorded 18.4 billion e-payment transactions in 2025. DuitNow QR doubled to 3 billion. Here are the key digital payment statistics for merchants.","dateModified":"2026-09-08T03:32:12.993Z","datePublished":"2026-09-08T02:07:16.038Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/digital-payments-malaysia-statistics-2025","@type":"WebPage"}}},"blocks":[{"id":548,"body":"Every Malaysian made an average of 538 digital payment transactions in 2025, up from 432 the year before. That is more than one digital payment per person per day. According to Bank Negara Malaysia's (BNM) [Annual Report 2025](https://www.bnm.gov.my/documents/20124/21185005/ar2025_en_book.pdf), the country's total e-payment volume hit 18.4 billion transactions, a 25% jump from 14.7 billion in 2024. The shift is no longer emerging. Digital payments are now the default way Malaysians pay.\n\nThis article breaks down the key digital payments Malaysia statistics from 2025, covering DuitNow QR, mobile banking, contactless payments, cross-border QR, and e-money. If you accept payments from Malaysian customers, these numbers set the context for what they already expect at checkout.\n\n## The numbers at a glance\n\nThe headline figures from BNM's Annual Report 2025:\n\n* **18.4 billion** total e-payment transactions, up 25% from 14.7 billion in 2024\n* **538** e-payments per capita, up from 432\n* **MYR 831 billion** in retail e-payment value, up 19% year on year\n* **17% compound annual growth rate** (CAGR) from 2022 to 2025, exceeding BNM's Financial Sector Blueprint target of 15%\n* **31.4 million** cheque transactions, down 21% year on year\n\nThe per capita figure is worth pausing on. In 2019, Malaysians averaged 150 e-payments per person per year ([BNM, DuitNow QR: Fostering Inclusive Digital Payments, AR 2023 Box 6](https://www.bnm.gov.my/documents/20124/12142010/ar2023_en_box6.pdf)). Six years later, that number is 538. The country did not just adopt digital payments; it made them routine.\n\n## DuitNow QR doubled in a year\n\nDuitNow QR transactions hit 3 billion in 2025, doubling from 1.5 billion in 2024. By year end, there were nearly 3 million DuitNow QR merchant touchpoints across the country.\n\nThe growth is broad, not concentrated. As of 2023 (the latest year for this breakdown), approximately 80% of DuitNow QR merchants were small merchants registering monthly sales below MYR 5,000 ([BNM, DuitNow QR: Fostering Inclusive Digital Payments, AR 2023 Box 6](https://www.bnm.gov.my/documents/20124/12142010/ar2023_en_box6.pdf)). The QR code acceptance network has expanded 6.3 times since 2019, when there were just 0.3 million registered codes ([BNM, DuitNow QR: Fostering Inclusive Digital Payments, AR 2023 Box 6](https://www.bnm.gov.my/documents/20124/12142010/ar2023_en_box6.pdf)).\n\nOne reason for the rapid adoption: cost. DuitNow QR removes the need for point-of-sale (POS) terminal rental, and its Merchant Discount Rate (MDR) is competitive with or lower than that of MyDebit, the domestic debit card network. For small merchants, BNM notes that a preferential MDR is maintained at a low level, keeping the barrier to entry minimal.\n\nDuitNow QR is an interoperable payment rail. A single QR code accepts payments from customers using different e-wallet and banking apps. That interoperability, operated by [PayNet](https://paynet.my/), is what makes the network effect possible. For a closer look at how QR interoperability works in Malaysia, see our [guide to DuitNow QR interoperability](https://main.billplz.com/blog/qr-interoperability-malaysia-duitnow). Billplz supports [DuitNow QR](https://main.billplz.com/blog/products/duitnow-qr-for-online-businesses) as part of its [payment methods](https://main.billplz.com/payment-methods), alongside FPX, Wallet, Card, and Instalments.\n\n## Mobile banking is now the main channel\n\nMobile banking accounted for 64% of all online banking activity in 2025. The number of active mobile banking users reached 25 million, an 8.7% increase year on year.\n\nThis is a structural shift, not a temporary spike. When nearly two thirds of banking interactions happen on a phone, the phone is the primary banking device. For organizations collecting payments, this means the payment experience on mobile is the payment experience, full stop.\n\nContactless card payments also grew, reaching 2 billion transactions in 2025, a 20.3% increase. Debit card transactions grew 20.5%, outpacing credit card growth of 10.9%. The pattern is consistent: everyday, smaller-value transactions are moving digital fastest.\n\n## Cross-border QR is taking off\n\nCross-border QR transactions surged 179% year on year. In the first half of 2025 alone, there were 11.8 million cross-border QR transactions worth MYR 967 million.\n\nThe infrastru
1cture behind this is expanding. There are now 29 live instant payment connections across ASEAN. DuitNow is linked with Thailand's PromptPay and Indonesia's QRIS, meaning tourists from those countries can pay Malaysian merchants using their home banking and e-wallet apps, scanning the same DuitNow QR code.\n\nFor merchants in tourism, hospitality, and retail, this removes a real friction point. International visitors can pay without exchanging cash, without needing a local payment app, and without the fees associated with international card transactions.\n\nCross-border person-to-person transfers also grew 121% year on year, and e-remittance surged 70.1% to MYR 31.6 billion, reinforcing the broader trend of cross-border money movement going digital.\n\n## E-money is growing up\n\nThe average e-money transaction value rose to MYR 43.00 in 2025, up from MYR 33.00 the year before. That 30% increase in average transaction size signals a change in how consumers use e-wallets.\n\nE-wallets started as a tool for small, everyday purchases. The rising transaction value suggests consumers now trust them for higher-value spending. For merchants, this means e-wallet acceptance is no longer just about capturing micro-transactions; it is relevant across a wider range of price points.\n\n## What this means for merchants\n\nThe data points to four practical takeaways.\n\n**Digital payments are the default.** With 538 e-payments per capita, the question is no longer whether customers want to pay digitally. Not offering e-payment options is a friction point that costs transactions.\n\n**DuitNow QR levels the playing field.** Small merchants can access the full pool of digital payment users without POS terminal costs. The interoperable QR code means one integration point covers multiple banks and e-wallets.\n\n**Cross-border QR expands the customer base.** International tourists from Thailand and Indonesia can already pay at DuitNow QR-enabled merchants. As more ASEAN connections go live, the pool of foreign customers who can pay by QR grows.\n\n**The growth rate is sustained.** A 17% CAGR from 2022 to 2025, exceeding BNM's own target, is not a one-year anomaly. The infrastructure investments, from DuitNow QR to cross-border linkages, are compounding.\n\nBillplz is a certified PayNet system integrator, processing payments since 2012 for 60,000+ Malaysian organizations. To see which payment methods are available, visit the [payment methods page](https://main.billplz.com/payment-methods).\n\n---\n\n## FAQ\n\n### How many digital payments does the average Malaysian make per day?\n\nBased on BNM's Annual Report 2025, the average Malaysian made 538 digital payment transactions in 2025. That works out to roughly 1.5 e-payments per person per day.\n\n### How many merchants accept DuitNow QR in Malaysia?\n\nBy the end of 2025, there were nearly 3 million DuitNow QR merchant touchpoints across Malaysia, according to BNM's Annual Report 2025. As of 2023, approximately 80% of those merchants were small merchants registering monthly sales below MYR 5,000 ([BNM, DuitNow QR: Fostering Inclusive Digital Payments, AR 2023 Box 6](https://www.bnm.gov.my/documents/20124/12142010/ar2023_en_box6.pdf)).\n\n### Is DuitNow QR free for small merchants?\n\nDuitNow QR is not free, but it is designed to be affordable. According to BNM, smaller merchants enjoy a preferential Merchant Discount Rate (MDR) that is maintained at a low level, and DuitNow QR's MDR is competitive with or lower than that of the domestic debit card, MyDebit. There is no POS terminal rental cost for merchants using static QR codes.","__component":"shared.rich-text"}]},{"id":569,"documentId":"kl4x2kdaebgx5ngxzfunnwxx","title":"Malaysia is phasing out proprietary QR codes: what merchants need to know","slug":"qr-interoperability-malaysia-duitnow","createdAt":"2026-09-01T05:56:52.853Z","updatedAt":"2026-09-01T06:39:52.364Z","publishedAt":"2026-09-01T06:39:52.464Z","publishDate":"2026-09-01T06:25:00.000Z","cover":{"id":155,"documentId":"iscyow1d8hgy5h0okl8z7u42","name":"260901_01_01.webp","alternativeText":"image-banner","caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260901_01_01_bc3d0257e1.webp","hash":"large_260901_01_01_bc3d0257e1","mime":"image/webp","name":"large_260901_01_01.webp","path":null,"size":23.8,"width":1000,"height":556,"sizeInBytes":23800},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260901_01_01_bc3d0257e1.webp","hash":"small_260901_01_01_bc3d0257e1","mime":"image/webp","name":"small_260901_01_01.webp","path":null,"size":8.28,"width":500,"height":278,"sizeInBytes":8280},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260901_01_01_bc3d0257e1.webp","hash":"medium_260901_01_01_bc3d0257e1","mime":"image/webp","name":"medium_260901_01_01.webp","path":null,"size":15.28,"width":750,"height":417,"sizeInBytes":15278},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260901_01_01_bc3d0257e1.webp","hash":"thumbnail_260901_01_01_bc3d0257e1","mime":"image/webp","name":"thumbnail_260901_01_01.webp","path":null,"size":2.52,"width":245,"height":136,"sizeInBytes":2524}},"hash":"260901_01_01_bc3d0257e1","ext":".webp","mime":"image/webp","size":92.48,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260901_01_01_bc3d0257e1.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-01T06:24:30.333Z","updatedAt":"2026-09-01T06:25:43.948Z","publishedAt":"2026-09-01T06:24:30.333Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":296,"metaTitle":"Malaysia is phasing out proprietary QR codes: what merchants need to know","metaDescription":"BNM is phasing out proprietary QR networks by June 2028. All QR payments will run on DuitNow QR. Here is what Malaysian merchants need to know.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260901_01_01_bc3d0257e1.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"url":"https://main.billplz.com/blog/qr-interoperability-malaysia-duitnow","@type":"Article","author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Malaysia is phasing out proprietary QR codes: what merchants need to know","keywords":["DuitNow QR","interoperable QR Malaysia","proprietary QR","BNM QR payment","DuitNow QR merchant"],"publisher":{"url":"https://main.billplz.com","logo":{"url":"https://main.billplz.com/images/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"inLanguage":"en-MY","description":"BNM is phasing out proprietary QR networks by June 2028. All QR payments will run on DuitNow QR. Here is what Malaysian merchants need to know.","dateModified":"","datePublished":"","articleSection":"Insights"},{"@type":"FAQPage","mainEntity":[{"name":"Do I need to change anything if I already accept DuitNow QR?","@type":"Question","acceptedAnswer":{"text":"No. DuitNow QR already runs on the interoperable payment infrastructure operated by PayNet. Your customers can pay from any participating bank or e-wallet app, and no migration is needed on your end.","@type":"Answer"}},{"name":"What happens to proprietary QR codes after June 2028?","@type":"Question","acceptedAnswer":{"text":"Proprietary QR payment networks must be discontinued by 30 June 2028 under BNM's Interoperable Fund Transfer Framework. After that date, all QR payments in Malaysia will run through the shared interoperable system (DuitNow QR), operated by PayNet.","@type":"Answer"}},{"name":"Can tourists pay with DuitNow QR?","@type":"Question","acceptedAnswer":{"text":"Yes. Cross-border QR payments are growing rapidly, with tourists from Thailand, Singapore, and Indonesia able to pay Malaysian merchants via DuitNow QR using their own banking apps. BNM reported a 179% year-on-year increase in cross-border QR transactions in 2025.","@type":"Answer"}},{"name":"How do I enable DuitNow QR on my Billplz account?","@type":"Question","acceptedAnswer":{"text":"DuitNow QR appears automatically on the Billplz payment page once it is enabled on your collection. KYB verification happens during onboarding. To add DuitNow QR, apply through the payment method application form, then enable it per collection. For a step-by-step walkthrough, see the Billplz support article on enabling or disabling a payment method at support.billplz.com.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Malaysia is phasing out proprietary QR codes: what merchants need to know","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"BNM is phasing out proprietary QR networks by June 2028. All QR payments will run on DuitNow QR. Here is what Malaysian merchants need to know.","dateModified":"2026-09-01T06:39:51.055Z","datePublished":"2026-09-01T05:56:52.853Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/qr-interoperability-malaysia-duitnow","@type":"WebPage"}}},"blocks":[{"id":543,"body":"On 30 June 2026, Bank Negara Malaysia (BNM) issued the [Interoperable Fund Transfer Framework](https://theedgemalaysia.com/node/808881), a policy document that requires all proprietary QR payment networks in Malaysia to be discontinued by 30 June 2028. After that date, every QR payment in the country will run on a single interoperable system: [DuitNow QR](https://paynet.my), operated by Payments Network Malaysia (PayNet). If you already accept DuitNow QR through Billplz, nothing changes for you. Your customers can already pay from any participating bank or Wallet app, and your setup is on the right rail.\n\nThis article explains what the new framework means, why BNM is making this move, and what merchants in each situation should do next.\n\n## What is changing\n\nUnder the new framework, proprietary QR networks, meaning closed systems where only one specific app can scan and pay through a particular QR code, must be discontinued by 30 June 2028. During the transition period, affected
1institutions are also barred from onboarding new merchants onto proprietary QR networks.\n\nGoing forward, all QR payments must go through the shared payment infrastructure: PayNet's Real-time Retail Payments Platform (RPP). This is the same infrastructure that already powers DuitNow Transfer and DuitNow QR.\n\nIn practical terms, this means:\n\n* Banks offering QR payments must participate in the shared infrastructure and allow their customers to pay merchants served by any participating acquirer.\n* Merchant acquirers must allow their merchants to accept payments from customers of any participating bank or Wallet provider.\n* Consumers will be able to use any participating bank or e-wallet app to pay any participating merchant through the same QR code.\n\nThe result is one unified QR payment network instead of multiple siloed ones.\n\n## Why BNM is making this move\n\nThe reasoning is straightforward. Proprietary QR networks created fragmentation. Merchants had to display multiple QR codes for different apps, and consumers could not always pay with their preferred app at a given merchant. The experience was inconsistent, and smaller merchants were the most affected because they could not afford to support every provider.\n\nBNM's position is that interoperability solves both problems. One QR code covers all participating apps, and every merchant, regardless of size, has access to the full pool of QR-paying consumers. According to BNM, most respondents to its earlier consultation did not object to the prohibition on proprietary QR schemes, recognising that it would prevent market fragmentation and improve the payment experience.\n\nPayNet has also assured full flexibility for providers to design and implement loyalty and marketing programmes within the shared payment network, addressing concerns raised by some stakeholders about the transition.\n\n## What this means for merchants\n\nThe impact depends on your current setup. Here are the three most common scenarios.\n\n### You already accept DuitNow QR\n\nNothing changes. DuitNow QR already runs on the interoperable RPP infrastructure. Your customers can pay from any participating bank or Wallet app, and there is no migration required on your end. This applies whether you accept DuitNow QR through Billplz or through another acquirer.\n\n### You accept a proprietary QR code\n\nYour provider will need to migrate you to the DuitNow QR system before 30 June 2028. The two-year transition period gives providers time to adjust their systems and operating models. If you are unsure whether your current QR setup is proprietary or interoperable, ask your payment provider about their transition plan.\n\n### You do not accept QR payments yet\n\nNow is a practical time to start. With all QR payments converging on DuitNow QR, you only need one QR code to accept payments from every participating bank and Wallet app. There is no longer a question of which QR provider to choose, because every provider will be on the same interoperable network.\n\n## DuitNow QR by the numbers\n\nDuitNow QR adoption has grown quickly since its launch in 2019, and the numbers show why this interoperability mandate is building on strong momentum rather than starting from scratch.\n\n**2025 data (BNM Annual Report 2025):**\n\n* 3 billion DuitNow QR transactions, doubled from 1.5 billion in 2024\n* Nearly 3 million merchant touchpoints registered\n* 179% year-on-year increase in cross-border QR transactions, with 11.8 million transactions worth MYR 967 million in the first half of 2025 alone\n* Cross-border QR payments now allow tourists from Thailand, Singapore, and Indonesia to pay Malaysian merchants using their own banking apps\n* 18.4 billion total e-payment transactions across Malaysia, up 25% from 14.7 billion in 2024\n* 538 e-payments per capita, up from 432 in 2024\n\n**2023 data (BNM Annual Report 2023, Box 6):**\n\n* Approximately 80% of DuitNow QR merchants are small merchants registering monthly sales below MYR 5,000.00\n* DuitNow QR registered codes grew 6.3x from 0.3 million in 2019 to 2.0 million in 2023\n\nThe cross-border growth is particularly relevant. As inbound tourism continues to grow, accepting DuitNow QR means your checkout works for both Malaysian consumers and visitors from participating countries, without any additional setup.\n\n## How Du
1itNow QR works on Billplz\n\nDuitNow QR is a supported [payment method on Billplz](https://main.billplz.com/payment-methods). Billplz is a certified PayNet system integrator, which means the connection to the DuitNow QR rail is direct and maintained.\n\nHere is what to know:\n\n* DuitNow QR shows up automatically on the Billplz payment page once it is enabled on your collection.\n* KYB verification happens during onboarding. To add non-FPX payment methods like DuitNow QR, you then apply through a [payment method application form](https://docs.google.com/forms/d/17j9QyO8m0ds_9X6Zxuldx0sDiEssOKGMcvYgQrQ90I0/viewform). Once approved, enable DuitNow QR on each collection.\n* For developers: no extra API work is needed. Callbacks and webhooks work the same way they do for FPX, Wallet, Card, and Instalments. The payment method is handled on the Billplz payment page.\n* Billplz supports DuitNow QR as one of several payment methods alongside FPX, Wallet, Card, and Instalments, so your customers always have a choice.\n\nTo enable or disable DuitNow QR on your collection, follow the steps in the [Billplz support article on payment methods](https://support.billplz.com/guide/enable-or-disable-a-payment-method).\n\n---\n\n## FAQ\n\n### Do I need to change anything if I already accept DuitNow QR?\n\nNo. DuitNow QR already runs on the interoperable payment infrastru
1cture operated by PayNet. Your customers can pay from any participating bank or Wallet app, and no migration is needed on your end. This applies whether you accept DuitNow QR through Billplz or through another acquirer.\n\n### What happens to proprietary QR codes after June 2028?\n\nProprietary QR payment networks must be discontinued by 30 June 2028 under BNM's Interoperable Fund Transfer Framework. After that date, all QR payments in Malaysia will run through the shared interoperable system, which is the DuitNow QR network operated by PayNet. During the transition period, affected providers are also barred from onboarding new merchants onto proprietary QR networks.\n\n### Can tourists pay with DuitNow QR?\n\nYes. Cross-border QR payments are growing rapidly. Tourists from Thailand, Singapore, and Indonesia can pay Malaysian merchants via DuitNow QR using their own banking apps. BNM reported a 179% year-on-year increase in cross-border QR transactions in 2025, with 11.8 million transactions worth MYR 967 million in the first half of the year alone.\n\n### How do I enable DuitNow QR on my Billplz account?\n\nDuitNow QR appears automatically on the Billplz payment page once it is enabled on your collection. KYB verification happens during onboarding. To add DuitNow QR, apply through the [payment method application form](https://docs.google.com/forms/d/17j9QyO8m0ds_9X6Zxuldx0sDiEssOKGMcvYgQrQ90I0/viewform), then enable it per collection. For a step-by-step walkthrough, see the Billplz support article on [enabling or disabling a payment method](https://support.billplz.com/guide/enable-or-disable-a-payment-method).\n\n---\n\n## Looking ahead\n\nThe shift to a single interoperable QR system is a simplification of the Malaysian payment landscape, not a disruption. For merchants already on DuitNow QR, the change reinforces a decision you have already made. For those still on proprietary systems, the two-year window gives you time to plan the transition. And for organizations not yet accepting QR payments, the path forward is now clearer than ever: one QR code, one network, every participating app.\n\nBillplz has been processing payments since 2012, serving 60,000+ Malaysian organizations across FPX, Wallet, Card, and Instalments. If you have questions about DuitNow QR on Billplz, [visit the payment methods page](https://main.billplz.com/payment-methods) or check [pricing](https://main.billplz.com/pricing) for your plan.","__component":"shared.rich-text"}]},{"id":568,"documentId":"d58fugngdby4tuewahms6unr","title":"Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities","slug":"education-fee-collection-malaysia-fpx-duitnow","createdAt":"2026-08-25T06:22:13.087Z","updatedAt":"2026-09-01T06:29:33.338Z","publishedAt":"2026-09-01T06:29:33.450Z","publishDate":"2026-08-25T06:22:13.087Z","cover":{"id":156,"documentId":"gaj78m637idnxcyhr82fgmw2","name":"260824_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260824_01_01_4d6b66be13.webp","hash":"large_260824_01_01_4d6b66be13","mime":"image/webp","name":"large_260824_01_01.webp","path":null,"size":41.12,"width":1000,"height":556,"sizeInBytes":41120},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260824_01_01_4d6b66be13.webp","hash":"small_260824_01_01_4d6b66be13","mime":"image/webp","name":"small_260824_01_01.webp","path":null,"size":11.22,"width":500,"height":278,"sizeInBytes":11224},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260824_01_01_4d6b66be13.webp","hash":"medium_260824_01_01_4d6b66be13","mime":"image/webp","name":"medium_260824_01_01.webp","path":null,"size":24.49,"width":750,"height":417,"sizeInBytes":24488},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260824_01_01_4d6b66be13.webp","hash":"thumbnail_260824_01_01_4d6b66be13","mime":"image/webp","name":"thumbnail_260824_01_01.webp","path":null,"size":3.68,"width":245,"height":136,"sizeInBytes":3682}},"hash":"260824_01_01_4d6b66be13","ext":".webp","mime":"image/webp","size":122.8,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260824_01_01_4d6b66be13.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-01T06:29:14.850Z","updatedAt":"2026-09-01T06:29:14.850Z","publishedAt":"2026-09-01T06:29:14.850Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":295,"metaTitle":"Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities","metaDescription":"How Malaysian schools, colleges, and universities handle education fee collection online with FPX and DuitNow, from fee schedules to refunds and payouts.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260824_01_01_4d6b66be13.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"@id":"https://main.billplz.com/blog/education-fee-collection-malaysia-fpx-duitnow#article","@type":"Article","author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"How Malaysian schools, colleges, and universities handle education fee collection online with FPX and DuitNow, from fee schedules to refunds and payouts.","dateModified":"SET-AT-PUBLISH","datePublished":"SET-AT-PUBLISH","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/education-fee-collection-malaysia-fpx-duitnow"},{"@id":"https://main.billplz.com/blog/education-fee-collection-malaysia-fpx-duitnow#faq","@type":"FAQPage","mainEntity":[{"name":"Can schools and universities in Malaysia collect fees online?","@type":"Question","acceptedAnswer":{"text":"Yes. Schools, colleges, and universities collect fees online through FPX and DuitNow via a payment provider, which hosts the payment page and settles collections to the institution. Parents and students pay from their own bank accounts, and each payment is recorded for reconciliation.","@type":"Answer"}},{"name":"What payment methods can an institution accept?","@type":"Question","acceptedAnswer":{"text":"Through one provider, an institution can accept FPX, Wallet, Card, and Instalments on a single payment page. FPX does most of the work for fee collection, because parents and students pay directly from their bank accounts.","@type":"Answer"}},{"name":"How do parents or students pay a large semester fee?","@type":"Question","acceptedAnswer":{"text":"Through FPX from a personal bank account. Personal account transactions run from MYR 1.00 to MYR 30,000.00 per transaction, as documented at paynet.my, a range that covers most individual fees, including a large semester fee.","@type":"Answer"}},{"name":"Can an institution refund fees or pay out scholarships online?","@type":"Question","acceptedAnswer":{"text":"Yes, using a disbursement product. Billplz Payment Order handles money going out, so it fits fee refunds and scholarship or stipend payouts to students, kept separate from the Collection product that brings fees in.","@type":"Answer"}},{"name":"How much does it cost an institution to collect fees online?","@type":"Question","acceptedAnswer":{"text":"Fees vary by payment method and plan, and they change over time, so a live pricing page beats any static figure. Billplz publishes current rates for every plan and method at main.billplz.com/pricing.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"How Malaysian schools, colleges, and universities handle education fee collection online with FPX and DuitNow, from fee schedules to refunds and payouts.","dateModified":"2026-09-01T06:29:31.670Z","datePublished":"2026-08-25T06:22:13.087Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/education-fee-collection-malaysia-fpx-duitnow","@type":"WebPage"}}},"blocks":[{"id":542,"body":"Malaysian education institutions can collect fees online through FPX and DuitNow, the same national rails families already use for everyday banking. A payment provider connects the institution to those rails, hosts the payment page, and settles collections to the institution. That means education fee collection in Malaysia does not need a queue at the bursary counter: a parent or student can settle a term fee from their own bank account, and the record is created the moment they pay. This article walks a finance office through how the rails work, how collection maps to different fee sizes, how the collection and disbursement products fit, and how to weigh a payment partner.\n\n## The pain of collecting fees manually\n\nManual fee collection is slow work for a finance office. Staff reconcile who paid what by hand, matching bank-in slips against a list of students at the end of the term. Overdue fees mean chasing families one by one. Cash and cheques at a counter add banking runs and clearing time on top.\n\nOnline collection changes the shape of that work. A parent or student settles a fee from their own bank account at any hour, and the record is created at the moment of payment. Reconciliation then starts from complete data instead of keyed-in receipts, and collection stops being tied to counter hours.\n\nEvery institution's process is different. A primary school collecting term fees, a college collecting registration and exam fees, and a university handling semester fees all start from different systems and volumes. The rails underneath, though, are the same for all of them.\n\n## The rails: FPX and DuitNow for fee collection\n\nFPX lets a payer pay directly from their bank account. More than 20 Malaysian banks participate. The parent or student selects their bank on the payment page, logs in to their own online banking, and approves the payment there. No card is needed, and the institution never sees the payer's banking credentials. PayNet, which operates Malaysia's national payment infrastru
1cture, documents the system at [paynet.my](https://www.paynet.my).\n\nDuitNow supports instant bank-to-bank transfers, and DuitNow QR lets a payer scan a code and pay from their banking app or Wallet. PayNet is progressively moving online bank payments toward DuitNow Online Banking, but FPX remains the standard at checkout today.\n\nA payment provider connects the institution to these rails, and usually to more than the rails. Through one provider, an institution can accept FPX, Wallet, Card, and Instalments on a single payment page, so the family pays with whatever they already use. You can read more about how FPX works in [our FPX explainer](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide).\n\n### How FPX models map to fee sizes\n\nFPX runs two models, documented at [paynet.my](https://www.paynet.my). They map cleanly to how education fees actually get paid:\n\n* **B2C** covers an individual paying from a personal bank account. Personal account transactions run from MYR 1.00 to MYR 30,000.00 per transaction. This range covers most individual fees, including a large semester fee, so a parent or student settling tuition fits here.\n* **B2B** cover a company or organization paying from a corporate account, up to MYR 1,000,000.00 per transaction. These fit cases where the institution collects from another body rather than an individual, for example a sponsored-student invoice or a bulk institutional flow.\n\nFor what any of this costs an institution to run, see the pricing page rather than a static figure: [main.billplz.com/pricing](https://main.billplz.com/pricing).\n\n## Collecting fees with Billplz Collection\n\nFor a fixed fee tied to a specific payer, Billplz Collection is the fit. A Collection bill is a pre-defined amount for a specific payer: a term fee, a registration fee, or an exam fee for a named student or parent. The finance office sets the amount, and the payer settles that exact bill.\n\nCollection also helps with the chasing. It supports reminders by email and SMS, as documented in the EZQurban case study on the [Billplz customers page](https://main.billplz.com/customers). For a bursary tracking overdue term fees, automated reminders take some of the manual follow-up off the desk.\n\nYou can see how Collection fits fee schedules at [main.billplz.com/collection](https://main.billplz.com/collection).\n\n### When to use an open-amount payment form instead\n\nNot every charge is a fixed fee for a named payer. When the payer chooses the amount, for example an open contribution to a school fund or a variable charge, that is a different product: the Catalog Payment Link, the payment-link product for open amounts. A Collection bill is a pre-defined amount for a specific payer, so keep the two separate. If the amount is fixed and tied to a student, reach for Collection; if the payer decides how much to pay, reach for the payment form.\n\n## Refunds and disbursements with Billplz Payment Order\n\nMoney going out is a separate job from money coming in, so it uses a separate product. Billplz Payment Order is the disbursement product. It fits fee refunds, and scholarship or stipend payouts to students. Where Collection brings fees in, Payment Order sends money back out, and keeping the two distinct keeps the finance office's records clean. You can read what Payment Order covers at [main.billplz.com/payment-order](https://main.billplz.com/payment-order).\n\n## Choosing a payment partner institutions can trust\n\nAn institution handing fee collection to a provider is trusting that provider with families' money and its own reconciliation. Statutory and institutional buyers tend to ask the same question: is this provider credible enough for institutional and public-sector use? A few documented facts help answer it.\n\nPDRM (Polis Diraja Malaysia) is documented as a government client on the [Billplz landing page](https://main.billplz.com). A provider trusted to collect for a federal agency has already met the kind of scrutiny institutional procurement applies. Billplz is a certified PayNet system integrator, and has processed payments since 2012, with 99.9% historical uptime. More than 60,000 Malaysian organizations use Billplz, a base that includes schools.\n\nTo be clear about what that proof is: a documented public-sector client is a track record, not a government or education endorsement, and no provider should present it as one.\n\n---\n\n## FAQ\n\n### Can schools and universities in Malaysia collect fees online?\n\nYes. Schools, colleges, and universities collect fees online through FPX and DuitNow via a payment provider, which hosts the payment page and settles collections to the institution. Parents and students pay from their own bank accounts, and each payment is recorded for reconciliation.\n\n### What payment methods can an institution accept?\n\nThrough one provider, an institution can accept FPX, Wallet, Card, and Instalments on a single payment page. FPX does most of the work for fee collection, because parents and students pay directly from their bank accounts.\n\n### How do parents or students pay a large semester fee?\n\nThrough FPX from a personal bank account. Personal account transactions run from MYR 1.00 to MYR 30,000.00 per transaction, as documented at [paynet.my](https://www.paynet.my), a range that covers most individual fees, including a large semester fee.\n\n### Can an institution refund fees or pay out scholarships online?\n\nYes, using a disbursement product. Billplz Payment Order handles money going out, so it fits fee refunds and scholarship or stipend payouts to students, kept separate from the Collection product that brings fees in.\n\n### How much does it cost an institution to collect fees online?\n\nFees vary by payment method and plan, and they change over time, so a live pricing page beats any static figure. Billplz publishes current rates for every plan and method at [main.billplz.com/pricing](https://main.billplz.com/pricing).\n\n---\n\n## Where to start\n\nEvery institution's fee structure is different: term fees, registration and exam fees, semester schedules, refunds, and payouts all sit in the mix, and payment preferences keep evolving as more families bank on their phones. The mechanics in this article stay the same wherever you start. Pick the rails your families already trust, use Collection for fixed fees and Payment Order for money going back out, and choose a partner with a documented track record. For what it costs, the live rates are at [main.billplz.com/pricing](https://main.billplz.com/pricing).","__component":"shared.rich-text"}]},{"id":571,"documentId":"ndbado2ticzh9m0hvn8wj0ty","title":"Zakat and religious collection in Malaysia: how institutions accept payments online","slug":"zakat-religious-collection-malaysia","createdAt":"2026-08-11T07:04:46.265Z","updatedAt":"2026-09-08T02:58:54.752Z","publishedAt":"2026-09-08T02:58:54.915Z","publishDate":"2026-08-14T09:00:00.000Z","cover":{"id":157,"documentId":"wmwoibpp8uv6isueinwn6ci0","name":"260814_01_01.webp","alternativeText":null,"caption":null,"width":1801,"height":1001,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_260814_01_01_7f3a091b3a.webp","hash":"large_260814_01_01_7f3a091b3a","mime":"image/webp","name":"large_260814_01_01.webp","path":null,"size":103.94,"width":1000,"height":556,"sizeInBytes":103938},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260814_01_01_7f3a091b3a.webp","hash":"small_260814_01_01_7f3a091b3a","mime":"image/webp","name":"small_260814_01_01.webp","path":null,"size":28.36,"width":500,"height":278,"sizeInBytes":28360},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260814_01_01_7f3a091b3a.webp","hash":"medium_260814_01_01_7f3a091b3a","mime":"image/webp","name":"medium_260814_01_01.webp","path":null,"size":63.21,"width":750,"height":417,"sizeInBytes":63212},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260814_01_01_7f3a091b3a.webp","hash":"thumbnail_260814_01_01_7f3a091b3a","mime":"image/webp","name":"thumbnail_260814_01_01.webp","path":null,"size":6.58,"width":245,"height":136,"sizeInBytes":6576}},"hash":"260814_01_01_7f3a091b3a","ext":".webp","mime":"image/webp","size":322.55,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260814_01_01_7f3a091b3a.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-09-08T02:57:14.344Z","updatedAt":"2026-09-08T02:57:14.344Z","publishedAt":"2026-09-08T02:57:14.345Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":298,"metaTitle":"Zakat and religious collection in Malaysia: how institutions accept payments online","metaDescription":"How Malaysian zakat bodies, mosques, and Islamic NGOs accept payments online, and how Billplz supports trusted zakat online payment collection in Malaysia.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260814_01_01_f219670d0e.webp","@type":"ImageObject","width":1801,"height":1001},"@graph":[{"@id":"https://main.billplz.com/blog/zakat-religious-collection-malaysia#article","@type":"Article","author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Zakat and religious collection in Malaysia: how institutions accept payments online","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"How Malaysian zakat bodies, mosques, and Islamic NGOs accept payments online, and how Billplz supports trusted zakat online payment collection in Malaysia.","dateModified":"SET-AT-PUBLISH","datePublished":"SET-AT-PUBLISH","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/zakat-religious-collection-malaysia"},{"@id":"https://main.billplz.com/blog/zakat-religious-collection-malaysia#faq","@type":"FAQPage","mainEntity":[{"name":"Is Billplz an official zakat agent?","@type":"Question","acceptedAnswer":{"text":"Yes. Billplz is the official agent (ejen rasmi) appointed by Lembaga Zakat Selangor (MAIS) and by Pusat Pungutan Zakat MAIWP. The appointment letters (surat pelantikan) are displayed publicly on zakat.billplz.com.","@type":"Answer"}},{"name":"Which zakat bodies has Billplz been appointed by?","@type":"Question","acceptedAnswer":{"text":"Billplz is appointed as official agent by Lembaga Zakat Selangor (MAIS) and by Pusat Pungutan Zakat MAIWP, which covers Wilayah Persekutuan Kuala Lumpur. The appointment letters for both are shown on zakat.billplz.com.","@type":"Answer"}},{"name":"Which types of zakat can be paid online?","@type":"Question","acceptedAnswer":{"text":"The channel documented on zakat.billplz.com covers obligatory zakat types including pendapatan, perniagaan, fitrah, simpanan, saham, KWSP, takaful, emas, perak, tanaman, ternakan, kripto, and qadha, and more. A payer selects the type when they pay.","@type":"Answer"}},{"name":"Can a mosque or Islamic NGO use Billplz to collect its own donations?","@type":"Question","acceptedAnswer":{"text":"Yes. A mosque or surau committee, an Islamic NGO, or a qurban and aqiqah operator can set up its own collection. Use Billplz Collection for a defined amount billed to a specific payer, or a Catalog Payment Form when the payer chooses the amount, such as an open donation. You can see the setup at main.billplz.com/collection.","@type":"Answer"}},{"name":"Will payers receive an official statement for tax relief?","@type":"Question","acceptedAnswer":{"text":"Individuals who pay zakat through the official channel receive an official statement, the Penyata Zakat, issued by the zakat body itself, Lembaga Zakat Selangor or Pusat Pungutan Zakat MAIWP. That statement supports tax relief. It is issued by the zakat institution, not by Billplz.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Zakat and religious collection in Malaysia: how institutions accept payments online","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"How Malaysian zakat bodies, mosques, and Islamic NGOs accept payments online, and how Billplz supports trusted zakat online payment collection in Malaysia.","dateModified":"2026-09-01T06:25:12.462Z","datePublished":"2026-08-11T07:04:46.265Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/zakat-religious-collection-malaysia","@type":"WebPage"}}},"blocks":[{"id":545,"body":"Religious institutions in Malaysia can collect zakat, donations, and fees online through local payment methods such as FPX, Wallet, and Card. Zakat bodies, mosque and surau committees, Islamic NGOs, and qurban and aqiqah operators all set up their own online collection this way. Trust matters more here than in most collection, because payers are fulfilling a religious obligation. This is where zakat online payment collection in Malaysia has to be handled with care. Billplz supports this work as the appointed official agent (ejen rasmi) for two major zakat bodies, and this article covers how an institution sets up its own collection and why that trust is central.\n\n## Collecting religious payments online in Malaysia\n\nReligious institutions in Malaysia accept payments online by connecting to local payment methods through a payment provider. The provider hosts a payment page, accepts FPX, Wallet, and Card, and channels the collection to the institution. Zakat bodies, mosque and surau committees, Islamic NGOs, and qurban and aqiqah operators collect zakat, donations, and fees this way.\n\n## Why trust is different for religious collection\n\nReligious collection carries a higher trust bar than ordinary payments. The reason is simple: the payer is fulfilling a religious obligation, not buying a product. That changes what matters at the moment of payment.\n\nThree things weigh heavily here. The payer needs to know the money reaches the right fund, not an unfamiliar third party. Statements matter, because zakat payments support tax relief and the payer will want a record. And the whole flow has to feel appropriate to the act of worship, without pressure or promotional noise.\n\nThe face-to-face test applies with extra weight. Ask whether you would say a line to a person paying zakat, sitting across from you, without it sounding out of place. If it would, revise. This is why proof of trust, not marketing, anchors the sections that follow.\n\n## Billplz is an appointed official zakat agent\n\nBillplz is the official agent (ejen rasmi) appointed by Lembaga Zakat Selangor (MAIS) and by Pusat Pungutan Zakat MAIWP, which covers Wilayah Persekutuan Kuala Lumpur. The appointment letters (surat pelantikan) are displayed publicly on [zakat.billplz.com](https://zakat.billplz.com), so the appointment is not a claim you have to take on faith. It is documented on the page where individuals pay.\n\nThis appointment is the proof that anchors everything else on this page. An institution weighing how to collect online can see what a trusted, compliant religious collection actually looks like in practice, backed by real appointments rather than a general promise.\n\n### What \"official agent\" means for payers and institutions\n\nBeing an official agent means collections are channelled directly to the state zakat funds. Those funds are managed according to the zakat institutions' syariah requirements. The syariah management belongs to the zakat institutions themselves, not to Billplz. Billplz does not hold or claim any Shariah certification of its own. Its role is the payment channel, appointed and documented, that moves the payment to the fund the payer intends.\n\n## Zakat types accepted\n\nIndividuals paying through the official channel can pay a wide range of obligatory zakat types, documented on [zakat.billplz.com](https://zakat.billplz.com):\n\n* Zakat pendapatan\n* Zakat perniagaan\n* Zakat fitrah\n* Zakat simpanan\n* Zakat saham\n* Zakat KWSP\n* Zakat takaful\n* Zakat emas\n* Zakat perak\n* Zakat tanaman\n* Zakat ternakan\n* Zakat kripto\n* Zakat qadha\n\nThe channel covers these and more. The breadth matters for an institution asse
1ssing whether online collection can carry the full range of obligations its payers bring.\n\n## How institutions set up their own collection\n\nThis is the practical core for an institution running its own collection. Billplz offers two products for this, and they suit different needs. Keeping them distinct avoids charging the wrong way.\n\n### Billplz Collection for defined amounts\n\nUse Billplz Collection when the amount is set in advance and billed to a specific payer. A fixed contribution or a known fee fits here. Staff create the bill from a dashboard, one at a time or in bulk via an Excel upload, and the payer settles it on a Billplz-hosted payment page with a receipt sent automatically. This is a bill for a defined amount, not an open link.\n\n### Catalog Payment Form for open donations\n\nUse the Catalog Payment Form when the payer chooses the amount. Open sadaqah or a general donation fits here, because the payer decides how much to give. The Catalog Payment Form is the product behind a payment link: one link, any payer, an amount they set themselves.\n\n### Payment methods and payer experience\n\nOn both products, the payer can choose FPX, Wallet, or Card. FPX lets them pay from their own bank account. Wallet and Card cover payers who prefer those. The setup is meant to be matter-of-fact: connect, create the collection, and share the page or bill. You can see how a collection is set up at [main.billplz.com/collection](https://main.billplz.com/collection). Fees differ by method and plan and change over time, so current rates live on [main.billplz.com/pricing](https://main.billplz.com/pricing) rather than in this article.\n\n## Statements and tax relief\n\nIndividuals who pay zakat receive an official statement, the Penyata Zakat, issued by the zakat body itself: Lembaga Zakat Selangor or Pusat Pungutan Zakat MAIWP. That statement supports tax relief. The statement comes from the zakat institution, not from Billplz. Billplz is the channel that carries the payment; the record that supports relief is issued by the body the payer is paying. This matters for institutions to state accurately to their own payers.\n\n---\n\n## FAQ\n\n### Is Billplz an official zakat agent?\n\nYes. Billplz is the official agent (ejen rasmi) appointed by Lembaga Zakat Selangor (MAIS) and by Pusat Pungutan Zakat MAIWP. The appointment letters (surat pelantikan) are displayed publicly on [zakat.billplz.com](https://zakat.billplz.com).\n\n### Which zakat bodies has Billplz been appointed by?\n\nBillplz is appointed as official agent by Lembaga Zakat Selangor (MAIS) and by Pusat Pungutan Zakat MAIWP, which covers Wilayah Persekutuan Kuala Lumpur. The appointment letters for both are shown on zakat.billplz.com.\n\n### Which types of zakat can be paid online?\n\nThe channel documented on zakat.billplz.com covers obligatory zakat types including pendapatan, perniagaan, fitrah, simpanan, saham, KWSP, takaful, emas, perak, tanaman, ternakan, kripto, and qadha, and more. A payer selects the type when they pay.\n\n### Can a mosque or Islamic NGO use Billplz to collect its own donations?\n\nYes. A mosque or surau committee, an Islamic NGO, or a qurban and aqiqah operator can set up its own collection. Use Billplz Collection for a defined amount billed to a specific payer, or a Catalog Payment Form when the payer chooses the amount, such as an open donation. You can see the setup at [main.billplz.com/collection](https://main.billplz.com/collection).\n\n### Will payers receive an official statement for tax relief?\n\nIndividuals who pay zakat through the official channel receive an official statement, the Penyata Zakat, issued by the zakat body itself, Lembaga Zakat Selangor or Pusat Pungutan Zakat MAIWP. That statement supports tax relief. It is issued by the zakat institution, not by Billplz.\n\n---\n\n## Where to start\n\nEvery institution's needs are different. A zakat body, a surau committee, and an Islamic NGO each start from different collections, volumes, and payer habits, and every one deserves a setup that fits its own context. If you are an institution weighing how to collect online, you can see how a collection is set up at [main.billplz.com/collection](https://main.billplz.com/collection). If you are an individual looking to bayar zakat online, you can pay through the official channel at [zakat.billplz.com](https://zakat.billplz.com).","__component":"shared.rich-text"}]},{"id":555,"documentId":"mg46wv90jli2x0e1rjgekhvn","title":"How Malaysian government agencies collect payments online with FPX and DuitNow","
1slug":"government-payment-collection-malaysia-fpx-duitnow","createdAt":"2026-07-16T03:20:00.551Z","updatedAt":"2026-08-11T06:46:35.962Z","publishedAt":"2026-08-11T06:46:36.081Z","publishDate":"2026-08-11T07:03:00.000Z","cover":{"id":142,"documentId":"fc65tuzr7evt5vu0ebgcn4pv","name":"260716_01_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260716_01_01_622bf144cf.webp","hash":"small_260716_01_01_622bf144cf","mime":"image/webp","name":"small_260716_01_01.webp","path":null,"size":22.54,"width":500,"height":278,"sizeInBytes":22542},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260716_01_01_622bf144cf.webp","hash":"medium_260716_01_01_622bf144cf","mime":"image/webp","name":"medium_260716_01_01.webp","path":null,"size":56.6,"width":750,"height":417,"sizeInBytes":56600},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260716_01_01_622bf144cf.webp","hash":"thumbnail_260716_01_01_622bf144cf","mime":"image/webp","name":"thumbnail_260716_01_01.webp","path":null,"size":4.45,"width":245,"height":136,"sizeInBytes":4454}},"hash":"260716_01_01_622bf144cf","ext":".webp","mime":"image/webp","size":107.96,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_01_01_622bf144cf.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-16T05:11:00.846Z","updatedAt":"2026-07-16T05:11:00.846Z","publishedAt":"2026-07-16T05:11:00.846Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":282,"metaTitle":"How Malaysian government agencies collect payments online with FPX and DuitNow","metaDescription":"How Malaysian government agencies collect payments online with FPX and DuitNow, plus what PDRM's MyBayar Saman and PS 2.1 compliance mean for your agency.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_01_01_622bf144cf.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"How Malaysian government agencies collect payments online with FPX and DuitNow","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"How Malaysian government agencies collect payments online with FPX and DuitNow, plus what PDRM's MyBayar Saman and PS 2.1 compliance mean for your agency.","dateModified":"2026-08-11T06:46:34.670Z","datePublished":"2026-07-16T03:20:00.551Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/government-payment-collection-malaysia-fpx-duitnow","@type":"WebPage"}}},"blocks":[{"id":529,"body":"Malaysian government agencies and statutory bodies collect payments online through FPX and DuitNow, the same national rails citizens already use for everyday banking. The agency connects to those rails through a payment provider. The provider hosts the payment page, accepts the payment, and settles the collection to the agency. Government agency payment collection in Malaysia already runs this way at national scale: PDRM collects traffic summons payments through MyBayar Saman, with Billplz processing the payments. This article walks through how the rails work, how the collection flow runs end to end, and what the government's own payment standard, Pekeliling PS 2.1, means when your agency evaluates a provider.\n\n## Why Malaysian agencies are moving payment collection online\n\nCounter collection is slow for everyone involved. A citizen takes time off work to queue, pays in cash or by cheque, and leaves with a paper receipt. The finance unit then keys in the receipt, banks in the takings, and matches everything by hand at month end. Cheques add clearing time on top.\n\nOnline collection changes the shape of the work. The payer settles a fine, levy, or licence fee from their own bank account at any hour. The record is created at the moment of payment, so reconciliation starts from complete data instead of manual entry. Collections also stop being bound to counter hours and locations.\n\nEvery agency's process is different. A local council collecting licence fees, a statutory body collecting levies, and a federal department collecting fines all start from different systems and volumes. The rails underneath, though, are the same for all of them.\n\n## The rails: FPX and DuitNow explained for agencies\n\nFPX lets a payer pay directly from their bank account. More than 20 Malaysian banks participate. The payer selects their bank on the payment page, logs in to their own online banking, and approves the payment there. No card is involved, and the agency never sees the payer's banking credentials. PayNet, which operates Malaysia's national payment infrastru
1cture, documents the system at [paynet.my](https://www.paynet.my).\n\nDuitNow supports instant bank-to-bank transfers, and DuitNow QR lets a payer scan a code and pay from their banking app or Wallet. PayNet is progressively moving online bank payments toward DuitNow Online Banking, but FPX remains the standard at checkout today.\n\nA payment provider connects the agency to these rails, and usually to more than the rails. Through one provider, an agency can accept FPX, Wallet, Card, and Instalments on a single payment page, so the citizen chooses whatever they already use. You can read more about how FPX works in [our FPX explainer](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide).\n\n### How the FPX models map to agency use cases\n\nFPX runs three models, documented at [paynet.my](https://www.paynet.my). They map cleanly to how agencies actually collect:\n\n* **B2C** covers an individual paying from a personal bank account. Personal account transactions run from MYR 1.00 to MYR 30,000.00 per transaction. This is the most common agency scenario: a citizen settling a fine, a licence fee, a levy, or a statutory charge.\n* **B2B1 and B2B2** cover a business or organization paying from a corporate account, from MYR 2.00 up to MYR 1,000,000.00 per transaction. The two differ in where the payment starts: B2B1 begins on the agency's payment page, while B2B2 begins inside the payer's own corporate banking platform. These fit agencies that collect from companies: licence fees, statutory contributions, or bulk obligations.\n\nThe practical takeaway: personal-account limits comfortably cover citizen-facing collection, and the corporate models handle the large obligations that would never fit a counter transaction.\n\n## How the collection flow works end to end\n\nThe flow looks the same whether the agency collects fines, levies, or fees:\n\n1. The payer reaches the agency's payment page, through a link on the agency's website or portal, a printed notice, or a QR code. The page can carry the agency's own branding, so the payer knows who they are paying.\n2. The payer picks a payment method: FPX, Wallet, Card, or Instalments. For FPX, they approve the payment inside their own online banking.\n3. The provider confirms the payment in real time, and the payer receives a receipt automatically.\n4. The collection settles to the agency's account. Settlement timing depends on the provider and plan; PDRM's documented deployment receives collections the same day, with real-time payout.\n5. Every transaction lands in the agency's reports automatically, so the finance unit reconciles from complete records instead of keyed-in receipts.\n\nOn the agency side, there are two routes in. With [Billplz Collection](https://main.billplz.com/collection), staff create and send bills through a dashboard, one at a time or by uploading an Excel file for bulk invoicing. Each bill is paid on a Billplz-hosted payment page that works on all devices, with receipts sent automatically after successful payment. Agencies with their own systems integrate through the Billplz API instead: PDRM's MyBayar Saman runs on the API.\n\n## How PDRM collects traffic summons payments online\n\nPDRM (Polis Diraja Malaysia) collects traffic summons payments online through MyBayar Saman, with Billplz processing the payments. The deployment is documented on the [Billplz customers page](https://main.billplz.com/customers), which records four benefits:\n\n* receives fast payments and collections the same day, with real-time payout\n* simplifies the payment process by outsourcing at a cheaper cost\n* minimizes the need for in-house development and finance resources, optimizing efforts and cost\n* uses a custom payment page with PDRM's own branding\n\nTwo of those benefits are worth reading twice. Real-time payout means collections do not sit in transit while the agency waits to reconcile. And the custom payment page matters for trust: a citizen paying a summons wants to see PDRM's branding, not an unfamiliar third party.\n\nPDRM is one of more than 60,000 Malaysian organizations that use Billplz, a base that includes NGOs, zakat bodies, schools, and government agencies. If your agency is weighing a similar move, [Billplz Collection](https://main.billplz.com/collection) is the place to see what the agency-side tooling looks like.\n\n## What Pekeliling PS 2.1 compliance means for procurement\n\nPekeliling Perbendaharaan Malaysia PS 2.1 is the Malaysian government's standard for online payment collection. It set
1s requirements a payment provider must meet: real-time settlement, capped transaction costs, and transparent pricing. For procurement and finance staff, that makes PS 2.1 a concrete yardstick. Instead of comparing marketing claims, you can ask a shortlisted provider to show documented compliance.\n\nBillplz is documented as Pekeliling Perbendaharaan Malaysia PS 2.1 Compliant, and is a certified PayNet system integrator. Both credentials are published at [main.billplz.com/security](https://main.billplz.com/security), alongside the wider security stack that institutional buyers typically ask about.\n\nOne thing to be clear about: PS 2.1 compliance means a provider meets a published government standard. It is not a government endorsement of any provider, and no provider should present it that way.\n\n---\n\n## FAQ\n\n### Can Malaysian government agencies collect payments online?\n\nYes. Agencies and statutory bodies collect online through FPX and DuitNow via a payment provider, which hosts the payment page and settles collections to the agency. PDRM already collects traffic summons payments this way through MyBayar Saman.\n\n### What payment methods can an agency accept?\n\nThrough one provider, an agency can accept FPX, Wallet, Card, and Instalments on a single payment page. FPX is the workhorse for agency collection because payers pay directly from their bank accounts, with personal transactions supported from MYR 1.00 to MYR 30,000.00.\n\n### How fast do collections reach the agency?\n\nSettlement timing depends on the provider and plan. PDRM's documented deployment receives payments and collections the same day, with real-time payout. Payout timing by method and plan is published at [main.billplz.com/pricing](https://main.billplz.com/pricing).\n\n### What is Pekeliling PS 2.1 and why does it matter for agencies?\n\nPekeliling Perbendaharaan Malaysia PS 2.1 is the government's standard for online payment collection, covering real-time settlement, capped transaction costs, and transparent pricing. It matters at procurement: documented compliance shows a provider meets the government's own requirements rather than its own marketing claims.\n\n### How much does it cost an agency to collect online?\n\nFees vary by payment method and plan, and they change over time, so a live pricing page beats any static figure. Billplz publishes current rates for every plan and method at [main.billplz.com/pricing](https://main.billplz.com/pricing).\n\n---\n\n## Where to start\n\nEvery agency's requirements are different: payer mix, transaction sizes, existing systems, and procurement rules all shape the rollout. The rails and the standards will keep evolving too, with DuitNow gradually taking on more of what FPX does today. The mechanics in this article stay the same wherever you start: pick the rails your payers already trust, and a provider that meets the standard your procurement already recognizes.","__component":"shared.rich-text"}]},{"id":552,"documentId":"gujf28ss918hwfvzgw372ijg","title":"Billplz vs HitPay: fees, settlement, and support compared","slug":"billplz-vs-hitpay-malaysia","createdAt":"2026-07-15T02:57:28.830Z","updatedAt":"2026-07-29T07:29:51.877Z","publishedAt":"2026-07-29T07:29:52.052Z","publishDate":"2026-07-29T02:57:00.000Z","cover":{"id":138,"documentId":"yo2pfq3swe7krz5szxtyv0v0","name":"260715_01_01.webp","alternativeText":"Comparison table of Billplz and HitPay pricing models, settlement, and security","caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260715_01_01_bbba0db1ce.webp","hash":"small_260715_01_01_bbba0db1ce","mime":"image/webp","name":"small_260715_01_01.webp","path":null,"size":5.84,"width":500,"height":278,"sizeInBytes":5844},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260715_01_01_bbba0db1ce.webp","hash":"medium_260715_01_01_bbba0db1ce","mime":"image/webp","name":"medium_260715_01_01.webp","path":null,"size":8.88,"width":750,"height":417,"sizeInBytes":8878},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260715_01_01_bbba0db
11ce.webp","hash":"thumbnail_260715_01_01_bbba0db1ce","mime":"image/webp","name":"thumbnail_260715_01_01.webp","path":null,"size":2.48,"width":245,"height":136,"sizeInBytes":2478}},"hash":"260715_01_01_bbba0db1ce","ext":".webp","mime":"image/webp","size":11.55,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260715_01_01_bbba0db1ce.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-15T07:37:37.637Z","updatedAt":"2026-07-15T07:37:43.383Z","publishedAt":"2026-07-15T07:37:37.637Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":279,"metaTitle":"Billplz vs HitPay: fees, settlement, and support compared","metaDescription":"Billplz vs HitPay in Malaysia: how each gateway charges, how fast they settle, security, and support, so you can pick the right fit. Compare both.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260715_01_01_bbba0db1ce.webp","@type":"ImageObject","width":901,"height":501},"@graph":[{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260715_01_01_bbba0db1ce.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Billplz vs HitPay: fees, settlement, and support compared","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"inLanguage":"en-MY","description":"Billplz vs HitPay in Malaysia: how each gateway charges, how fast they settle, security, and support, so you can pick the right fit. Compare both.","dateModified":"2026-07-29T03:29:22.443Z","datePublished":"2026-07-15T10:57:28+08:00","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/billplz-vs-hitpay-malaysia","@type":"WebPage"}},{"@type":"FAQPage","mainEntity":[{"name":"Is Billplz cheaper than HitPay?","@type":"Question","acceptedAnswer":{"text":"It depends on your payment mix, transaction values, and whether you collect online or in person. On FPX, the published rates as of 15 July 2026 are 1.8% + MYR 0.40 per transaction at HitPay and a flat MYR 1.25 (Basic) or MYR 0.75 (Standard) at Billplz, so the gap widens as transaction values grow. For Card and Wallet payments, model your own mix against both published pricing pages.","@type":"Answer"}},{"name":"How much does Billplz cost?","@type":"Question","acceptedAnswer":{"text":"Billplz publishes current rates for every plan and payment method at main.billplz.com/pricing. There are three plans: a free Basic plan, a paid Standard annual membership, and custom Enterprise pricing. Rates differ by plan and payment method, and pricing details can change, so check the live page rather than third-party summaries.","@type":"Answer"}}
1,{"name":"Does HitPay support more payment methods than Billplz?","@type":"Question","acceptedAnswer":{"text":"HitPay's list is longer, but core Malaysian coverage is close. Both accept FPX, DuitNow, Card, the major Wallet options (Touch 'n Go, GrabPay, ShopeePay, Boost), and instalment plans including Atome and PayLater by Grab. HitPay adds Maybank QRPay and cross-border options such as AliPay and WeChatPay. The bigger difference is product breadth: in-person terminals and cross-border acceptance.","@type":"Answer"}},{"name":"Does Billplz have no-code tools like HitPay?","@type":"Question","acceptedAnswer":{"text":"Yes. Catalog, Billplz's standalone commerce platform, provides Catalog Payment Form, a free payment form with link, and Catalog Store, a free online storefront. Billplz Collection covers billing without code: create bills one at a time or in bulk via Excel upload, each paid on a Billplz-hosted Bill Page with automatic receipts. That plays the role of HitPay's invoice generator; their bundled set still adds a recurring billing tool. For selling online without code, the two are closer than the product lists suggest.","@type":"Answer"}},{"name":"Is Billplz safe and compliant?","@type":"Question","acceptedAnswer":{"text":"Yes. Billplz is PCI DSS Level 1 certified, audited annually. It is a certified PayNet system integrator, complies with Pekeliling Perbendaharaan PS 2.1, and maintains 99.9% historical uptime. The full stack is published at main.billplz.com/security.","@type":"Answer"}},{"name":"How fast does Billplz settle?","@type":"Question","acceptedAnswer":{"text":"Billplz publishes payout timing by method at main.billplz.com/pricing: next business day for FPX, T+2 business days for Card, and next day for Wallet, with real-time payout documented at the Enterprise tier. PDRM's documented deployment receives collections the same day with real-time payout.","@type":"Answer"}},{"name":"Can I use either gateway for government or institutional collection?","@type":"Question","acceptedAnswer":{"text":"Billplz documents a public-sector deployment (PDRM's MyBayar Saman) and compliance with Pekeliling Perbendaharaan PS 2.1, the Malaysian government's payment standard. HitPay's site does not currently document an equivalent public-sector deployment; review their pages for their institutional offering.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Billplz vs HitPay: fees, settlement, and support compared","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Billplz vs HitPay in Malaysia: how each gateway charges, how fast they settle, security, and support, so you can pick the right fit. Compare both.","dateModified":"2026-07-29T07:29:49.168Z","datePublished":"2026-07-15T02:57:28.830Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/billplz-vs-hitpay-malaysia","@type":"WebPage"}}},"blocks":[{"id":527,"body":"Comparing Billplz vs HitPay in Malaysia comes down to fit. HitPay suits businesses that need in-person payments and a broad set of no-code tools on a pay-per-transaction model. Billplz suits organizations that collect mainly through FPX online, including government, statutory, and institutional collectors, and buyers who need a documented security and compliance stack. Both publish their pricing: [Billplz pricing](https://main.billplz.com/pricing) and [HitPay pricing](https://hitpayapp.com/my/pricing). This comparison covers how each gateway charges, how fast money settles, security, and support, so you can match one to your payment mix.\n\n## Billplz and HitPay at a glance\n\nBoth gateways let Malaysian businesses accept online payments through local rails. Both publish their rates. Neither is the right answer for everyone.\n\nHitPay is a Singapore-headquartered company, HitPay Payment Solutions Pte Ltd, operating across Southeast Asia. Its published center of gravity is breadth: in-person card terminals, Tap to Pay, cross-border acceptance in multiple markets, and a set of free no-code tools including payment links, online payment forms, recurring billing, an invoice generator, and an online store builder.\n\nBillplz is a Malaysian company, Billplz Sdn Bhd, built in Malaysia and processing payments for Malaysian organizations since 2012, with its team based in Selangor. More than 60,000 Malaysian organizations use it, a base that includes NGOs, zakat bodies, schools, and government agencies. Its documented center of gravity is Malaysia-first: FPX collection and the compliance stack that government and institutional buyers ask about. For selling without code, Catalog, its standalone commerce platform, provides a free payment form with link and a free online storefront. For billing, [Billplz Collection](https://main.billplz.com/collection) creates bills from the dashboard with no code, one at a time or in bulk via Excel upload, each paid on a pre-built, Billplz-hosted Bill Page with automatic receipts.\n\n## How each gateway charges\n\nThe two pricing models are structured differently, and the structure matters more than any single rate.\n\nHitPay publishes a pay-per-transaction model with no setup or monthly fees. Its [Malaysia pricing page](https://hitpayapp.com/my/pricing) lists, as of 15 July 2026, online domestic cards at 1.2% + MYR 1.00, international cards at 3% + MYR 1.00, FPX at 1.8% + MYR 0.40, DuitNow at 1.2%, and per-brand rates for GrabPay, Boost, ShopeePay, Touch 'n Go, and Maybank QRPay. In-person rates differ from online rates.\n\nBillplz publishes three plans: Basic, which is free, Standard, a paid annual membership, and Enterprise, which is custom. Per-transaction fees apply on every plan and are listed by payment method, with FPX charged as a flat per-transaction fee rather than a percentage: MYR 1.25 on Basic and MYR 0.75 on Standard, as published on 15 July 2026. Card rates step down on the Standard plan. Current rates for every method and plan are published at [main.billplz.com/pricing](https://main.billplz.com/pricing). Pricing details change, so treat the live page as the source of truth; third-party summaries can lag behind current rates.\n\nThe structural difference shows most clearly on FPX. HitPay charges a percentage plus a fixed fee per FPX transaction: 1.8% + MYR 0.40 as of 15 July 2026. Billplz charges a flat fee per FPX transaction: MYR 1.25 on Basic and MYR 0.75 on Standard, as of the same date. On a MYR 500.00 collection, the published rates work out to MYR 9.40 against a flat MYR 1.25 or less. As transaction values rise, a percentage grows with the payment; a flat fee does not. At lower transaction values the gap narrows and the percentage model can cost less, so model your own typical ticket size against both published pages.\n\nCompare live rates at [main.billplz.com/pricing](https://main.billplz.com/pricing) and [HitPay's pricing page](https://hitpayapp.com/my/pricing).\n\n### What this means for your payment mix\n\nYour real cost depends on how your customers pay, not on any single headline rate. Model your own mix:\n\n* **Collect mainly through FPX bank transfer, especially at higher transaction values?** Compare HitPay's percentage-based FPX rate against Billplz's flat rate at your typical ticket size.\n* **Card-heavy, local and international?** Compare the published card percentages side by side, including foreign-currency treatment.\n* **Selling in person at a counter or an event?** HitPay documents terminals and Tap to Pay. Billplz's documented products are built for online collection.\n* **High volume?** Both publish custom or enterprise tiers. Talk to each team with your numbers.\n\n## Billplz vs HitPay: side by side\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eHitPay\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCompany\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBillplz Sdn Bhd, a Malaysian company; team based in Selangor; processing payments in Malaysia since 2012\u003c/td\u003e\u003ctd\u003eHitPay Payment Solutions Pte Ltd, headquartered in Singapore; operates across Southeast Asia\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePricing model\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eThree plans (Basic free, Standard annual membership, Enterprise custom) plus per-transaction fees; FPX flat at MYR 1.25 (Basic) or MYR 0.75 (Standard), as of 15 July 2026\u003c/td\u003e\u003ctd\u003eNo subscription; pay per transaction; FPX at 1.8% + MYR 0.40, as of 15 July 2026, per their published pricing page\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePublished pricing\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003ca href=\"https://main.billplz.com/pricing\"\u003emain.billplz.com/pricing\u003c/a\u003e\u003c/td\u003e\u003ctd\u003e\u003ca href=\"https://hitpayapp.com/my/pricing\"\u003ehitpayapp.com/my/pricing\u003c/a\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX (20+ Malaysian banks), DuitNow QR, Wallet (Touch 'n Go eWallet, GrabPay, ShopeePay, Boost), Card (Visa, Mastercard), Instalments (Atome, PayLater by Grab, Shopee SPayLater)\u003c/td\u003e\u003ctd\u003eCards, FPX, DuitNow, GrabPay, Boost, ShopeePay, Touch 'n Go, Maybank QRPay, Atome, AliPay, WeChatPay, and others\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSettlement as documented\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX next business day; Card T+2 business days; Wallet next day; Enterprise plans include real-time payout\u003c/td\u003e\u003ctd\u003eT+2 business days for non-card payment methods; from T+3 business days for cards, final schedule set by their compliance team case by case, as of 15 July 2026\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eIntegrations\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFull API access and \u003ca href=\"https://main.billplz.com/plugins\"\u003e30+ plugins\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eShopify, WooCommerce, Wix, Xero, Google Forms, and others\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eNo-code tools\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eCatalog Payment Form (payment form with link) and Catalog Store (online storefront), both free; Billplz Collection billing with no code: single or bulk bills via Excel, Billplz-hosted Bill Page, automatic receipts\u003c/td\u003e\u003ctd\u003ePayment links, payment forms, recurring billing, invoice generator, online store builder, free\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## How fast each gateway settles\n\nSettlement speed decides how quickly collections become working c
1apital, so check the documented terms rather than assumptions.\n\nBillplz publishes payout timing by method on its [pricing page](https://main.billplz.com/pricing): FPX settles next business day, Card in T+2 business days, and Wallet next day. Enterprise plans include real-time payout; [PDRM's MyBayar Saman collections](https://main.billplz.com/customers), for example, arrive the same day.\n\nHitPay publishes its payout schedule on its [pricing page](https://hitpayapp.com/my/pricing): T+2 business days for non-card payment methods, and from T+3 business days for card payments, with the final schedule set by its compliance team case by case, as of 15 July 2026.\n\nIf settlement speed matters for your cash flow, compare the published schedules directly: next business day for FPX at Billplz against T+2 for non-card methods at HitPay.\n\n## Security and compliance\n\nSecurity is where procurement teams slow down, so here is what each gateway documents.\n\nBillplz publishes its stack at [main.billplz.com/security](https://main.billplz.com/security): PCI DSS Level 1, verified through annual audits. It is a certified PayNet system integrator and complies with Pekeliling Perbendaharaan Malaysia PS 2.1, the government payment standard covering real-time settlement, capped transaction costs, and transparent pricing. It inherits ISO 27001, ISO 27017, ISO 27018, and SOC 2 Type II controls from its cloud infrastructure, maintained and audited continuously, and maintains 99.9% historical uptime.\n\nThis stack matters most if you are a government agency, statutory body, or institution, or if your procurement process asks for certifications by name. PDRM's traffic summons collection through MyBayar Saman is a documented example of that kind of deployment.\n\nHitPay publishes its security and compliance position on its [trust and compliance page](https://hitpayapp.com/my/resources/trust-compliance). As of 20 July 2026, that page lists PCI DSS certification, licensing by the Monetary Authority of Singapore, 99.99% uptime, and platform measures including AES data encryption, external penetration testing, and anti-money laundering tools. For Malaysia, it states that HitPay Payment Solutions Sdn Bhd operates as a technology service provider and partners with Stripe Payments Malaysia Sdn Bhd, a merchant acquirer registered with Bank Negara Malaysia under the Financial Services Act 2013, for regulated activities. The page does not state a PCI DSS level, so ask their team if your procurement requires one.\n\n## Which gateway fits your organization\n\nEvery organization's payment mix is different, so here is the honest split based on what each gateway documents today.\n\n### Choose HitPay if\n\n* You sell in person and need card terminals or Tap to Pay alongside online payments.\n* You sell across borders: their pages document cross-border acceptance in multiple markets and currencies.\n* You want a no-subscription model where you only pay per transaction.\n* You need a bundled recurring billing tool today; their published software set includes one.\n* You need their published plugin list, which includes Shopify, WooCommerce, Wix, Xero, and Google Forms.\n\n### Choose Billplz if\n\n* You prefer a Malaysian company. Billplz Sdn Bhd was built in Malaysia, has focused on Malaysian payments since 2012, and its team is based in Selangor.\n* You collect mainly through FPX bank transfer online and want a flat per-transaction fee on FPX (see [main.billplz.com/pricing](https://main.billplz.com/pricing)).\n* You are a government agency, statutory body, or institution collecting fines, levies, fees, zakat, or tuition. PDRM's MyBayar Saman deployment is documented at [main.billplz.com/customers](https://main.billplz.com/customers).\n* Your procurement is security and compliance sensitive and asks for PCI DSS Level 1, a certified PayNet system integrator, or Pekeliling Perbendaharaan Malaysia PS 2.1 compliance.\n* You value a long local track record: processing payments since 2012, with 60,000+ Malaysian organizations on the platform.\n\nSee what collecting with Billplz looks like at [main.billplz.com/collection](https://main.billplz.com/collection).\n\n---\n\n## FAQ\n\n### Is Billplz cheaper than HitPay?\n\nIt depends on your payment mix, transaction values, and whether you collect online or in person. On FPX, the published rates as of 15 July 2026 are 1.8% + MYR 0.40 per transaction at HitPay and a flat MYR 1.25 (Basic) or MYR 0.75 (Standard) at Billplz, so the gap widens as transaction values grow. For Card and Wallet payments, model your own mix against both published pages: [main.billplz.com/pricing](https://main.billplz.com/pricing) and [hitpayapp.com/my/pricing](https://hitpayapp.com/my/pricing).\n\n### How much does Billplz cost?\n\nBillplz publishes current rates for every plan and payment method at [main.billplz.com/pricing](https://main.billplz.com/pricing). There are three plans: a free Basic plan, a paid Standard annual membership, and custom Enterprise pricing. Rates differ by plan and payment method, and pricing details can change, so check the live page rather than third-party summaries.\n\n### Does HitPay supp
1ort more payment methods than Billplz?\n\nHitPay's list is longer, but core Malaysian coverage is close. Both accept FPX, DuitNow, Card, the major Wallet options (Touch 'n Go, GrabPay, ShopeePay, Boost), and instalment plans including Atome and PayLater by Grab. HitPay adds Maybank QRPay and cross-border options such as AliPay and WeChatPay. The bigger difference is product breadth: HitPay also sells in-person terminals and cross-border acceptance. For local online collection, match either list against how your customers actually pay.\n\n### Does Billplz have no-code tools like HitPay?\n\nYes. Catalog, Billplz's standalone commerce platform, provides Catalog Payment Form, a free payment form with link, and Catalog Store, a free online storefront. Billplz Collection covers billing without code: create bills one at a time or in bulk via Excel upload, each paid on a Billplz-hosted [Bill Page](https://main.billplz.com/collection) with automatic receipts. That plays the role of HitPay's invoice generator; their bundled set still adds a recurring billing tool. For selling online without code, the two are closer than the product lists suggest.\n\n### Is Billplz safe and compliant?\n\nYes. Billplz is PCI DSS Level 1 certified, audited annually. It is a certified PayNet system integrator, complies with Pekeliling Perbendaharaan Malaysia PS 2.1, and maintains 99.9% historical uptime. The full stack is published at [main.billplz.com/security](https://main.billplz.com/security).\n\n### How fast does Billplz settle?\n\nBillplz publishes payout timing by method at [main.billplz.com/pricing](https://main.billplz.com/pricing): next business day for FPX, T+2 business days for Card, and next day for Wallet. Enterprise plans include real-time payout, so collections can arrive the same day.\n\n### Can I use either gateway for government or institutional collection?\n\nBillplz documents a public-sector deployment (PDRM's MyBayar Saman) and compliance with Pekeliling Perbendaharaan Malaysia PS 2.1, the Malaysian government's payment standard. HitPay's site does not currently document an equivalent public-sector deployment; review their pages for their institutional offering.\n\n---\n\n## Choosing between two capable gateways\n\nBoth gateways keep evolving, and the right choice depends on how your organization collects. Compare the published pricing, check the documented settlement terms against your cash flow needs, and weigh the compliance stack your procurement requires. If FPX-first collection for a Malaysian organization is your starting point, review the numbers at [main.billplz.com/pricing](https://main.billplz.com/pricing).","__component":"shared.rich-text"}]},{"id":527,"documentId":"cos4401y67gclywsau8m028h","title":"MyInvois e-invoicing in Malaysia: what you need to know and how payments connect","slug":"myinvois-e-invoicing-malaysia","createdAt":"2026-07-17T04:38:27.331Z","updatedAt":"2026-07-29T04:07:30.530Z","publishedAt":"2026-07-29T04:07:30.677Z","publishDate":"2026-07-21T04:38:00.000Z","cover":{"id":147,"documentId":"kmqrrubkb7f193rgqau7got1","name":"260720_01_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260720_01_01_8ad6f64370.webp","hash":"small_260720_01_01_8ad6f64370","mime":"image/webp","name":"small_260720_01_01.webp","path":null,"size":10.04,"width":500,"height":278,"sizeInBytes":10042},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260720_01_01_8ad6f64370.webp","hash":"medium_260720_01_01_8ad6f64370","mime":"image/webp","name":"medium_260720_01_01.webp","path":null,"size":15.9,"width":750,"height":417,"sizeInBytes":15896},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260720_01_01_8ad6f64370.webp","hash":"thumbnail_260720_01_01_8ad6f64370","mime":"image/webp","name":"thumbnail_260720_01_01.webp","path":null,"size":3.98,"width":245,"height":136,"sizeInBytes":3982}},"hash":"260720_01_01_8ad6f64370","ext":".webp","mime":"image/webp","size":23.42,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260720_01_01_8ad6f64370.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-29T04:06:58.427Z","updatedAt":"2026-07-29T04:06:58.427Z","publishedAt":"2026-07-29T04:06:58.428Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":254,"metaTitle":"MyInvois e-invoicing in Malaysia: what you need to know and how payments connect","metaDescription":"MyInvois e-invoicing in Malaysia, explained plainly: who must comply, current phases and thresholds, and how your payment records connect. Confirm with LHDN.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260720_01_01_8ad6f64370.webp","@type":"ImageObject","width":901,"height":501},"@graph":[{"@id":"https://main.billplz.com/blog/myinvois-e-invoicing-malaysia#article","@type":"Article","author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"MyInvois e-invoicing in Malaysia: what merchants need to know and how payments connect","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"MyInvois e-invoicing in Malaysia, explained plainly: who must comply, current phases and thresholds, and how your payment records connect. Confirm with LHDN.","dateModified":"SET-AT-PUBLISH","datePublished":"SET-AT-PUBLISH","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/myinvois-e-invoicing-malaysia"},{"@id":"https://main.billplz.com/blog/myinvois-e-invoicing-malaysia#faq","@type":"FAQPage","mainEntity":[{"name":"Is my business required to use MyInvois?","@type":"Question","acceptedAnswer":{"text":"It depends on your annual revenue. If your annual revenue is above MYR 1,000,000.00, you are in scope and your phase depends on your revenue band, with the smallest in-scope band mandatory from 1 January 2026. If your annual revenue is below MYR 1,000,000.00, you are currently exempt, though you may opt in. Confirm your exact position with LHDN or your tax advisor.","@type":"Answer"}},{"name":"Is a payment receipt the same as an e-invoice?","@type":"Question","acceptedAnswer":{"text":"No. A payment receipt confirms that money moved. An e-invoice is a tax document that LHDN validates through MyInvois, and once validated it carries a unique identifier and a QR code. A receipt from your payment gateway does not satisfy the e-invoicing mandate on its own.","@type":"Answer"}},{"name":"Do I need special software, or can I use the free MyInvois Portal?","@type":"Question","acceptedAnswer":{"text":"Both routes exist. LHDN provides two mechanisms: the free MyInvois Portal, where you can issue and validate e-invoices directly, and an API integration that connects an e-invoicing solution to MyInvois. The Portal suits lower volumes; an API or a dedicated solution tends to suit higher volumes.","@type":"Answer"}},{"name":"What is a consolidated e-invoice?","@type":"Question","acceptedAnswer":{"text":"It is a single e-invoice that aggregates multiple B2C transactions where individual buyers did not request their own e-invoice, allowed within LHDN's rules. It is common in retail. There is a per-transaction ceiling above which a sale needs its own individual e-invoice, so check the current figure in LHDN's guidelines.","@type":"Answer"}},{"name":"What happens if I am below MYR 1,000,000.00 in annual revenue?","@type":"Question","acceptedAnswer":{"text":"You are currently exempt from e-invoicing. You can still opt in voluntarily if it suits how you work, for example if larger customers ask for e-invoices. Because the exemption threshold has changed before, it is worth confirming your status with LHDN or your tax advisor.","@type":"Answer"}},{"name":"When is my phase's deadline?","@type":"Question","acceptedAnswer":{"text":"Check the timeline table above for your revenue band, then confirm it against the official LHDN e-invoice timeline page. The schedule was last revised on 7 December 2025, so the LHDN page is the reference if anything you read elsewhere disagrees.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"MyInvois e-invoicing in Malaysia: what you need to know and how payments connect","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"MyInvois e-invoicing in Malaysia, explained plainly: who must comply, current phases and thresholds, and how your payment records connect. Confirm with LHDN.","dateModified":"2026-07-29T04:07:23.363Z","datePublished":"2026-07-17T04:38:27.331Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/myinvois-e-invoicing-malaysia","@type":"WebPage"}}},"blocks":[{"id":502,"body":"MyInvois is the platform run by Malaysia's Inland Revenue Board (LHDN) for issuing and validating e-invoices. If you are wondering whether MyInvois e-invoicing in Malaysia applies to your business, the short answer is that it depends on your annual revenue. Businesses with annual revenue above MYR 1,000,000.00 are in scope and roll in by phase, with the smallest in-scope band, up to MYR 5 million, mandatory from 1 January 2026. Businesses with annual revenue below MYR 1,000,000.00 are currently exempt, though they may opt in voluntarily. Rules move, so confirm your exact position with your tax advisor or LHDN.\n\n## The MyInvois e-invoicing timeline and current phases\n\nLHDN rolled out e-invoicing in phases across 2024 to 2026, largest businesses first. The schedule below reflects the official LHDN e-invoice implementation timeline, last revised on 7 December 2025. Any older date circulating online may be stale, so treat this table and the LHDN source behind it as the reference.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePhase\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eAnnual revenue threshold\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eMandatory from\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePhase 1\u003c/td\u003e\u003ctd\u003eMore than MYR 100 million\u003c/td\u003e\u003ctd\u003e1 August 2024\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePhase 2\u003c/td\u003e\u003ctd\u003eMore than MYR 25 million up to MYR 100 million\u003c/td\u003e\u003ctd\u003e1 January 2025\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePhase 3\u003c/td\u003e\u003ctd\u003eMore than MYR 5 million up to MYR 25 million\u003c/td\u003e\u003ctd\u003e1 July 2025\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePhase 4\u003c/td\u003e\u003ctd\u003eUp to MYR 5 million, and above the exemption\u003c/td\u003e\u003ctd\u003e1 January 2026\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\nYou can confirm the current schedule directly on the [official LHDN e-invoice timeline page](https://www.hasil.gov.my/e-invois/pelaksanaan-e-invois-di-malaysia/garis-masa-pelaksanaan-e-invois/).\n\n## Who must comply and who is exempt\n\nThe line that matters most for smaller businesses is MYR 1,000,000.00 in annual revenue. Below that line, you are currently exempt from e-invoicing, though you may opt in if it suits you. Above that line, you are in scope and your phase depends on your revenue band, as shown in the table above.\n\nThis threshold was revised to MYR 1,000,000.00 on 7 December 2025. If you have read an older article citing an MYR 500,000.00 exemption, that figure is out of date. A previously planned lowest band was also cancelled, so there is no additional phase below Phase 4 to plan around.\n\nOne practical note on \"revenue\": LHDN defines it against a reference year, not simply your current month-to-month takings. If you are close to the threshold, or unsure which phase you fall into, it is worth pinning down your exact position with LHDN or your tax advisor rather than guessing.\n\n## What changes day to day for a merchant\n\nFor an in-scope business, the shift is mostly in how your invoices are handled, not in how you run your day. The invoices you issue to customers become e-invoices that you submit to MyInvois for validation. Once LHDN validates a document, it carries a unique identifier and a QR code that confirm it is a valid e-invoice.\n\nYour buyers can request an e-invoice for a transaction. Where a buyer does not request one, some sales can be captured together through a consolidated e-invoice, within LHDN's rules. This is common in retail and other high-volume B2C settings, where issuing an individual e-invoice for every walk-in sale would be impractical.\n\nLHDN also provides an interim relaxation period for each phase to ease early compliance, giving newly in-scope businesses room to adjust before the rules apply in full. The exact end date of the Phase 4 relaxation is the detail most worth checking on the day you act, because it has been subject to change. Confirm the current end date on the LHDN e-invoice guidelines before you rely on it.\n\n## How payments connect\n\nThis is where merchants most often get confused. A payment gateway and an e-invoice are two different things, and one does not replace the other.\n\n* A payment gateway confirms that money moved. It produces a payment record and a receipt for the transaction.\n* An e-invoice is a tax document that LHDN validates through MyInvois. A payment receipt is not an e-invoice, and it does not satisfy the mandate on its own.\n\nIn practice, most in-scope merchants run two things side by side. They use their payment gateway to collect payments and keep clean records, and they use an e-invoicing solution or the free MyInvois Portal to issue and validate e-invoices. The two connect through your records: clean payment data, meaning the amount, the date, the reference, and the customer, makes it easier to prepare accurate e-invoices and reconcile them later.\n\nA neutral end-to-e
1nd workflow looks like this. The customer pays. The gateway records the payment and issues a receipt. The merchant, or their accounting or e-invoicing tool, issues the e-invoice and submits it to MyInvois. LHDN validates the document. The records are then reconciled against the payment. The gateway handles the collection and the record; your e-invoicing route handles the tax document.\n\nOn the payment side of that workflow, [Billplz](https://main.billplz.com/collection) helps organizations collect payments and keeps a clean record of every transaction, which makes preparing and reconciling e-invoices less of a chore. Billplz does not issue e-invoices or submit them to MyInvois, and a payment record is not an e-invoice. The e-invoicing step stays with LHDN's MyInvois Portal or your chosen e-invoicing solution.\n\n## Consolidated e-invoices for B2C\n\nFor retail and other B2C sales where individual buyers do not ask for an e-invoice, suppliers may aggregate those transactions into a single consolidated e-invoice, within LHDN's rules. This keeps the paperwork manageable for high-volume, walk-in businesses.\n\nThere is a per-transaction ceiling: above a certain value, a sale needs its own individual e-invoice and cannot be rolled into the consolidated one. LHDN sets that figure in its e-invoice guidelines, and it is worth confirming the current value on the day rather than relying on a number you saw elsewhere. If in doubt, check the guideline or ask your tax advisor.\n\n---\n\n## FAQ\n\n### Is my business required to use MyInvois?\n\nIt depends on your annual revenue. If your annual revenue is above MYR 1,000,000.00, you are in scope and your phase depends on your revenue band, with the smallest in-scope band mandatory from 1 January 2026. If your annual revenue is below MYR 1,000,000.00, you are currently exempt, though you may opt in. Confirm your exact position with LHDN or your tax advisor.\n\n### Is a payment receipt the same as an e-invoice?\n\nNo. A payment receipt confirms that money moved. An e-invoice is a tax document that LHDN validates through MyInvois, and once validated it carries a unique identifier and a QR code. A receipt from your payment gateway does not satisfy the e-invoicing mandate on its own.\n\n### Do I need special software, or can I use the free MyInvois Portal?\n\nBoth routes exist. LHDN provides two mechanisms: the free MyInvois Portal, where you can issue and validate e-invoices directly, and an API integration that connects an e-invoicing solution to MyInvois. The Portal suits lower volumes; an API or a dedicated solution tends to suit higher volumes.\n\n### What is a consolidated e-invoice?\n\nIt is a single e-invoice that aggregates multiple B2C transactions where individual buyers did not request their own e-invoice, allowed within LHDN's rules. It is common in retail. There is a per-transaction ceiling above which a sale needs its own individual e-invoice, so check the current figure in LHDN's guidelines.\n\n### What happens if I am below MYR 1,000,000.00 in annual revenue?\n\nYou are currently exempt from e-invoicing. You can still opt in voluntarily if it suits how you work, for example if larger customers ask for e-invoices. Because the exemption threshold has changed before, it is worth confirming your status with LHDN or your tax advisor.\n\n### When is my phase's deadline?\n\nCheck the timeline table above for your revenue band, then confirm it against the [official LHDN e-invoice timeline page](https://www.hasil.gov.my/e-invois/pelaksanaan-e-invois-di-malaysia/garis-masa-pelaksanaan-e-invois/). The schedule was last revised on 7 December 2025, so the LHDN page is the reference if anything you read elsewhere disagrees.\n\n---\n\n## Getting your bearings\n\nE-invoicing in Malaysia is settling in, and LHDN is still refining the rules, so dates and finer details can shift. The steady parts are worth holding onto: know your revenue band, know your phase, and keep clean records of how you get paid. Your payment gateway helps with the collection and the records; MyInvois and your e-invoicing route handle the tax document. For the parts that are specific to your business, confirm your exact obligation with LHDN or your tax advisor.","__component":"shared.rich-text"}]},{"id":528,"documentId":"hozcxv8dqzmipi4150kn7l27","title":"Is Billplz safe? The security and compliance stack","slug":"is-billplz-safe","createdAt":"2026-07-16T06:04:17.344Z","updatedAt":"2026-07-29T04:08:19.076Z","publishedAt":"2026-07-29T04:08:19.211Z","publishDate":"2026-07-17T06:04:00.000Z","cover":{"id":146,"documentId":"glxzg1czolvyf8gcrlfewddq","name":"260716_05_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260716_05_01_c77f5d315d.webp","hash":"small_260716_05_01_c77f5d315d","mime":"image/webp","name":"small_260716_05_01.webp","path":null,"size":15.52,"width":500,"height":278,"sizeInBytes":15524},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260716_05_01_c77f5d315d.webp","hash":"medium_260716_05_01_c77f5d315d","mime":"image/webp","name":"medium_260716_05_01.webp","path":null,"size":25.33,"width":750,"height":417,"sizeInBytes":25330},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260716_05_01_c77f5d315d.webp","hash":"thumbnail_260716_05_01_c77f5d315d","mime":"image/webp","name":"thumbnail_260716_05_01.webp","path":null,"size":5.54,"width":245,"height":136,"sizeInBytes":5544}},"hash":"260716_05_01_c77f5d315d","ext":".webp","mime":"image/webp","size":36.33,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_05_01_c77f5d315d.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-29T04:06:47.638Z","updatedAt":"2026-07-29T04:06:47.638Z","publishedAt":"2026-07-29T04:06:47.639Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":255,"metaTitle":"Is Billplz safe? The security and compliance stack","metaDescription":"Is Billplz safe? PCI DSS Level 1 certified, a certified PayNet system integrator, PS 2.1 compliant, with 99.9% historical uptime. What each layer means.","metaKeywords":null,"metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_05_01_c77f5d315d.webp","@type":"ImageObject","width":901,"height":501},"@graph":[{"@id":"https://main.billplz.com/blog/is-billplz-safe#article","@type":"Article","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_05_01_f185971e1e.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"headline":"Is Billplz safe? The security and compliance stack, explained","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Is Billplz safe? PCI DSS Level 1 certified, a certified PayNet system integrator, PS 2.1 compliant, with 99.9% historical uptime. What each layer means.","dateModified":"2026-07-17T02:33:12.083Z","datePublished":"2026-07-16T06:04:17.344Z","articleSection":"Insights","mainEntityOfPage":"https://main.billplz.com/blog/is-billplz-safe"},{"@id":"https://main.billplz.com/blog/is-billplz-safe#faq","@type":"FAQPage","mainEntity":[{"name":"Is Billplz safe?","@type":"Question","acceptedAnswer":{"text":"Yes. Billplz is PCI DSS Level 1 certified, a certified PayNet system integrator, and compliant with Pekeliling Perbendaharaan PS 2.1, with 99.9% historical uptime. The documented stack is published at main.billplz.com/security.","@type":"Answer"}},{"name":"Is Billplz PCI DSS compliant?","@type":"Question","acceptedAnswer":{"text":"Yes. Billplz is PCI DSS Level 1 certified, the highest level of payment card security compliance, verified through annual audits of the payment processing environment.","@type":"Answer"}},{"name":"Does Billplz meet Malaysian government payment standards?","@type":"Question","acceptedAnswer":{"text":"Yes. Billplz complies with Pekeliling Perbendaharaan Malaysia PS 2.1, the government's payment standard for real-time settlement, capped transaction costs, and transparent pricing, and it is a certified PayNet system integrator. Compliance means the platform meets a published standard, not that any government body endorses Billplz.","@type":"Answer"}}]}],"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Is Billplz safe? The security and compliance stack","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Is Billplz safe? PCI DSS Level 1 certified, a certified PayNet system integrator, PS 2.1 compliant, with 99.9% historical uptime. What each layer means.","dateModified":"2026-07-29T04:08:16.624Z","datePublished":"2026-07-16T06:04:17.344Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/is-billplz-safe","@type":"WebPage"}}},"blocks":[{"id":503,"body":"Yes, Billplz is safe, and the answer is documented rather than asserted. Billplz is PCI DSS Level 1 certified, a certified PayNet system integrator, and compliant with Pekeliling Perbendaharaan Malaysia PS 2.1, with 99.9% historical uptime. Every credential in this article is published on the Billplz [security page](https://main.billplz.com/security), which is the canonical source for the full stack. This article does not restate that page. It explains, in plain language, what each layer protects for a Malaysian organization moving money through the platform.\n\n## What makes Billplz safe: the certifications, explained\n\nCertifications only help a reader who knows what they cover. Here is what each one protects, stated plainly.\n\nPCI DSS Level 1 is the highest level of payment card security compliance. Billplz holds it, verified through annual audits of the payment processing environment. For an organization, that means card data moves through an environment that an external assessor checks every year against a recognized standard.\n\nBillplz is a certified PayNet system integrator, certified by PayNet Malaysia to integrate DuitNow payments. This credential covers the technical connection to Malaysia's national payment rails, which is the plumbing behind everyday bank transfers and QR payments.\n\nBillplz complies with Pekeliling Perbendaharaan Malaysia PS 2.1, the government's payment standard covering real-time settlement, capped transaction costs, and transparent pricing. Compliance means the platform meets a published government requirement. It is a standard the platform meets, not a government endorsement of Billplz.\n\nBillplz is a Visa Payment Facilitator, authorized by Visa to provide payment services. For an organization, that authorization is what allows the platform to accept card payments within Visa's own rules.\n\n### Security inherited from cloud infrastructure\n\nSome of the most recognized security standards sit underneath the platform rather than on it. In the words of the security page, \"We inherit enterprise-grade security from our cloud infrastructure, maintained and audited continuously.\"\n\nThat inherited layer includes ISO 27001:2013, ISO 27017:2015, ISO 27018:2019, and SOC 2 Type II. These are held and maintained by the cloud infrastructure Billplz runs on, and audited continuously by that infrastru
1cture. Billplz benefits from the controls without being the party that holds those particular certifications, a common arrangement for platforms built on major cloud providers.\n\n## How the platform stays reliable: what it means in practice\n\nSecurity is not only about certificates. It is also about the platform being available and transactions staying protected in transit.\n\nBillplz maintains 99.9% historical uptime. The reliability layer behind that figure includes auto-scaling infrastructure, multi-region redundancy via Cloudflare, real-time monitoring through Sentry, and centralized audit trails through Papertrail. Traffic is protected with 2,048-bit SSL encryption end to end.\n\nFor an organization, this means two practical things. The platform stays available when payers arrive, and payment data stays encrypted while it travels between the payer, the platform, and the bank.\n\n## The standards organizations already trust: what it means\n\nThe stack above is not unusual for the environments that handle serious money. As the security page puts it, these are \"the same standards trusted by banks, government agencies and Malaysia's largest organizations\".\n\nThe scale behind that statement is documented. More than 60,000 Malaysian organizations use Billplz, a base that includes NGOs, zakat bodies, schools, and government agencies. Billplz has processed payments since 2012, moving over MYR 5 billion annually and over 50,000 transactions each day. PDRM (Polis Diraja Malaysia) collects traffic summons payments through the platform, a deployment documented on the Billplz [customers page](https://main.billplz.com/customers). A national police force collecting summons payments on the same stack
1is a plain fact worth stating, and the documentation is public.\n\n## Security is continuous work: what is next\n\nSecurity is never finished. Standards evolve, audits recur, and monitoring runs around the clock rather than at a single point in time. Billplz treats the stack as ongoing work rather than a box that has been ticked, because there is always more to protect and more to improve.\n\nFor the full technical detail, including every credential named here, the [security page](https://main.billplz.com/security) is the place to look.\n\n---\n\n## FAQ\n\n### Is Billplz safe?\n\nYes. Billplz is PCI DSS Level 1 certified, a certified PayNet system integrator, and compliant with Pekeliling Perbendaharaan PS 2.1, with 99.9% historical uptime. The documented stack is published at [main.billplz.com/security](https://main.billplz.com/security).\n\n### Is Billplz PCI DSS compliant?\n\nYes. Billplz is PCI DSS Level 1 certified, the highest level of payment card security compliance, verified through annual audits of the payment processing environment.\n\n### Does Billplz meet Malaysian government payment standards?\n\nYes. Billplz complies with Pekeliling Perbendaharaan Malaysia PS 2.1, the government's payment standard for real-time settlement, capped transaction costs, and transparent pricing, and it is a certified PayNet system integrator. Compliance means the platform meets a published standard, not that any government body endorses Billplz.","__component":"shared.rich-text"}]},{"id":423,"documentId":"u046uh9tsfrnx3b1in1o8clt","title":"Merchant Discount Rate: What is it \u0026 its impact on transactions","slug":"merchant-discount-rate-guide","createdAt":"2025-12-02T05:08:36.640Z","updatedAt":"2026-04-29T03:34:03.613Z","publishedAt":"2026-04-29T03:34:03.777Z","publishDate":"2025-12-02T05:08:36.640Z","cover":{"id":120,"documentId":"bqlb177smdrsx0rsdhfmi1wl","name":"Hero Image.webp","alternativeText":"Merchant discount rate","caption":"Merchant discount rate","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_ffade2a5cd.webp","hash":"small_Hero_Image_ffade2a5cd","mime":"image/webp","name":"small_Hero Image.webp","path":null,"size":10.75,"width":500,"height":278,"sizeInBytes":10748},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_ffade2a5cd.webp","hash":"medium_Hero_Image_ffade2a5cd","mime":"image/webp","name":"medium_Hero Image.webp","path":null,"size":17.25,"width":750,"height":417,"sizeInBytes":17246},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_ffade2a5cd.webp","hash":"thumbnail_Hero_Image_ffade2a5cd","mime":"image/webp","name":"thumbnail_Hero Image.webp","path":null,"size":4.52,"width":245,"height":136,"sizeInBytes":4522}},"hash":"Hero_Image_ffade2a5cd","ext":".webp","mime":"image/webp","size":29.39,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_ffade2a5cd.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-27T01:51:51.618Z","updatedAt":"2025-11-27T02:03:23.479Z","publishedAt":"2025-11-27T01:51:51.618Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":150,"metaTitle":"Merchant Discount Rate: What is it \u0026 its impact on transactions","metaDescription":"Learn what Merchant Discount Rate (MDR) is, how it impacts your business, and how to manage costs with local payment options like FPX and DuitNow QR via Billplz.\n","metaKeywords":"Merchant Discount Rate, MDR, payment gateway comparison Malaysia, Malaysian payment gateway, FPX payment gateway, Billplz review, Toyyibpay review, payment gateway for SME Malaysia, online payment Malaysia, payment gateway fees Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_ffade2a5cd.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Merchant Discount Rate: What is it \u0026 its impact on transactions","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Learn what Merchant Discount Rate (MDR) is, how it impacts your business, and how to manage costs with local payment options like FPX and DuitNow QR via Billplz.\n","dateModified":"2026-04-29T03:34:02.274Z","datePublished":"2025-12-02T05:08:36.640Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/merchant-discount-rate-guide","@type":"WebPage"}}},"blocks":[{"id":398,"body":"**Key takeaways:**\n\n* MDR stands for Merchant Discount Rate, a fee charged to businesses for accepting electronic payments like cards, e-wallets, and online transfers.\n* MDR is made up of several components, like interchange fees, card network charges, and payment gateway markups.\n* In Malaysia, MDR varies by payment method, with credit cards typically carrying the highest rates, while FPX and DuitNow QR offer more affordable options.\n* High MDR can affect your profit margins, especially for SMEs, and may influence which payment methods you promote or accept.\n* Businesses can reduce MDR costs by encouraging local payment methods, negotiating with providers, and optimising their checkout experience.\n* Billplz supports local payment rails and transparent pricing, helping Malaysian merchants manage MDR more efficiently and sustainably.\n\n## Introduction\n\nFor any business that accepts payments electronically, whether by card, e-wallet, or online transfer, the Merchant Discount Rate (MDR) is a cost that quietly affects every transaction. It might be just a few percent, but over time, it can significantly shape your margins.\n\nWith Malaysiaâs growing adoption of FPX, DuitNow QR, and e-wallets, understanding MDR has become more important. \n\nThis guide breaks down MDR, what influences it, and how businesses can reduce costs, especially with local solutions like Billplz.\n\n## What is a Merchant Discount Rate (MDR) and how does it work?\n\nThe Merchant Discount Rate (MDR) is the fee a business pays each time it accepts an electronic payment. The fee is usually a small percentage of the transaction value and is deducted automatically before the funds reach your bank account.\n\n**A simple example:** \nIf your MDR is 2% and a customer pays RM100, youâll receive RM98 in your bank account, and RM2 goes to the payment provider and other intermediaries.\n\nMDR is a standard part of electronic payments in Malaysia, and understanding how it works helps businesses manage costs and protect margins.\n\n### What are the components of the Merchant Discount Rate?\n\nMDR is made up of several underlying fees, each serving a different part of the payment process:\n\n* **Interchange fee**: Paid to the cardholderâs bank. This covers fraud risk, authorisation, and handling the transaction. Credit cards usually have higher interchange fees than debit cards.\n* **Card scheme or network fee**: Charged by global networks such as Visa and Mastercard. This fee supports the network infrastructure that routes and verifies card payments.\n* **Acquirer or payment gateway markup**: Added by the provider that processes the transaction for the merchant. This is where pricing can vary widely depending on the gateway, business type, volume, and negotiated terms.\n\n#### MDR vs interchange fee\n\nInterchange fees and Merchant Discount Rates (MDR) are closely related, but theyâre not the same.\n\nThe interchange fee is a base cost set by the card networks (like Visa or Mastercard) and paid to the cardholderâs bank every time a transaction is made. It covers the cost of processing, fraud protection, and risk management. While important, this fee is only one part of the overall payment cost.\n\nThe MDR is the total fee a merchant pays per transaction. It includes:\n\n* The interchange fee,\n* The card networkâs fee, and\n* The payment gateway or acquirerâs markup.\n\nAs a business owner, you donât typically see the breakdown of these individual fees. What you do see is the final MDR on your transaction reports.\n\n## How does MDR affect your transactions and margins?\n\nMDR is deducted before you receive the funds, which means it directly reduces your net revenue. For small businesses or high-volume merchants, even a 1â2% fee can impact profit margins over time.\n\nIn Malaysia, credit card payments often carry a higher MDR (up to 3%), while e-wallets range from 1%â2%. Local methods like FPX and DuitNow QR typically offer lower MDR, making them a more cost-efficient option for small businesses.\n\nBeyond fees, MDR can also shape business decisions; from how you price products to which payment methods you promote. Many merchants favour lower-MDR options to protect their margins, especially for high-volume or local transactions.\n\n## What factors influence the MDR rate?\n\n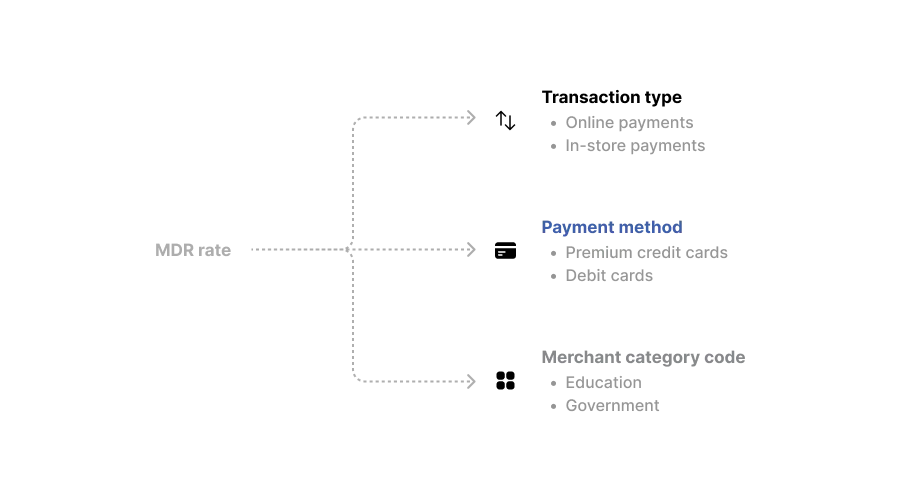\n\nMDR isnât a fixed fee. It varies depen
1ding on your business type, payment method, and how the transaction is processed. Key factors include:\n\n* **Transaction type**: Online or cardânotâpresent payments usually carry a higher MDR due to fraud risk. Inâstore payments often cost less.\n* **Payment method**: Premium credit cards tend to cost more than debit cards or QR-based payments.\n* [**Merchant Category Code (MCC)**](https://main.billplz.com/blog/insights/merchant-category-codes-mcc-what-are-they-lookup-guide): This business classification affects network fees. Some categories, like education or government, enjoy a lower MDR.\n* **Business size and transaction volume**: Higher volume merchants may qualify for better rates through negotiation.\n* **Currency and country**: Cross-border and foreign currency payments typically involve higher fees.\n* **Payment provider markup**: Each gateway adds its own charges, impacting your final MDR.\n\n## What is a typical MDR in Malaysia?\n\nMerchant Discount Rates in Malaysia vary depending on the payment method and provider. Hereâs what you can expect:\n\n* **Credit cards**: Around 1.5% to 3%, depending on card type and provider\n* **Debit cards**: Typically below 1%\n* **E-wallets**: Usually fall between 1% to 2%\n* [**FPX**](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide) **and DuitNow QR**: Range from 0% to 3%, often lower for SMEs\n* [**Buy Now Pay Later (BNPL)**](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz): Can go from 1.5% to over 3%, depending on the providerâs model.\n\nSome QR payment providers also waive MDR for micro-merchants or during promotional periods, especially under initiatives to support digital adoption. Always confirm the exact rate with your payment provider, as costs can vary based on your industry, transaction volume, and merchant classification.\n\n## How can businesses reduce their MDR charges and improve payment cost efficiency?\n\nWhile MDR is unavoidable, smart decisions can help you manage the cost. Start by prioritising lower-cost methods like FPX and DuitNow QR for local payments. Encourage debit card or e-wallet usage over credit cards, which often carry higher fees.\n\nA streamlined checkout also reduces failed payments and disputes, helping you avoid unnecessary costs. If you process high volumes or recurring transactions, talk to your provider about better rates.\n\nWith local rails, transparent pricing, and real-time fee visibility, [Billplz](https://main.billplz.com/) gives Malaysian businesses the tools to reduce MDR and improve their payment cost structure.\n\n## Role of payment gateway in MDR: How does Billplz help?\n\nYour choice of payment gateway directly affects how much you pay in MDR. From the payment methods available to how fees are structured and reported, it all adds up, especially for growing businesses.\n\nBillplz is designed with Malaysian merchants in mind, offering:Â \n\n* Transparent, MYR-based pricing with no hidden charges, so you always know what you're paying for.\n* Support for lower-cost, local payment methods like FPX, DuitNow QR, and e-wallets, helping reduce your MDR from the start.\n* Real-time reporting and reconciliation tools that let you track every fee, transaction, and settlement clearly.\n* Flexible plans, including optional PayPal integration for businesses that also serve international customers.\n\nWhether you're running an online store, managing recurring payments, or collecting donations, Billplz gives you the control and clarity to keep your costs efficient and predictable.\n\nAlso read: [Jom Duitnow with Billplz: Solutions for online businesses](https://main.billplz.com/blog/products/duitnow-qr-for-online-businesses)\n\n---\n\n## FAQ\n\n### How does MDR affect my business profitability?\n\nIt reduces your net earnings from each sale. Even a small percentage can add up, especially for businesses with tight margins or high-volume transactions.\n\n### Are there MDR waivers for small businesses in Malaysia?\n\nYes. Some QR-based payments (like DuitNow QR) come with reduced or waived MDR, especially for micro and small merchants, depending on the acquiring bank or payment provider.\n\n### Does accepting e-wallets or QR reduce my MDR?\n\nOften, yes. E-wallet and QR-based payments typically have lower MDR compared to credit cards, making them a cost-effective option for local transactions.\n\n### What is the average merchant discount rate for businesses?\n\nMost MDRs fall between 1% to 3%, depending on the payment method, business category, and provider. QR and debit card rates are generally on the lower end.\n\n### How do interchange fees relate to MDR?\n\nInterchange fees are one component of MDR, paid to the cardholderâs bank. Merchants donât see this breakdown; they only pay the final MDR charged by their gateway.\n\n### Can merchants negotiate their MDR?\n\nYes. Businesses with high transaction volume or low-risk profiles can often negotiate lower MDR rates with their payment gateway or acquiring bank.\n\n### Why is MDR higher for online transactions?\n\nOnline (card-not-present) payments carry higher fraud risk and processing complexity, which results in higher MDR.\n\n### How is MDR different for credit and debit cards?\n\nCredit cards generally have higher MDR due to risk and reward-based fees. Debit card transactions are processed at a lower cost and usually carry a lower MDR. Â \n\n---\n\n## Conclusion\n\nMDR is part of doing business in a digital economy, but that doesnât mean it should go unchecked. For Malaysian merchants, understanding how MDR works, what influences it, and how to control it can lead to better margins and healthier cash flow.\n\nBy choosing a gateway like Billplz that prioritises local payment rail
1s and transparent pricing, businesses can gain better control over payment costs without compromising on customer experience.\n\nReview your current MDR rates, compare providers, and explore how [_**Billplz**_](https://main.billplz.com/pricing) can help bring more clarity, control, and cost-efficiency to your payment process.","__component":"shared.rich-text"}]},{"id":418,"documentId":"xhp0wa41z27tt9wjzds1sndi","title":"Stripe vs PayPal: Which payment gateway should you choose?","slug":"stripe-vs-paypal-which-should-you-choose","createdAt":"2025-12-02T04:55:39.670Z","updatedAt":"2026-01-06T01:23:08.353Z","publishedAt":"2026-01-06T01:23:08.928Z","publishDate":"2025-12-02T04:55:39.670Z","cover":{"id":118,"documentId":"b0trz9nd8ub74vhpaevogxwh","name":"Hero Image.webp","alternativeText":"Comparison Stripe with Paypal","caption":"Comparison Stripe with Paypal","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_e655957bb9.webp","hash":"small_Hero_Image_e655957bb9","mime":"image/webp","name":"small_Hero Image.webp","path":null,"size":8.05,"width":500,"height":278,"sizeInBytes":8054},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_e655957bb9.webp","hash":"medium_Hero_Image_e655957bb9","mime":"image/webp","name":"medium_Hero Image.webp","path":null,"size":12.57,"width":750,"height":417,"sizeInBytes":12570},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_e655957bb9.webp","hash":"thumbnail_Hero_Image_e655957bb9","mime":"image/webp","name":"thumbnail_Hero Image.webp","path":null,"size":3.08,"width":245,"height":136,"sizeInBytes":3080}},"hash":"Hero_Image_e655957bb9","ext":".webp","mime":"image/webp","size":16.77,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_e655957bb9.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-27T01:51:32.188Z","updatedAt":"2025-11-27T02:04:01.258Z","publishedAt":"2025-11-27T01:51:32.189Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":145,"metaTitle":"Stripe vs PayPal: Which payment gateway should you choose?","metaDescription":"Compare Stripe and PayPal for fees, features, and suitability for Malaysian businesses. Learn which works best and how Billplz supports local payments.\n","metaKeywords":"Stripe, Paypal, payment gateway comparison Malaysia, Malaysian payment gateway, FPX payment gateway, Billplz review, Toyyibpay review, payment gateway for SME Malaysia, online payment Malaysia, payment gateway fees Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_e655957bb9.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Stripe vs PayPal: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Stripe and PayPal for fees, features, and suitability for Malaysian businesses. Learn which works best and how Billplz supports local payments.\n","dateModified":"2026-01-06T01:23:06.606Z","datePublished":"2025-12-02T04:55:39.670Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/stripe-vs-paypal-which-should-you-choose","@type":"WebPage"}}},"blocks":[{"id":393,"body":"**Key takeaways:**\n\n* Stripe and PayPal are strong global platforms, but each serves different business needs.\n* Stripe offers flexible, developer-driven payment infrastructure ideal for SaaS and scaling eCommerce.\n* PayPal provides quick setup, broad consumer trust, and simple invoicing for freelancers and small businesses.\n* Neither platform fully supports Malaysian payment methods such as DuitNow QR or local e-wallets.\n* Billplz fills this local gap with MYRânative support for FPX, DuitNow, e-wallets, BNPL, and fast bank settlements.\n* With optional integrations, Billplz lets businesses manage both local and international payments in one dashboard.\n\n## Introduction\n\nStripe and PayPal are two of the most recognised names in global payments. Whether youâre running an eCommerce store, a SaaS platform, or freelancing across borders, chances are youâve come across both.\n\nWhile Stripe is known for its developer-first, scalable infrastructure, PayPal dominates with its ease of use and brand familiarity. In this guide, weâll compare the two across setup, features, fees, and suitability for Malaysian businesses.\n\n## Overview of both platforms\n\n### What is Stripe?\n\n[Stripe](https://stripe.com/en-my) is a full-stack payment processor offering APIs and infrastructure for businesses to accept online and offline payments. Itâs especially popular among startups and tech-forward companies thanks to its deep customisation and automation capabilities.\n\nWhile Stripe is officially available in Malaysia, it lacks support for local payment methods like DuitNow, which can be limiting for merchants serving local customers.\n\n### What is PayPal?\n\n[PayPal](https://www.paypal.com/) is a digital wallet and payment processor that enables users to send, receive, and store money online. For businesses, it offers an easy-to-set-up gateway that integrates with major platforms like Shopify and WooCommerce.\n\nIts plug-and-play setup, along with high consumer trust, makes PayPal a convenient choice for small businesses and freelancers. However, its fees are notably higher for international transactions.\n\n## Stripe vs PayPal: Comparison of key features\n\nHereâs a side-by-side look at how Stripe and PayPal compare across key business and payment features.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003eFeature\u003c/td\u003e\u003ctd\u003eStripe\u003c/td\u003e\u003ctd\u003ePayPal\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eCore Focus\u003c/td\u003e\u003ctd\u003eDeveloper-first payment infrastru
1cture for custom integration\u003c/td\u003e\u003ctd\u003eConsumer-facing digital wallet and checkout solution\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eIdeal For\u003c/td\u003e\u003ctd\u003eSaaS platforms, global marketplaces, and scalable eCommerce\u003c/td\u003e\u003ctd\u003eFreelancers, small businesses, and service-based eCommerce\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePayment Methods\u003c/td\u003e\u003ctd\u003eCredit/debit cards, Apple Pay, Alipay; limited support for local methods\u003c/td\u003e\u003ctd\u003eCards, PayPal wallet; limited support for local bank or QR methods\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eMalaysian Support\u003c/td\u003e\u003ctd\u003eAvailable since 2019; does not support FPX or DuitNow natively\u003c/td\u003e\u003ctd\u003eAvailable and supports MYR; local withdrawals enabled\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eSetup Complexity\u003c/td\u003e\u003ctd\u003eRequires developer resources for setup and integration\u003c/td\u003e\u003ctd\u003eSimple setup with ready-to-use plugins and minimal technical effort\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFees\u003c/td\u003e\u003ctd\u003e3.0% + FX markup per transaction (may vary by use case)\u003c/td\u003e\u003ctd\u003e3.9%â4.4% + FX markup and fixed fee per transaction\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePayout Time\u003c/td\u003e\u003ctd\u003eTypically 5â7 business days to Malaysian bank accounts\u003c/td\u003e\u003ctd\u003eUsually 3â5 business days for local withdrawals\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePlatform Integration\u003c/td\u003e\u003ctd\u003eHighly flexible with API; integrates with Shopify, WooCommerce, and more\u003c/td\u003e\u003ctd\u003eBuilt-in integrations with major platforms and marketplaces\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n_Also read:_ [_Wise vs PayPal: Which payment gateway should you choose?_](https://main.billplz.com/blog/products/wise-vs-paypal-malaysia-payment-comparison)\n\n### Ease of use and setup\n\nStripe is built for developers, requiring technical resources for setup and customisation. This enables highly tailored payment flows but adds complexity. \n\nPayPal, by contrast, is designed for ease. You can start accepting payments within minutes, making it ideal for solo entrepreneurs or smaller teams.\n\n### Features and flexibility\n\nStripe shines in flexibility, supporting over 135 currencies, recurring billing, and real-time reporting. Its APIs are robust and suitable for scaling businesses. \n\nPayPal is simpler, offering invoicing, instant payments, and access to business tools like debit cards and working capital loans. Itâs effective but limited in comparison.\n\n### Stripe vs PayPal: Fees and currency exchange rates\n\n#### Stripe fees\n\nStripe charges around 3.0% per transaction, plus a small fixed fee (e.g. MYR 1.00). Cross-border transactions involve currency conversion fees, though theyâre not always clearly broken out. There are no monthly or setup fees, but custom integration may require developer costs.\n\n#### PayPal fees\n\nPayPal typically charges 3.9â4.4% + MYR 2.00 per transaction, along with a currency conversion markup (around 3% to 4%). You may also incur withdrawal and cross-border fees. These charges can accumulate quickly, especially for freelancers or small businesses dealing with overseas clients.\n\n### Payment methods and local compatibility\n\nStripe is excellent for card-based transactions and supports Apple/Google Pay. However, it lacks native support for DuitNow or local e-wallets in Malaysia.\n\nPayPal supports its own wallet and card payments, and allows local bank withdrawals. But like Stripe, it doesnât offer built-in support for Malaysian BNPL or QR payments.\n\nFor businesses in Malaysia, this gap can limit how easily your customers pay, especially if they prefer local methods like FPX or DuitNow QR. Local-focused providers like Billplz help close that gap by supporting the payment methods Malaysians already use without needing to patch together extra tools.\n\n#### Stripe vs PayPal for international payments\n\nStripe is generally stronger for international payments, offering lower crossâborder fees, broader multiâcurrency supp
1ort, and more flexibility for businesses that want to build a customised global checkout. Itâs designed for scale, especially if youâre running subscriptions, SaaS, or highâvolume international eCommerce.\n\nPayPal, on the other hand, remains a practical choice if you want something fast to set up and familiar to customers worldwide. Its global wallet and trusted brand make it easy for buyers to complete payments, even if the overall costs are higher.\n\n### Stripe vs PayPal: Integrations \u0026 development tools\n\nStripe is widely praised for its developer-first approach. With support for webhooks, custom workflows, and advanced billing logic, itâs ideal for SaaS and marketplaces.\n\nPayPal keeps it simple. With plugins for WooCommerce, Shopify, and other platforms, it works well for non-technical users or teams without in-house developers.\n\n_Also read:_ [_Shopify vs WooCommerce (WordPress): An updated comprehensive comparison_](https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison)\n\n### Stripe vs PayPal: Security and compliance\n\nBoth platforms are PCI DSS Level 1 certified, meaning they meet the highest standards for payment security. This reduces compliance burdens for businesses and protects cardholder data.\n\n## Use case comparison\n\nStripe and PayPal each shine in different scenarios, so the right choice depends on how your business operates and who you're serving.\n\n### Stripe vs PayPal for freelancers and remote workers\n\nPayPal is often the go-to for freelancers. Itâs easy to set up and widely recognised by global clients. But its high fees and currency conversion costs can quickly eat into your earnings.\n\nStripe is less common among individual freelancers but works well for agencies or small businesses with the resources to set up custom workflows. Its flexibility makes it ideal if youâre billing clients at scale or handling recurring payments.\n\n### eCommerce businesses\n\nIf you're launching an online store, PayPal makes it easy to get started. It integrates with major platforms like Shopify and WooCommerce, and customers trust the brand at checkout.\n\nStripe, meanwhile, is built for scaling. It offers customisable, branded payment flows and is ideal if youâre expanding internationally or want more control over your checkout experience.\n\n### SaaS and subscription platforms\n\nStripe leads the way here. Its built-in tools for recurring billing, metered pricing, and automation make it a favourite for SaaS businesses. You can customise almost everything if youâve got the dev resources.\n\nPayPal does offer recurring payments, but itâs not as flexible or automated. Itâs best for simpler subscription models.\n\n### Stripe vs PayPal for Malaysian businesses\n\nWhile both platforms support global payments, they donât natively offer Malaysian payment methods. That gap matters, especially if your customers expect to pay using familiar, local channels.\n\nLocal-first providers like Billplz help bridge this, offering Malaysian payment rails and optional PayPal integration. That way, you can serve both local and international customers with one connected setup.\n\n## Which payment gateway is best in Malaysia?\n\n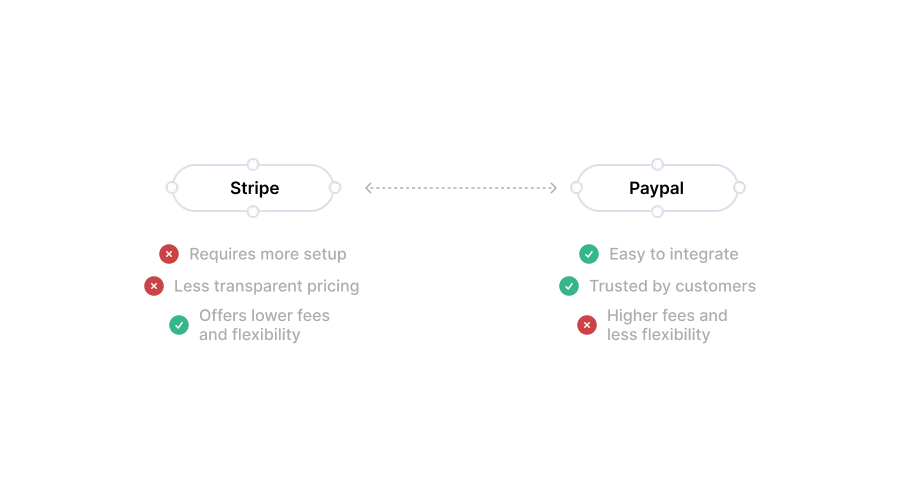\n\nStripe and PayPal are both powerful, but neither is a complete fit for the Malaysian market.\n\n* **Fees**: Stripe may offer slightly lower rates overall, but its FX markups and less transparent structure make it harder to predict. PayPal, while pricier, is easier to understand, especially for low-volume users or one-off transactions.\n* **Ease of Integration**: PayPal is plug-and-play and great for getting started quickly. Stripe takes more setup but offers unmatched flexibility once integrated.\n* **Use Case Fit**: Stripe shines for SaaS, scaling startups, and custom payment flows. PayPal is ideal for freelancers, small eCommerce, and global client billing.\n* **Customer Preference**: Many Malaysian customers and international clients recognise and trust PayPal, especially at checkout.\n\n## Where does Billplz fit in for Malaysian businesses?\n\n[Billplz](https://main.billplz.com/) bridges what global platforms miss: seamless local payments tailored for Malaysian businesses.\n\nBuilt specifically for Malaysian businesses, it supports FPX, DuitNow QR, major e-wallets like TNG, Boost, and GrabPay, as well as BNPL options. This means your customers can pay the way they prefer, securely and instantly.\n\nWith MYR-native pricing, no currency conversion losses, and fast settlements to local bank accounts, you stay in control of your revenue and cash flow.\n\nBillplz also integrates with PayPal, giving businesses the ability to manage both local and international payments within a single, consolidated dashboard. \n\nWhile Stripe supports global scale and PayPal enables international transactions, Billplz complements them by offering the local infrastru
1cture Malaysian businesses need to operate efficiently.\n\nAlso read:\n\n* [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n* [_Jom Duitnow with Billplz: Solutions for Online Businesses_](https://main.billplz.com/blog/products/duitnow-qr-for-online-businesses)\n* [_BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings_](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz)\n\n---\n\n## FAQ\n\n### Is Stripe better than PayPal?\n\nIt depends. Stripe is better for scalable, tech-forward businesses. PayPal is easier to use and trusted by consumers.\n\n### Can I use Stripe in Malaysia?\n\nYes, Stripe has been available in Malaysia since 2019.\n\n### Is Stripe owned by PayPal?\n\nNo. Stripe and PayPal are entirely separate companies. They are competitors in the global payments space and operate independently.\n\n### Do I need both Stripe and PayPal?\n\nMany businesses use both. Stripe provides flexibility and customisation for backend payment flows, while PayPal offers ease of use and trust with consumers, particularly in markets where PayPal is widely adopted.\n\n### Does Stripe hold your money like PayPal?\n\nStripe typically settles payouts within 5â7 business days and is upfront about its processing timelines. PayPal may hold funds temporarily for risk reviews, especially for new or high-risk accounts.\n\n### Which platform is cheaper for online transactions in 2025?\n\nStripe tends to be cheaper, especially at scale. But exact fees vary by transaction type.\n\n### Does Stripe support local Malaysian payment methods?\n\nStripe supports FPX, Malaysiaâs bank transfer system, allowing customers to pay directly from their local bank accounts. \n\nIn addition, it offers international payment methods such as credit and debit cards (Visa, Mastercard) and digital wallets like Google Pay and Apple Pay, all in Malaysian Ringgit (MYR).\n\n### Does PayPal support Malaysian Ringgit (MYR) transactions?\n\nYes, PayPal supports MYR for both domestic and international transactions. You can hold a MYR balance and send or receive payments in Malaysian Ringgit within supported contexts.\n\n### How do Stripe and PayPal compare in terms of settlement speed?\n\nPayPal typically settles to Malaysian bank accounts within 3â5 business days. Stripe takes slightly longer, usually 5â7 business days. Timing may vary depending on the account and transaction history.  \n\n---\n\n## Conclusion\n\nStripe and PayPal each offer unique strengths for online payments. Stripe is built for flexibility and scale, making it ideal for businesses with technical teams and custom workflows. PayPal, on the other hand, is easy to set up, widely recognised, and trusted by customers around the world.\n\nBut for Malaysian businesses, global tools alone arenât always enough. Local payment preferences play a major role in conversion and customer satisfaction.\n\nBillplz bridges this gap by offering:\n\n* A local-first gateway with support for FPX, DuitNow, BNPL, and major e-wallets\n* Transparent, MYR-based pricing with no FX markups\n* Integrations for a unified local and global payment experience\n\nWith _Billplz_, you can accept payments the way your customers prefer and manage them all from one secure, scalable platform.\n\n_Explore how_ [_**Billplz**_](https://main.billplz.com/) _fits into your payment flow and supports your business growth._\n\nTo learn more about Billplz, read: \n\n* [_SenangPay vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n* [_iPay88 vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [_Billplz vs Stripe: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [_Billplz vs Curlec: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [_Toyyibpay vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]}
1,{"id":417,"documentId":"k7no8rp81m1vpacdi7rqua23","title":"Wise vs PayPal: Which payment gateway should you choose?","slug":"wise-vs-paypal-malaysia-payment-comparison","createdAt":"2025-12-02T04:53:49.867Z","updatedAt":"2026-01-06T01:22:14.942Z","publishedAt":"2026-01-06T01:22:15.006Z","publishDate":"2025-12-02T04:53:49.867Z","cover":{"id":116,"documentId":"oapjugmal617cjvxamr69cki","name":"Hero-Image.webp","alternativeText":"Comparison Wise with Paypal","caption":"Comparison Wise with Paypal","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_cb3b5dbf02.webp","hash":"small_Hero_Image_cb3b5dbf02","mime":"image/webp","name":"small_Hero-Image.webp","path":null,"size":8.22,"width":500,"height":278,"sizeInBytes":8224},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_cb3b5dbf02.webp","hash":"medium_Hero_Image_cb3b5dbf02","mime":"image/webp","name":"medium_Hero-Image.webp","path":null,"size":12.64,"width":750,"height":417,"sizeInBytes":12644},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_cb3b5dbf02.webp","hash":"thumbnail_Hero_Image_cb3b5dbf02","mime":"image/webp","name":"thumbnail_Hero-Image.webp","path":null,"size":3.55,"width":245,"height":136,"sizeInBytes":3550}},"hash":"Hero_Image_cb3b5dbf02","ext":".webp","mime":"image/webp","size":16.39,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_cb3b5dbf02.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-27T01:50:41.884Z","updatedAt":"2025-11-27T02:03:36.551Z","publishedAt":"2025-11-27T01:50:41.884Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":144,"metaTitle":"Wise vs PayPal: Which payment gateway should you choose?","metaDescription":"Compare Wise and PayPal for fees, speed, FX rates, and use cases. Find the right fit for your business and how Billplz supports local payments.\n","metaKeywords":"Wise, PayPal, payment gateway comparison Malaysia, Malaysian payment gateway, FPX payment gateway, Billplz review, Toyyibpay review, payment gateway for SME Malaysia, online payment Malaysia, payment gateway fees Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_cb3b5dbf02.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Wise vs PayPal: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Wise and PayPal for fees, speed, FX rates, and use cases. Find the right fit for your business and how Billplz supports local payments.\n","dateModified":"2026-01-06T01:22:13.312Z","datePublished":"2025-12-02T04:53:49.867Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/wise-vs-paypal-malaysia-payment-comparison","@type":"WebPage"}}},"blocks":[{"id":392,"body":"**Key takeaways:**\n\n* Wise offers lower fees, mid-market exchange rates, and faster international transfers. This is ideal for freelancers and SMEs managing cross-border payments.\n* PayPal is built for online checkout, invoicing, and customer payments, with integrations for platforms like Shopify and WooCommerce.\n* Wise uses real exchange rates with no markup, while PayPal adds a hidden margin of 3â4% on currency conversions.\n* PayPal supports international withdrawals to Malaysian banks, but it can be slower and more costly than Wise.\n* Use Wise for cost-efficient transfers and PayPal for global checkout and client billing. Many businesses benefit from using both.\n* Billplz complements both platforms by offering local payment methods (FPX, DuitNow QR, e-wallets), PayPal integration, and fast MYR bank settlements.\n\n## Introduction\n\nWise and PayPal are two of the most recognised names when it comes to sending and receiving money internationally. While both offer global payment capabilities, they serve very different functions.\n\n* Wise (formerly TransferWise) focuses on international transfers and borderless accounts, offering real exchange rates with low, transparent fees.\n* PayPal is a long-standing online wallet and payment gateway, popular for eCommerce, invoicing, and consumer payments.\n\nThis guide compares Wise and PayPal across key factors like fees, exchange rates, speed, and integrations, so you can choose the one that fits your business best.\n\n## Overview of Wise and PayPal\n\n### What is Wise?\n\n[Wise](https://www.google.com/aclk?sa=L\u0026ai=DChsSEwiOpMOZ1_2QAxVXwzwCHYA0FbwYACICCAEQABoCc2Y\u0026co=1\u0026ase=2\u0026gclid=CjwKCAiAz_DIBhBJEiwAVH2XwKlcwedYU8ef9tuBxgnzZ9xU8L3ohlBQCMnHCe8ka_dttpDAsGW-cBoCXPkQAvD_BwE\u0026cid=CAASZeRowz5aEUKjIOpjxF4C9tXqX-0HUvcl9MaOXuo4yhDAJ8q0sRDV6GhiFzSKvsE3O9MRQ4bWy-wwHfInWWi3HCtFpfuBAtJ-1eIORD0On0nVEcQFv3FthcdjU9eKU5fbN2Syqk-k\u0026cce=2\u0026category=acrcp_v1_32\u0026sig=AOD64_0e5m5XPVyoMtPeMj8hVB9CijgUDQ\u0026q\u0026nis=4\u0026adurl\u0026ved=2ahUKEwi89K-Z1_2QAxWlT2wGHXlmNJUQ0Qx6BAgYEAE) is a global money transfer service known for its transparent fees and mid-market exchange rates. Originally built for individuals, it now serves businesses with features like batch payments, multi-currency accounts, and local bank payouts in 70+ countries.\n\nItâs ideal for Malaysian businesses looking to pay international suppliers, freelancers, or remote teams without inflated exchange rates or hidden charges.\n\n### What is PayPal?\n\n[PayPal](https://www.paypal.com/) is a global digital wallet and payment gateway. It allows users to send, receive, and withdraw funds internationally. For businesses, it offers checkout integrations with platforms like [Shopify and WooCommerce](https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison), making it a top choice for eCommerce sellers.\n\nHowever, PayPal comes with higher fees, including currency conversion markups, transaction fees, and withdrawal charges. All of which can eat into profits for small businesses or freelancers.\n\n## Comparison table: Wise vs PayPal\n\nHere's a side-by-side look at how Wise and PayPal compare across core features, fees, and business suitability for Malaysian users\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eWise\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003ePayPal\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCore service\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDesigned for international bank transfers and multi-currency accounts.\u003c/td\u003e\u003ctd\u003eBuilt as a global wallet and checkout solution for online payments.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eExchange rates\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eUses the real mid-market rate with no hidden markup.\u003c/td\u003e\u003ctd\u003eApplies a markup to exchange rates, increasing overall cost.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTransfer/receive fees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eCharges a low, transparent fee upfrontâno surprises.\u003c/td\u003e\u003ctd\u003eMultiple fees apply, including higher transaction and conversion charges.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupported countries\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eAvailable in over 70 countries with strong coverage for business transfers.\u003c/td\u003e\u003ctd\u003eOperates in 200+ countries with wide consumer and merchant adoption.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment gateway integration\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDoes not offer native checkout or gateway functionality.\u003c/td\u003e\u003ctd\u003eFully integrated checkout options for eCommerce platforms.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCurrency supp
1ort\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eOffers a multi-currency account, including MYR support.\u003c/td\u003e\u003ctd\u003eSupports MYR in select cases but with limitations for international use.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eWithdrawal options\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDirect and fast withdrawals to Malaysian bank accounts.\u003c/td\u003e\u003ctd\u003eWithdrawals to local banks are slower and less transparent.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eIdeal for\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBest for freelancers, B2B transactions, and international payroll.\u003c/td\u003e\u003ctd\u003eSuited for eCommerce, digital invoicing, and consumer-facing payments.\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n_Also read:_ [_Stripe vs PayPal: Which payment gateway should you choose?_](https://main.billplz.com/blog/products/stripe-vs-paypal-which-should-you-choose)\n\n### Wise vs PayPal fees\n\n#### Wise fees\n\nWise charges a small, upfront fee that combines a fixed amount and a percentage of the transaction. There are no hidden charges or exchange rate markups;Â what you see is what you pay.\n\n#### PayPal fees\n\nPayPal fees depend on the transaction type, currency, and country. Sending and receiving money, especially from international clients, can incur multiple charges:\n\n* Transfer fee\n* Currency conversion markup (typically 3â4%)\n* Withdrawal fee\n\nThis can make PayPal more expensive, particularly for freelancers or SMEs receiving international payments.\n\n### Wise vs PayPal exchange rates\n\n#### Wise exchange rates\n\nWise uses the mid-market rate, which is the real exchange rate you see on Google or Reuters, with no hidden markup. Instead of inflating the rate, Wise charges a small, transparent fee shown upfront before you send money. You always know exactly how much your recipient will get.\n\n#### PayPal exchange rates\n\nPayPal adds a markup to its exchange rates, usually between 3% and 4%. This hidden cost reduces the amount you receive in your local currency.\n\n#### Does PayPal or Wise Offer Better Exchange Rates?\n\nPayPal adds a margin to its exchange rate, typically around 3% to 4%. This markup is not always obvious, as itâs built into the rate itself rather than broken out separately. So, you may end up receiving less than expected, even before additional PayPal service fees.\n\n### Wise vs PayPal speed and payment experience\n\nWise is generally faster for international transfers, with payouts arriving in 1â2 business days and clear tracking throughout. It also supports batch payments, making it ideal for payroll or supplier payouts.\n\nPayPal withdrawals to Malaysian banks typically take 3â5 business days. While Instant Transfer is available, it's not always guaranteed and may come with extra fees.\n\n#### Which is faster for international payouts?\n\nFor speed and transparency in international payouts, Wise usually has the edge. PayPal works best for collecting payments via checkout or invoices, even if settlement takes a bit longer.\n\n### Wise vs PayPal safety and security\n\nBoth Wise and PayPal are trusted platforms that prioritise security and regulatory compliance.\n\nWise is licensed by Bank Negara Malaysia as a remittance, money-changing, and e-money issuance business with additional approvals from financial regulators worldwide. Its operations are built for transparency and compliance from the ground up.\n\nPayPal is also regulated by Bank Negara Malaysia as an e-money issuer and follows international standards like PCI DSS to protect cardholder data. It also offers seller protection features, which are especially useful for online merchants.\n\nWhen it comes to customer support, Wise often receives positive feedback for its clarity and responsiveness. PayPalâs support is more varied, given its large global user base and broader range of services.\n\n## Use case scenarios: Wise vs PayPal\n\nHereâs how Wise and PayPal compare across common business scenarios in Malaysia, from freelancers to online sellers and SMEs managing global payments:\n\n### Freelancers in Malaysia\n\nWise is ideal for freelancers who want lower fees, better exchange rates, and fast transfers to local bank accounts. It's transparent, efficient, and well-suited for managing international payments.\n\nPayPal, while costlier, remains a popular option thanks to its global reach. Many clients prefer it, especially in creative and tech industries, making it hard to ignore despite the higher fees.\n\n### eCommerce sellers\n\nPayPal is built for online selling, with ready-to-use integrations for platforms like Shopify and WooCommerce. Itâs a convenient checkout option for customers and comes with invoicing features.\n\nWise isnât meant for eCommerce checkout, but itâs helpful for receiving payouts from global platforms and convert
1ing them to MYR affordably.\n\n### SMEs with international suppliers or payroll\n\nWise works well for cross-border business payments, offering batch transfers, real-time tracking, and competitive rates. Itâs built to handle international B2B flows with ease.\n\nPayPal is better suited for receiving payments than sending them. For supplier payments or payroll, its higher fees make it a less efficient option.\n\n## Which is better for your business: Wise or PayPal?\n\n\n\nBoth Wise and PayPal are strong platforms, but they serve different business needs. The better choice depends on how you get paid and how you move money across borders.\n\n**Choose Wise if:**\n\n* You want to keep costs low and avoid currency markups\n* Youâre a freelancer, SME, or service provider managing cross-border payments\n* You need real exchange rates and fast, direct-to-bank transfers\n\n**Choose PayPal if:**\n\n* You run an eCommerce store and need integrated checkout or invoicing tools\n* Your clients prefer PayPal as a payment method\n* You operate on platforms where PayPal is the default or built-in option\n\nWise is more cost-efficient for global transfers. PayPal offers broader convenience for online payments and customer-facing transactions. Choose what fits your business flow best or use both where needed.\n\n## How do you choose the right platform for your payments?\n\nChoosing between Wise and PayPal depends on your business priorities. Think about how often you handle international payments, which currencies you use, and whether you need tools like checkout or batch transfers.\n\nBut international tools are just one part of the puzzle.\n\nFor Malaysian businesses, having a reliable local payment setup is just as important. Thatâs where [Billplz](https://main.billplz.com/) comes in. It complements your global platforms by supporting local payment methods like [FPX](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide), DuitNow, [BNPL](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz), and e-wallets, all with transparent, MYR-based pricing.\n\nYou also get fast settlements to Malaysian bank accounts and the ability to integrate PayPal for international transactions. That means one platform for both local and global payments, with full visibility and control in a single dashboard.\n\nWhether you're scaling up or just getting started, Billplz brings the local infrastructure to support your global ambitions. Â \n\n---\n\n## FAQ\n\n### Is Wise safe in Malaysia?\n\nYes. Wise is licensed by Bank Negara Malaysia as a provider of remittance, e-money issuance, and money-changing services. It operates under strict compliance and security standards both locally and globally.\n\n### Is PayPal available in Malaysia?\n\nYes. Malaysian users can create PayPal accounts to send, receive, and withdraw funds. However, certain limitations apply, especially when accepting payments in MYR or using it for local transactions.\n\n### Can I use Wise like PayPal?\n\nNot quite. Wise is designed for international transfers and multi-currency account management. PayPal, on the other hand, is built for online payments, invoicing, and eCommerce checkout.\n\n### Is PayPal better or Wise?\n\nIt depends on your use case. Wise offers lower fees and better exchange rates for transfers, while PayPal is more convenient for consumer-facing transactions and online sales.\n\n### Can PayPal transfer to Malaysian banks?\n\nYes. You can withdraw funds from PayPal to your Malaysian bank account. Standard withdrawals usually take 3â5 business days and may come with conversion and withdrawal fees.\n\n### Can Maybank accept PayPal?\n\nYes. PayPal supports withdrawals to local banks like Maybank, provided your account is linked and verified. Youâll receive the funds in MYR, subject to PayPalâs exchange and transfer fees.\n\n### Which is cheaper for international transfers, Wise or PayPal?\n\nWise is generally more cost-effective due to its real mid-market exchange rate and lower, transparent fees. PayPal charges higher fees and includes a hidden markup in its currency conversions.\n\n### Is Wise a payment gateway or a money transfer service?\n\nWise is a money transfer platform. It helps individuals and businesses send, receive, and manage money across borders, but it doesnât offer native checkout or gateway functionality.\n\n### Is Wise better than PayPal for international payments?\n\nYes, if your priority is cost savings and transparency. Wise typically offers lower total fees and more competitive exchange rates than PayPal for cross-border payments.\n\n### Can I use Wise and PayPal together?\n\nAbsolutely. Many businesses use Wise for sending or receiving funds internationally, while using PayPal for customer payments or eCommerce checkout.\n\n### Does PayPal support Malaysian Ringgit?\
1n\nYes, PayPal supports MYR, but usage is limited for international transactions. Currency conversion fees may apply when receiving or withdrawing funds in MYR.\n\n### Can I integrate Wise with WooCommerce?\n\nNo. Wise does not offer native WooCommerce or eCommerce checkout integration. Itâs meant for bank-to-bank transfers, not for direct consumer payments.\n\n### Is Wise a replacement for a business bank account?\n\nNot entirely. Wise offers multi-currency accounts and helps manage international transactions, but it doesnât replace the full functionality of a traditional business bank account.\n\n### Is Billplz better for Malaysian customer payments?\n\nYes. Billplz is purpose-built for Malaysian businesses, offering FPX, DuitNow QR, and e-wallet support with local bank settlement and MYR-based transparent pricing. Itâs a strong complement to global tools like Wise or PayPal.  \n\n---\n\n## Conclusion\n\nWise and PayPal are built for different strengths. Wise excels in affordable, direct international transfers, while PayPal remains a go-to option for online checkout and global customer payments.\n\nBut if you're a Malaysian business that wants to manage both international and local payments efficiently, you donât need to choose just one. \n\nBillplz bridges the gap by offering:\n\n* A local-first payment gateway with FPX, DuitNow, and e-wallet support\n* Seamless PayPal integration for overseas customers\n* Transparent MYR-based pricing and fast bank settlements\n\nWith Billplz, you can streamline your entire payment stack, from cross-border transactions to domestic collections, all in one flexible, business-friendly platform.\n\n_**Explore how**_ [_**Billplz**_](https://main.billplz.com/) _**helps you simplify payments while staying local, secure, and scalable.**_\n\nAlso read:\n\n* [iPay88 vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [Billplz vs Stripe: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [Billplz vs Curlec: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [SenangPay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":477,"documentId":"vdwbw9xw97gql4aq8ed4t9dw","title":"Jom DuitNow with Billplz: Solutions for Online Businesses","slug":"duitnow-qr-for-online-businesses","createdAt":"2025-12-02T04:33:05.609Z","updatedAt":"2026-07-03T13:32:54.508Z","publishedAt":"2026-07-03T13:32:54.668Z","publishDate":"2025-12-02T04:33:05.609Z","cover":{"id":112,"documentId":"h6jv51sc0bwlgy7w1kz8epam","name":"Hero-Image_1.webp","alternativeText":"Billplz with DuitNow","caption":"Billplz with DuitNow","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_1_8e09723a9e.webp","hash":"small_Hero_Image_1_8e09723a9e","mime":"image/webp","name":"small_Hero-Image_1.webp","path":null,"size":7.31,"width":500,"height":278,"sizeInBytes":7306},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_1_8e09723a9e.webp","hash":"medium_Hero_Image_1_8e09723a9e","mime":"image/webp","name":"medium_Hero-Image_1.webp","path":null,"size":11.3,"width":750,"height":417,"sizeInBytes":11304},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_1_8e09723a9e.webp","hash":"thumbnail_Hero_Image_1_8e09723a9e","mime":"image/webp","name":"thumbnail_Hero-Image_1.webp","path":null,"size":3.57,"width":245,"height":136,"sizeInBytes":3572}},"hash":"Hero_Image_1_8e09723a9e","ext":".webp","mime":"image/webp","size":13.69,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_1_8e09723a9e.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-27T01:49:56.048Z","updatedAt":"2025-11-27T02:03:49.357Z","publishedAt":"2025-11-27T01:49:56.049Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44
1:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":204,"metaTitle":"Jom DuitNow with Billplz: Solutions for Online Businesses","metaDescription":"Learn how DuitNow QR works and why it's ideal for online businesses in Malaysia. Accept bank and e-wallet payments easily with Billplz integration.","metaKeywords":"DuitNow QR, payment gateway comparison Malaysia, Malaysian payment gateway, FPX payment gateway, Billplz review, Toyyibpay review, payment gateway for SME Malaysia, online payment Malaysia, payment gateway fees Malaysia","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_1_8e09723a9e.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Jom DuitNow with Billplz: Solutions for Online Businesses","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Learn how DuitNow QR works and why it's ideal for online businesses in Malaysia. Accept bank and e-wallet payments easily with Billplz integration.","dateModified":"2026-07-03T07:58:46.897Z","datePublished":"2025-12-02T04:33:05.609Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/duitnow-qr-for-online-businesses","@type":"WebPage"}}},"blocks":[{"id":452,"body":"**Key takeaways**\n\n* DuitNow QR is Malaysiaâs national QR standard, enabling payments from over 30 banks and e-wallets through a single, unified code.\n* It simplifies payment acceptance for online businesses, removing the need for multiple proprietary QR codes.\n* Customers can pay using any supported banking app or e-wallet, including Maybank, CIMB, TNG, Boost, and more.\n* It offers instant payment confirmation, with same-day or next-day settlement depending on your provider.\n* Transaction fees are lower than traditional card payments, making it a cost-effective solution for businesses of all sizes.\n* Billplz makes DuitNow QR even easier to adopt, offering payment links, real-time tracking, MYR settlement, and support for other methods like FPX, credit cards, and BNPL.\n* Perfect for freelancers, SMEs, and online stores, Billplz helps you serve local customers better and grow without the complexity.\n\n## Introduction\n\nDuitNow QR is Malaysiaâs national QR standard for mobile payments, built to simplify how businesses collect money in an increasingly digital market.\n\nAs Malaysia continues its shift toward cashless payments, online businesses need payment options that customers trust and can use immediately.\n\nDuitNow QR delivers exactly that. With a single QR code, you can accept payments from more than 30 banks and eâwallets without managing multiple systems or appâspecific codes.\n\nIn this guide, weâll break down how DuitNow QR works, why it benefits your business, and how Billplz makes online adoption seamless.\n\n## What is DuitNow QR and how does it work?\n\nDuitNow QR is Malaysiaâs unified QR standard, developed by [Payments Network Malaysia (PayNet)](https://main.billplz.com/blog/insights/paynet-malaysia-payment-network-guide) and regulated by Bank Negara Malaysia (BNM). It ensures full interoperability across banks and e-wallets, so you only need one QR code to accept payments from your customers.\n\nInstead of managing multiple QR codes from different providers, merchants display a single DuitNow QR code. Customers then scan it using any participating bank app or e-wallet to make payments.\n\n### Whatâs the difference between TNG QR and DuitNow QR?\n\nThe TNG QR code is exclusive to Touch 'n Go eWallet, meaning only users of that app can make payments with it.\n\nIn contrast, DuitNow QR is a universal standard. Because TNG is part of the DuitNow network, its users, along with customers from banks like Maybank, CIMB, or e-wallets like Boost, can all scan the same DuitNow QR to pay.\n\nFor businesses, this means one DuitNow QR code is all you need to serve nearly every customer in Malaysia.\n\n## Benefits of DuitNow QR for businesses\n\nFor online businesses in Malaysia, offering seamless, secure, and accessible payment options is key to improving customer experience and boosting conversion. DuitNow QR checks all those boxes and more.\n\n* **Wider customer acceptance**: Accept payments from all major banks and e-wallets, without asking customers to
1switch apps.\n* **Massive reach**: Over 2.6 million acceptance points nationwide, with RM31.1 billion in transaction value (2024).\n* **Lower operating costs**: Fees are generally lower than credit card transactions, helping businesses save on every payment.\n* **Security \u0026 trust**: Backed by Bank Negara and PayNet; meeting high national standards for safety and reliability.\n* **Real-time confirmation**: Payments show up instantly, so you can confirm and fulfil orders without delay.\n* **Easy to deploy online**: Share a single QR or link via web, WhatsApp, or email; no need to build a full checkout system.\n\nWhether you're running a storefront, selling via Instagram, or sending invoices, DuitNow QR makes collecting payments easier for you and your customers.\n\n## How to set up DuitNow QR for your online business?\n\n\n\nGetting started with DuitNow QR is straightforward, and you donât need to build a full checkout system to offer it. Hereâs how to set it up for online payments:\n\n1. **Choose a provider that supports DuitNow QR**: Make sure they offer tools for generating QR codes or payment links, and that they support MYR settlement to Malaysian bank accounts. Local customer support is a plus.\n2. **Register for a merchant account**: After signing up, youâll receive your DuitNow QR code or a payment link, ready to use immediately.\n3. **Add the QR or link to your customer touchpoints**: You can embed it on your checkout page, invoice, or even share it via WhatsApp, Instagram DM, or email. It works just as well for web-based and social-driven businesses.\n4. **Test a payment**: Run a test using a participating bank or e-wallet to ensure the QR code works, and check if your payment appears correctly in the dashboard.\n5. **Settle and track**: Funds will be settled into your Malaysian bank account based on your providerâs schedule. Most dashboards allow you to view payment history, track status, and export reports for reconciliation.\n\n### How to integrate DuitNow QR with your website or store?\n\nAdding DuitNow QR to your online checkout is simpler than you think.\n\n* Place a QR image or âPay Nowâ link on your checkout page where itâs clearly visible and easy to access.\n* Optimise for mobile: Ensure the QR fills the screen or the link opens directly in a supported bank or e-wallet app for smoother payment flow.\n* Use available tools: If your payment provider offers plugins or embed codes, take advantage of them to save time and ensure compatibility.\n* Track transactions properly: Make sure your backend dashboard captures each DuitNow QR transaction with clear references for easy reconciliation.\n\nIntegrating DuitNow QR can reduce friction at checkout, speed up payment confirmation, and meet customer expectations in just a few taps. \n\nWork with a provider that supports MYR settlement and connects with major local e-wallets like Boost, GrabPay, and TNG. Billplz is a reliable option designed to support these local payment needs.\n\n## How Billplz helps online businesses accept DuitNow QR\n\nBillplz helps Malaysian businesses accept payments with ease. It supports [FPX](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide), DuitNow QR, e-wallets, credit cards, and [BNPL](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz), all from one system. Whether you run an online store, freelance, or manage a platform, you get the tools to move fast, stay in control, and serve local customers better.\n\n\n\nWith clear pricing, seamless integrations, and a powerful dashboard, Billplz lets you collect payments, track them in real time, and grow with confidence.\n\n* **Unified payment gateway**: Accept DuitNow QR, FPX, credit cards, and BNPL from the same platform.\n* **QR + link flexibility**: Generate dynamic or static QR codes, or create payment links from your Billplz dashboard or API, perfect for checkout, chat, or email.\n* **Transparent fees \u0026 fast settlement**: Know exactly what youâre paying, with direct MYR settlement to your Malaysian bank account.\n* **All-in-one dashboard**: Track all incoming payments (QR and non-QR) in real-time, with filters and export options.\n* **Compet
1itive pricing**: FPX-based QR transactions are charged a flat fee per payment, ideal for SMEs and growing brands. Current Basic and Standard plan rates are on the [pricing page](https://main.billplz.com/pricing).\n* **Flexible integrations**: Connect Billplz to your website, store, or platform using ready-made integrations and plugins. Explore available options at the [Billplz Integrations page](https://main.billplz.com/integrations).\n\n_Also read:_ [Payment link Malaysia: how to create and use one](https://main.billplz.com/blog/insights/payment-link-malaysia-for-business)\n\n### DuitNow QR settlement times\n\nDuitNow QR offers **instant payment confirmation**. The moment your customer scans and pays, youâll see it reflected in your Billplz dashboard. Settlement to your Malaysian bank account happens on the same day or the next business day, depending on your plan. \n\nThis speed removes any ambiguity around payment status and helps you move quickly from order to delivery, offering a smoother experience than traditional card terminal settlements.  \n\n---\n\n## FAQ\n\n### Is DuitNow QR safe?\n\nYes, itâs safe. DuitNow QR is regulated by Bank Negara Malaysia and runs on PayNetâs secure infrastru
1cture. \n\n### What are the fees for DuitNow QR payments?\n\nFees vary by provider. With Billplz, QR-based FPX payments are charged a flat fee per transaction. Current rates are on the [pricing page](https://main.billplz.com/pricing).\n\n### Does DuitNow QR support e-wallets and bank apps?\n\nAbsolutely. DuitNow QR works with over 40 participating banks and e-wallets (Source: [DuitNow Online Banking/Wallets](https://www.duitnow.my/Online-Banking-Wallets/index.html)), including Maybank, CIMB, TNG eWallet, Boost, GrabPay, and many more.\n\n### How quickly do funds settle when using DuitNow QR?\n\nYouâll typically receive funds by the next business day. Some providers, like Billplz, also offer same-day settlement options depending on your plan.\n\n### Does Maybank have DuitNow QR?\n\nYes. Maybank fully supports DuitNow QR. You can use it to send and receive payments through the MAE app or Maybank2u.\n\n### Can I use DuitNow QR with e-wallets?\n\nYes. Most major Malaysian e-wallets, including Boost, GrabPay, TNG eWallet, and MAE, let users scan and pay via DuitNow QR.\n\n### Is DuitNow QR free to use?\n\nFor customers, yes â thereâs no charge to pay using DuitNow QR. Merchants may pay a small transaction fee, depending on their payment provider.\n\n### Does DuitNow have a limit?\n\nYes, but it depends on your bank or e-wallet. Some support transaction limits up to RM50,000, while others may have lower caps. Check with your provider for exact limits.  \n\n---\n\n## Conclusion\n\nDuitNow QR makes it easier and more affordable for online businesses in Malaysia to accept digital payments. With one QR code, you unlock payments from nearly every bank and e-wallet your customers use.\n\nAnd when you connect DuitNow QR to a provider like Billplz, youâre not just simplifying payments, youâre streamlining operations. \n\nFrom MYR-based settlement to instant confirmation and full dashboard tracking, Billplz helps you accept payments the way your customers expect.\n\nSet up your DuitNow QR payments today with [**Billplz**](https://main.billplz.com/pricing) and start collecting from Malaysian customers faster, cheaper, and smarter.","__component":"shared.rich-text"}]},{"id":494,"documentId":"ynambmx4ch84471zf3nmnrhi","title":"Payment link Malaysia: how to create and use one","slug":"payment-link-malaysia-for-business","createdAt":"2025-12-02T03:30:34.909Z","updatedAt":"2026-07-16T05:11:23.242Z","publishedAt":"2026-07-16T05:11:23.388Z","publishDate":"2025-12-02T03:30:34.909Z","cover":{"id":141,"documentId":"a2dx9xvpenwdd8iw0xnxpw2p","name":"260716_02_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260716_02_01_4d8c0febaf.webp","hash":"small_260716_02_01_4d8c0febaf","mime":"image/webp","name":"small_260716_02_01.webp","path":null,"size":8.9,"width":500,"height":278,"sizeInBytes":8898},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260716_02_01_4d8c0febaf.webp","hash":"medium_260716_02_01_4d8c0febaf","mime":"image/webp","name":"medium_260716_02_01.webp","path":null,"size":14.39,"width":750,"height":417,"sizeInBytes":14394},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260716_02_01_4d8c0febaf.webp","hash":"thumbnail_260716_02_01_4d8c0febaf","mime":"image/webp","name":"thumbnail_260716_02_01.webp","path":null,"size":3.75,"width":245,"height":136,"sizeInBytes":3754}},"hash":"260716_02_01_4d8c0febaf","ext":".webp","mime":"image/webp","size":21.53,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_02_01_4d8c0febaf.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-16T05:10:49.194Z","updatedAt":"2026-07-16T05:10:49.194Z","publishedAt":"2026-07-16T05:10:49.194Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44
1:14.090Z","slug":"insights"},"seo_meta_tag":{"id":221,"metaTitle":"Payment link Malaysia: how to create and use one","metaDescription":"Get paid through WhatsApp, Instagram, or email with a payment link: what it is, how to create one with Billplz, and what it costs Malaysian businesses.","metaKeywords":"payment link Malaysia, payment link, create payment link, how to create payment link, WhatsApp payment link, payment link for business, Billplz payment link, Catalog Payment Form","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_02_01_4d8c0febaf.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Payment link Malaysia: how to create and use one","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Get paid through WhatsApp, Instagram, or email with a payment link: what it is, how to create one with Billplz, and what it costs Malaysian businesses.","dateModified":"2026-07-16T05:11:22.024Z","datePublished":"2025-12-02T03:30:34.909Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/payment-link-malaysia-for-business","@type":"WebPage"}}},"blocks":[{"id":469,"body":"**Key takeaways:**\n\n* A payment link is a secure URL or QR code that lets customers pay without a website or POS system.\n* It works well for Malaysian businesses collecting payments via WhatsApp, Instagram, email, or SMS.\n* Top features to look for include local method support, branding options, security, and real-time reporting.\n* Payment links help improve cash flow and reduce reliance on physical infrastructure or complex eCommerce setups.\n* Most providers charge per transaction with no monthly fees, ideal for SMEs and seasonal sellers.\n* Billplz supports both no-code and API-based payment links, with trusted local options like FPX, DuitNow QR, and e-wallets.\n\n## Introduction\n\nFor many Malaysian businesses, getting paid is as simple as sending a link. A payment link is a secure URL that allows customers to make a payment instantly, without needing a website, checkout, or [POS system](https://main.billplz.com/blog/insights/pos-system-malaysia-guide). \n \nFrom social sellers to NGOs, more businesses are turning to payment links to accept FPX, DuitNow QR, and e-wallet payments through WhatsApp, Instagram, or email. \n\nIn this guide, weâll walk through how payment links work, why they matter, and how Billplz helps businesses use them with ease.\n\n## What is a payment link, and how does it work?\n\nA payment link is a unique URL or QR code that directs customers to a secure, hosted checkout page. Once opened, the customer can review the payment details and pay using their preferred methodâtypically FPX, DuitNow QR, or e-wallets in Malaysia.\n\nThe process is simple: the business creates a link with a specific amount and purpose, shares it via messaging apps or email, and the customer completes the payment. The transaction status is updated in real time and tracked through the providerâs dashboard.\n\n### Payment link vs payment gateway\n\nA payment link is a fast, shareable way to get paid, often used by social sellers, freelancers, or businesses without a website. You simply generate a link and send it via WhatsApp, email, or Instagram. The customer clicks, pays, and you're done.\n\nA payment gateway, on the other hand, is the full backend system that powers payments on websites and mobile apps. It requires technical integration and is typically used by larger businesses with custom checkouts or shopping carts.\n\nThink of it this way:\n\n* Payment link = No-code, fast, plug-and-play. Great for direct messaging and quick collections.\n* Payment gateway = Developer-friendly, integrated into your platform or store. Better for high-volume or automated flows.\n\nWhichever path you choose, make sure it supports local methods like FPX, DuitNow QR, and e-wallets, and offers transparent pricing with fast settlement.\n\n_For more information on payment getaways, read:_ \n\n* [_Toyyibpay vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)\n* [_Billplz vs Curlec: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [_Billplz vs Stripe: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [_Senangpay vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n\n## Key features and best practices to look for in payment link solutions\n\nIf you're a Malaysian business planning to collect payments online, hereâs what to look for in a solution thatâs both reliable and ready to scale:\n\n* **Local payment support**: Accept payments via FPX, DuitNow QR, and e-wallets like GrabPay, Boost, and Touch ân Go. All are essential for Malaysian customers. \n Branding and customisation: Create branded checkout pages and personalised URLs to build trust and maintain consistency with your business identity.\n* **Link management tools**: Set expiry dates, control link access, and receive notifications when payments are completed, all from a central dashboard.\n* **Real-time reporting**: Monitor transactions with clear summaries of customer details, payment status, and collection trends.\n* **Security and compliance**: Ensure the solution is PCI DSS compliant and uses SSL encryption to keep customer data safe and secure.\n* **Developer-ready integration**: For businesses with custom systems, API access allows dynamic payment link creation and seamless billing workflows.\n\n## Why do businesses in Malaysia need a payment link?\n\nAs more Malaysians shop, book services, and donate through their phones, businesses are moving toward mobile-first payment experiences. But not every business has a full eCommerce setup, and not every customer wants to check out through a complex site.\n\nPayment links solve this gap. They let you collect payments through the platforms your customers already use. Whether you're sending an invoice or confirming an order, a secure link helps you get paid faster without the need for a website or POS system.\n\nFor many businesses, this also means better cash flow, easier tracking, and fewer manual steps. With real-time dashboards and automated notifications, payment links offer a simple yet powerful way to manage payments day to day.\n\n### What payment methods are supported by payment links in Malaysia?\n\nMost payment link providers in Malaysia support [FPX](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide) and DuitNow QR as standard. Many also offer additional options like e-wallets such as GrabPay, Boost, and Touch 'n Go, along with [Buy Now Pay Later (BNPL) services](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz).\n\nProvi
1ding multiple local payment methods gives customers more flexibility to pay using what they already trust. This helps improve the payment experience and encourages faster completion.\n\n## How can Malaysian businesses create a payment link?\n\n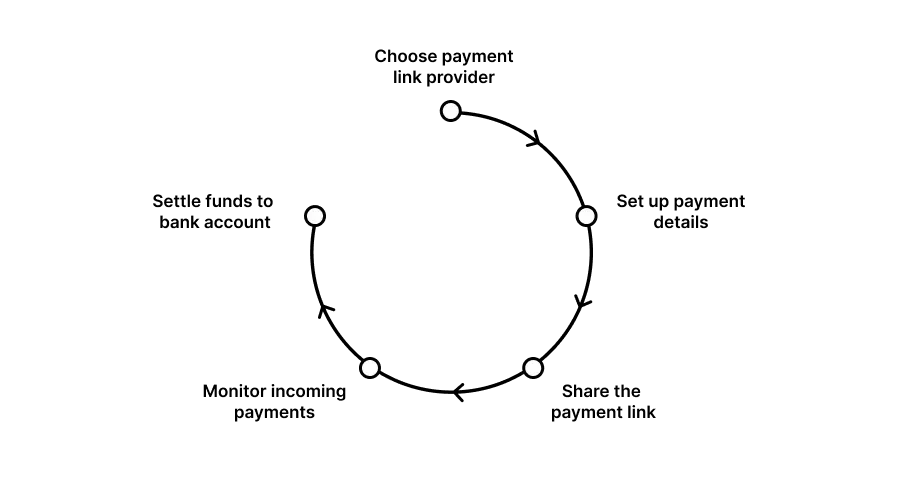\n\nGetting started with payment links is simple. Hereâs a step-by-step guide for local businesses:\n\n**Step 1: Choose a payment link provider** \nSelect a provider that supports Malaysian payment methods like FPX and DuitNow QR. Look for transparent pricing, local settlement, and tools that match your business needs.\n\n**Step 2: Set up your payment details** \nEnter the payment amount, item or service description, and optionally set an expiry date for the link.\n\n**Step 3: Share the payment link** \nSend the link directly to customers through WhatsApp, Instagram, email, or SMS. No website or checkout page is required.\n\n**Step 4: Monitor incoming payments** \nUse the providerâs dashboard to track who has paid, how much, and when. Some systems offer real-time updates.\n\n**Step 5: Settle funds to your bank account** \nOnce payments are received, funds are typically settled to your Malaysian bank account by the next business day.\n\nThis setup works well for SMEs, service providers, NGOs, and any business that values fast, secure collections without heavy infrastructure.\n\n## How to create a payment link with Billplz\n\nThe fastest no-code route is the Catalog Payment Form, Billplz's payment form with a shareable link:\n\n1. **Sign up for Catalog** at [catalog.billplz.com](https://catalog.billplz.com/signup). The free plan includes unlimited forms, and no coding is needed.\n2. **Create your Payment Form.** Click Create Payment Form, then fill in the form details: what the payment is for and the listing option (your amount settings).\n3. **Customize and enable.** Add any extra fields you need, set your thank-you page, and save.\n4. **Share the link.** Send it through WhatsApp, Instagram, email, or SMS, or place it in your bio and captions.\n5. **Track and settle.** Payments appear in your dashboard, and funds settle to your Malaysian bank account.\n\n## How to use payment links for your business?\n\nFrom social sellers to service providers, payment links offer a simple way to collect payments, no website or app needed. Hereâs how businesses in Malaysia are using them every day:\n\n* **Social sellers**: Accept orders directly through Instagram DMs, WhatsApp chats, or Facebook messages without needing a website.\n* **Service providers**: Tutors, freelancers, and consultants can send secure payment links to clients after delivering their services.\n* **Retailers and F\u0026B outlets**: Use payment links for online pre-orders, seasonal promotions, or limited-time offers, especially during peak sales periods.\n* **NGOs and community groups**: Collect donations during fundraising drives, event registrations, or monthly contribution campaigns with simple links.\n\n## Payment link fees and cost considerations in Malaysia\n\nPayment link providers typically charge a flat fee or a small percentage per transaction, often with no monthly charges, making them a good fit for small or seasonal businesses.\n\nBut price isnât the only factor. Itâs worth looking at how fast payments are settled, whether local options like FPX, DuitNow QR, or e-wallets are supported, and how transparent the fee structure is.\n\n[Billplz](https://main.billplz.com/) offers MYR-based pricing with no hidden charges, supporting a full range of local payment methods. Itâs a practical way to manage costs while keeping the checkout experience simple and familiar for your customers.\n\nPayment links created with the Catalog Payment Form follow Catalog's plan pricing, plus per-transaction fees for the payment methods you accept. Current rates are on the [Catalog pricing page](https://catalog.billplz.com/pricing) and the [Billplz pricing page](https://main.billplz.com/pricing).\n\n## How can Billplz help you accept payments with a link?\n\nBillplz gives you three ways to collect with a link, depending on what you sell and how often:\n\n[**Catalog Payment Form**](https://catalog.billplz.com/payment-form) is the easiest way to start: a branded, no-code payment page with a shareable link. Ideal for service providers, social sellers, NGOs, and anyone without a website. Payment links follow [Catalog's plan pricing](https://catalog.billplz.com/pricing), with a free tier to start. \n[**Billplz Collection bills**](https://main.billplz.com/collection) suit invoice-style collection: create a bill for a specific customer and amount, and Billplz sends it by email, SMS, or direct link. Good for consultations, fees, and one-to-one billing. \n[**Catalog Store**](https://catalog.billplz.com/commerce) is the upgrade path when one form is not enough: a full online storefront with products, inventory, and checkout, still with no coding.\n\nFor platforms and custom systems, the Billplz API generates payment links dynamically and redirects customers straight to the payment screen. Every option comes with real-time tracking and local bank settlement.\n\n---\n\n## FAQ\n\n### How to receive money through a payment link?\n\nChoose a trusted provider, set up your payment details like amount and description, then generate the link. Share it via WhatsApp, email, or any channel you use. Once the customer pays, you'll see the update in y
1our dashboard, and the funds will settle into your bank account shortly after.\n\n### How to know if a payment link is safe?\n\nCheck for HTTPS URLs, trusted providers, and official payment pages. Providers like Billplz comply with PCI DSS and use encryption.\n\n### Are payment links free?\n\nCreating a payment link is usually free. Transaction fees apply when a payment is completed. These vary by provider and payment method.\n\n### Can I create my own payment gateway?\n\nBuilding a custom payment gateway requires significant technical resources, ongoing maintenance, and regulatory approvals. For most businesses, itâs simpler and more cost-effective to use a reliable provider like Billplz, which already meets local compliance standards.\n\n### Is payment by link safe?\n\nYes, as long as a secure and verified platform issues the link. Look for encryption, PCI DSS compliance, and SSL protection. These are standard practices for most Malaysian payment providers.\n\n### Are payment links cheaper than traditional payment gateways?\n\nFor many small businesses and occasional sellers, payment links can be more affordable. They often come with lower upfront costs and no monthly fees, but it's still important to compare transaction rates and available features.\n\n### Can I send a payment link via WhatsApp or Instagram?\n\nAbsolutely. This is one of the most popular ways to use payment links in Malaysia, especially for social sellers and service providers. You can drop the link directly into chats, DMs, or captions for quick payments.  \n\n---\n\n## Conclusion\n\nFor many Malaysian businesses, collecting payments should be simple, secure, and accessible, even without a website or POS system. Payment links offer exactly that.\n\nWhether youâre a social seller, NGO, freelancer, or service provider, payment links give you the flexibility to receive payments through channels your customers already use, from WhatsApp to email.\n\nBillplz supports this with local-first solutions, along with real-time tracking, MYR settlement, and secure infrastru
1cture. It's a practical way to streamline how you collect payments while meeting the expectations of local buyers.\n\n_Explore the_ [_Catalog Payment Form_](https://catalog.billplz.com/payment-form) _to simplify your collection process and offer trusted, local payment experiences._","__component":"shared.rich-text"}]},{"id":496,"documentId":"q9po1dfxpg9imeivylgk7grc","title":"Billplz vs Curlec: Which payment gateway should you choose?","slug":"billplz-vs-curlec-payment-gateway-comparison","createdAt":"2025-11-06T06:40:37.124Z","updatedAt":"2026-07-16T05:12:09.280Z","publishedAt":"2026-07-16T05:12:09.419Z","publishDate":"2025-11-06T06:40:37.124Z","cover":{"id":139,"documentId":"brxaqlosnk2xjttiwhbp6oxj","name":"260716_04_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260716_04_01_7dfebd9222.webp","hash":"small_260716_04_01_7dfebd9222","mime":"image/webp","name":"small_260716_04_01.webp","path":null,"size":8.29,"width":500,"height":278,"sizeInBytes":8292},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260716_04_01_7dfebd9222.webp","hash":"medium_260716_04_01_7dfebd9222","mime":"image/webp","name":"medium_260716_04_01.webp","path":null,"size":12.93,"width":750,"height":417,"sizeInBytes":12926},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260716_04_01_7dfebd9222.webp","hash":"thumbnail_260716_04_01_7dfebd9222","mime":"image/webp","name":"thumbnail_260716_04_01.webp","path":null,"size":3.46,"width":245,"height":136,"sizeInBytes":3464}},"hash":"260716_04_01_7dfebd9222","ext":".webp","mime":"image/webp","size":19.13,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_04_01_7dfebd9222.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-16T05:10:22.050Z","updatedAt":"2026-07-16T05:10:22.050Z","publishedAt":"2026-07-16T05:10:22.050Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":223,"metaTitle":"Billplz vs Curlec: Which payment gateway should you choose?","metaDescription":"Compare Billplz and Curlec to find the right payment gateway for your Malaysian business. Discover differences in pricing, features, billing, payout speed \u0026 more.\n","metaKeywords":"Billplz and Curlec, Billplz vs Curlec, Billplz, Curlec, POS in Malaysia","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_04_01_7dfebd9222.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Billplz vs Curlec: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Billplz and Curlec to find the right payment gateway for your Malaysian business. Discover differences in pricing, features, billing, payout speed \u0026 more.\n","dateModified":"2026-07-16T05:12:07.451Z","datePublished":"2025-11-06T06:40:37.124Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison","@type":"WebPage"}}},"blocks":[{"id":471,"body":"**Key takeaways:**\n\n* Billplz is better suited for SMEs looking for cost-effective, local-first payment solutions with simple setup and faster payout (T+1 FPX or real-time via DuitNow).\n* Curlec offers stronger tools for recurring billing and is ideal for SaaS, NGOs, and education platforms managing complex subscriptions and direct debits.\n* Billplz offers flat, transparent pricing with no setup fees on the Basic plan, making it easier for local businesses to forecast costs.\n* Curlec charges percentage-based fees and has an onboarding cost, which may suit businesses with larger average transaction values.\n* Billplz supports Malaysiaâs key payment methods (FPX, DuitNow, e-wallets, BNPL) and integrates easily with Shopify, WooCommerce, and more.\n* For most local-first Malaysian businesses, Billplz delivers a simpler, faster, and more scalable solution without the overhead.\n\n## Introduction\n\nPayment gateways are essential for Malaysian businesses, especially SMEs, eCommerce brands, and businesses with subscription models. They directly affect how fast you get paid, what fees you incur, and how simple it is to scale operations.\n\nIn this guide, we compare two strong local solutions: Billplz and Curlec. While Billplz is known for its low-cost, fast-settlement approach, Curlec (now part of Razorpay) offers a more tech-forward platform focused on recurring payments. \n\nLetâs break down their key differences to help you decide.\n\n## Overview of both platforms\n\n### What is Billplz?\n\n[Billplz](https://main.billplz.com/) is built for Malaysian SMEs, startups, and NGOs that need affordable, efficient ways to collect payments. It focuses on FPX (online banking), real-time transfers, and bulk payouts, making it ideal for local-first businesses.\n\n### What is Curlec?\n\n[Curlec](https://curlec.com/), now part of Razorpay, is a Malaysian payment gateway with strong support for recurring billing. Itâs built for eCommerce businesses and subscription-first models that need automation, a polished checkout experience, and support for direct debit. \n\nWhile powerful, Curlec may require more technical setup.\n\n## What are the key differences between Billplz and Curlec?\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eCurlec\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTarget Users\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMalaysian startups, SMEs, NGOs, and growing teams looking for simple, affordable payments.\u003c/td\u003e\u003ctd\u003eBusinesses with advanced billing needs, recurring revenue, or custom-branded checkout flows.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTransaction Fees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFlat, transparent fees per FPX transaction, depending on plan. See \u003ca href=\"https://main.billplz.com/pricing\"\u003epricing page\u003c/a\u003e for current rates.\u003c/td\u003e\u003ctd\u003ePercentage-based fees for FPX and e-wallets; varies by method and use case.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSetup / Onboarding\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eQuick and easy onboarding with a free Basic plan. No upfront fees required.\u003c/td\u003e\u003ctd\u003eA setup fee applies, with more steps for access to subscription tools.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment Methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eSupports FPX (core), e-wallets, cards, BNPL\u003c/td\u003e\u003ctd\u003eOffers FPX, cards, direct debit, BNPL, and recurring bank debits.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eRecurring Billing\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eSupported via API and plugins. Great for simple subscriptions.\u003c/td\u003e\u003ctd\u003eBuilt-in subscription engine with flexible models, automated retries, and lifecycle tools.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eIntegrations \u0026amp; Tools\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDeveloper-friendly API, plugins, multi-user dashboards, webhooks, and payment links.\u003c/td\u003e\u003ctd\u003eStrong dev tools, dashboard, and compliance modules.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eLocal Fit \u0026amp; Support\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMalaysian-first focus with local support and cash flowâfriendly payout cycles.\u003c/td\u003e\u003ctd\u003eOperates in Malaysia with Razorpayâs global tech stack behind it.\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Billplz vs Curlec: Fee comparison\n\nBillplz offers cost-efficiency with flat-rate FPX fees, especially suited for smaller transactions. Its Free plan allows many businesses to get started without setup fees.\n\nCurlec has a broader fee structure to cover direct debit, recurring billing, and other services. While transparent, its percentage-based fees and setup costs may be more suited to businesses with larger ARPU or recurring models.\n\n_Check the latest rates on the_ [_Billplz pricing_](https://main.billplz.com/pricing) _page._\n\n### Payment features \u0026 local fit\n\n
1Billplz covers Malaysia's most-used payment options: FPX, DuitNow, major e-wallets, BNPL, and card payments. Itâs optimised for real-time FPX and local integration with a simple next-day settlement.\n\nCurlec supports FPX, debit and credit cards, e-wallets, and BNPL. Some of its products also include Shariah-compliant features. Its direct debit and recurring tools are key strengths.\n\n### Subscription \u0026 recurring billing\n\nBillplz supports recurring collections through its API and plugins, making it a solid fit for SMEs with straightforward subscription models. It integrates with platforms like WooCommerce, EasyStore, and others, giving businesses flexibility in how they manage recurring payments.\n\nCurlec is subscription-focused, offering advanced billing models (fixed, usage-based), automated retries, and end-to-end subscription lifecycle tools. Ideal for gyms, SaaS, and education platforms.\n\n### Integrations \u0026 support\n\nBillplz integrates smoothly with platforms like WooCommerce, Shopify, and more. It also supports invoicing, split payments, team dashboards, and pre-built plugins for over 30 local platforms. \n\nDevelopers can tap into REST APIs and real-time webhook notifications to streamline operations and stay in sync.\n\nCurlec provides API-first access, dashboards for monitoring real-time payment activity, and pre-built features for Islamic-compliant collections.\n\n_Read more about_ [_Billplz integrations_](https://main.billplz.com/integrations) _here!_\n\n### Security, compliance \u0026 reliability\n\nBillplz is built for Malaysian businesses from the ground up. It complies with local banking regulations and is PCI DSS certified, so your transactions stay protected with bank-level security. Its infrastructure is designed to be reliable, secure, and well-suited for the daily demands of SMEs and online sellers.\n\nCurlec benefits from Razorpayâs global infrastructure, offering strong uptime, robust encryption, and compliance with international standards. \n\nWhile both platforms are secure, Billplzâs local-first compliance and alignment with Malaysian systems give it a practical edge for businesses focused on operating within Malaysia.\n\n### Settlement \u0026 payout\n\nBillplz provides next-business-day (T+1) settlements for FPX, helping businesses maintain steady cash flow and better financial visibility. Enterprise users can also access real-time payouts through DuitNow Transfer, making it easier to manage disbursements or supplier payments without delays. \n\nIts predictable schedule gives SMEs more control over daily operations and expenses.\n\nCurlec typically settles payments within T+2 business days. While the process takes slightly longer, itâs designed for automation, especially for recurring payments and direct debit models.\n\n## Billplz vs Curlec: Which suits subscriptions better for Malaysian businesses?\n\nIf your business is built on recurring revenue, choosing the right payment gateway for subscriptions can make all the difference.\n\n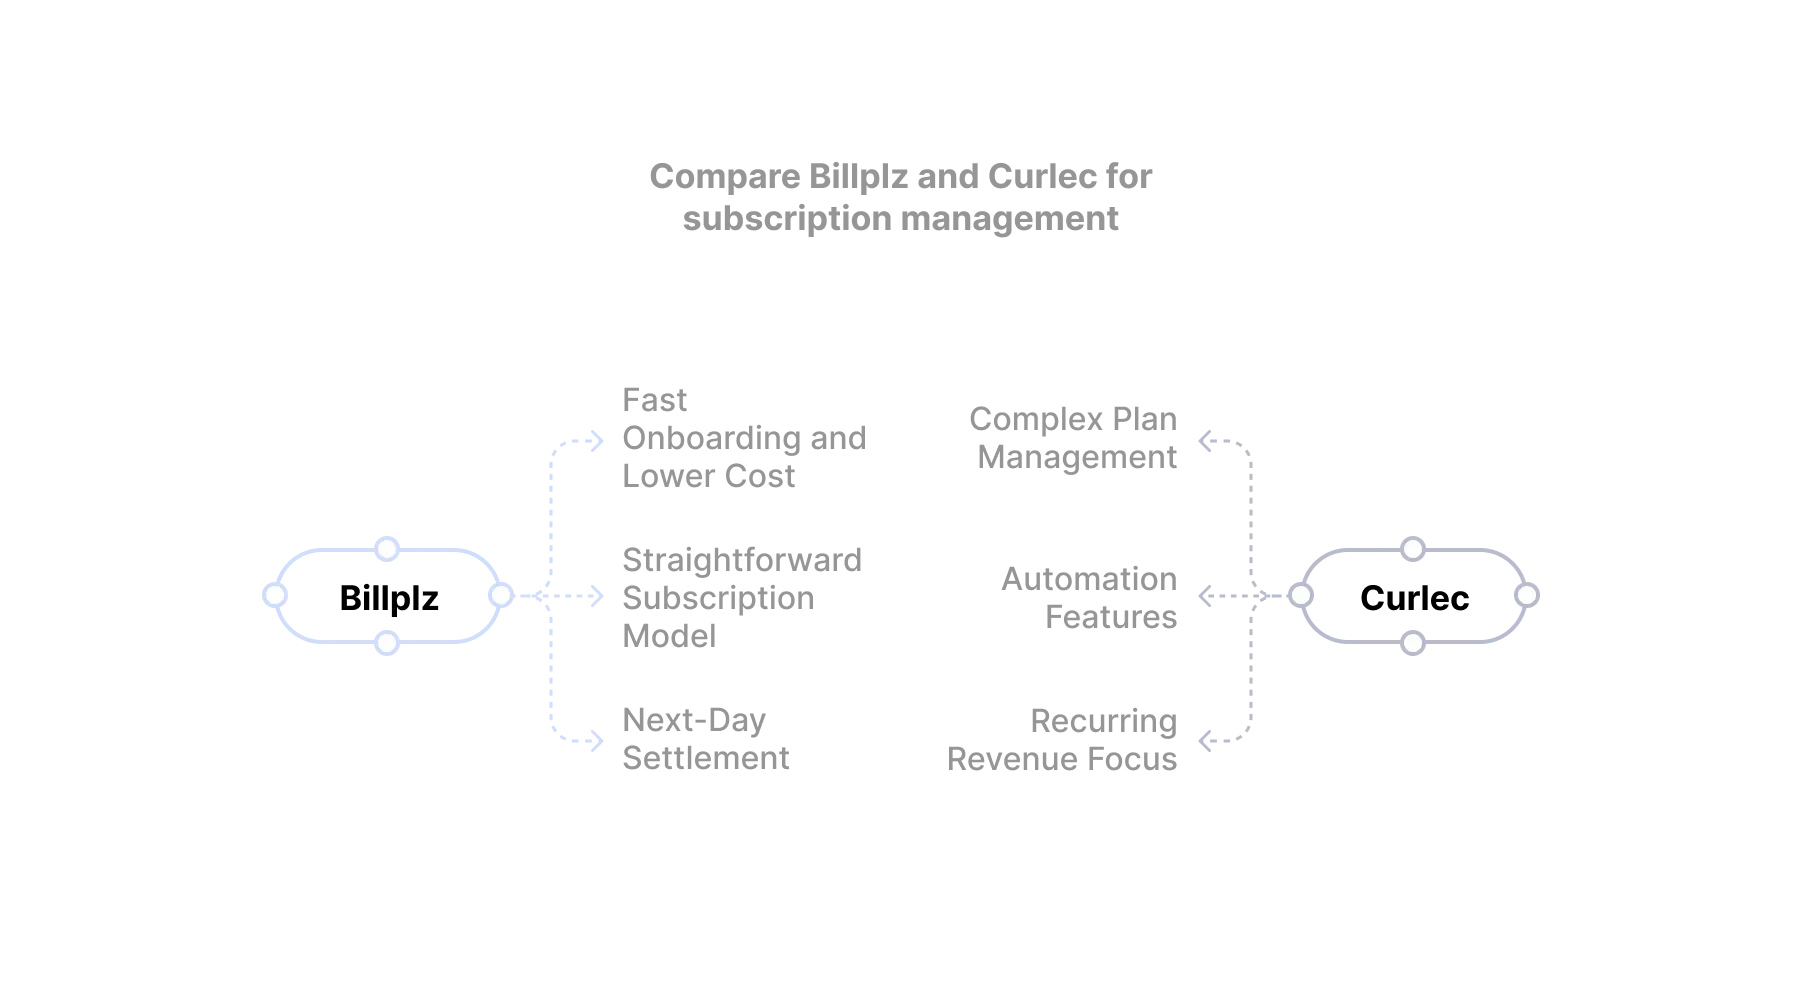\n\n##### Choose Billplz if:\n\n* You want fast onboarding with minimal setup and lower upfront cost.\n* Your subscription model is straightforward and works well with tools like WooCommerce and API integrations.\n* You rely on next-day settlement to maintain a healthy cash flow.\n* You need an easily scalable payment system that grows with your business, without complicated processes or additional fees.\n\n##### Choose Curlec if:\n\n* You manage more complex subscription plans, such as direct debit or tiered recurring billing.\n* You need automation features like smart retry logic and billing cycle control.\n* You're running a SaaS, NGO, or education platform where recurring revenue is central.\n\nBillplz is a strong fit for most Malaysian SMEs with simple recurring needs and local-first growth goals. If your business is built around subscriptions and needs a more advanced billing engine, Curlec brings more control, but often with more setup and cost.\n\n### How does Billplz help Malaysian businesses scale?\n\nBillplz is built to grow with you, from your first few customers to full-scale operations. Its local-first approach, combined with developer tools and transparent pricing, gives Malaysian businesses the flexibility to scale without getting overwhelmed.\n\n* **Transparent, predictable pricing**: No setup or monthly fees on the Basic plan, just straightforward transaction rates that scale with your business.\n* **Fast setup and payouts**: Get started quickly and receive FPX payments as early as the next business day, helping you keep cash flow healthy. _Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)_._\n* **Local payment methods that convert**: Accept FPX, cards, and major e-wallets like TNG, Boost, and GrabPay â all optimised for Malaysian customers.\n* **Built-in scalability tools**: Integrate easily using ready-made plugins for Shopify, WooCommerce, and EasyStore, or tap into Billplzâs robust API and webhooks.\n* **Real-time sync
1with webhooks**: Keep your systems updated with instant notifications. This is perfect for growing teams and automated workflows.\n\nBillplz gives you everything you need to scale with control, clarity, and confidence, without the complexity.\n\n_Also read:_ [_BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings_](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz)_._\n\n---\n\n## FAQ\n\n### Which payment gateway is better for recurring billing?\n\nCurlec is built around subscriptions. Billplz supports recurring billing via API and plugins, ideal for simpler models.\n\n### Are Billplz and Curlec suitable for small businesses?\n\nYes. Billplz is especially SME-friendly with low entry costs and fast setup. Curlec suits businesses with more complex billing needs.\n\n### How do they compare in fees?\n\nBillplz offers flat, transparent per-transaction pricing with no setup fees on the Basic plan. Curlec uses a percentage-based model, which may vary by use case.\n\n### Does Curlec support Islamic finance?\n\nYes. Curlec includes Shariah-compliant features tailored for NGOs and ethical finance use cases.\n\n### Which one has faster payouts?\n\nBillplz offers next-business-day (T+1) FPX settlements and real-time payouts via DuitNow. Curlec typically settles in T+2.\n\n### Can they integrate with eCommerce?\n\nYes. Both Billplz and Curlec support Shopify, WooCommerce, and custom integrations via API. \n_Also read:_ [_Shopify vs WooCommerce (WordPress): An updated, comprehensive comparison_](https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison)_._\n\n### Is Curlec better for subscriptions?\n\nItâs stronger for advanced subscription models. Billplz works well for SMEs with simpler recurring setups and faster payouts.\n\n---\n\n## Conclusion\n\nBoth Billplz and Curlec are trusted Malaysian payment solutions. Your decision depends on your needs. \nBillplz is the go-to for SMEs looking for cost-efficiency, local focus, and fast payouts. Curlec, on the other hand, is best for businesses managing subscriptions, complex billing, and needing automation.\n\nIf fast setup, local support, and clear pricing sound like your kind of fit, [Billplz](https://main.billplz.com/) is ready to support your next stage of growth.\n\nFor more information about Billplz, read:\n\n* [SenangPay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n* [iPay88 vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [Billplz vs Stripe: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [Toyyibpay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":420,"documentId":"k2m31io2hgt4zpfqc81gldws","title":"Billplz vs Stripe: Which payment gateway should you choose?","slug":"billplz-vs-stripe-malaysia-payment-gateway-comparison","createdAt":"2025-11-06T06:35:12.424Z","updatedAt":"2026-04-27T07:43:08.049Z","publishedAt":"2026-04-27T07:43:08.234Z","publishDate":"2025-11-06T06:35:12.424Z","cover":{"id":103,"documentId":"hhna6wf5c4qqd1tpzx2dzbna","name":"Frame 68.webp","alternativeText":null,"caption":null,"width":1802,"height":1002,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_Frame_68_1f80fbc7e4.webp","hash":"large_Frame_68_1f80fbc7e4","mime":"image/webp","name":"large_Frame 68.webp","path":null,"size":9.82,"width":1000,"height":556,"sizeInBytes":9816},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Frame_68_1f80fbc7e4.webp","hash":"small_Frame_68_1f80fbc7e4","mime":"image/webp","name":"small_Frame 68.webp","path":null,"size":4.44,"width":500,"height":278,"sizeInBytes":4444},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Frame_68_1f80fbc7e4.webp","hash":"medium_Frame_68_1f80fbc7e4","mime":"image/webp","name":"medium_Frame 68.webp","path":null,"size":7.02,"width":750,"height":417,"sizeInBytes":7020},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Frame_68_1f80fbc7e4.webp","hash":"thumbnail_Frame_68_1f80fbc7e4","mime":"image/webp","name":"thumbnail_Frame 68.webp","path":null,"size":2,"width":245,"height":136,"sizeInBytes":2002}},"hash":"Frame_68_1f80fbc7e4","ext":".webp","mime":"image/webp","size":18.99,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Frame_68_1f80fbc7e4.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-12T01:56:14.955Z","updatedAt":"2025-11-12T01:56:14.955Z","publishedAt":"2025-11-12T01:56:14.956Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":147,"metaTitle":"Billplz vs Stripe: Which payment gateway should you choose?","metaDescription":"Compare Billplz and Stripe for Malaysian businesses. Discover which payment gateway offers better pricing, payout speed, and local integration for your growth.\n","metaKeywords":"Billplz, Stripe, Billplz vs Stripe, POS Malaysia\n","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Frame_68_1f80fbc7e4.webp","@type":"ImageObject","width":1802,"height":1002},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Billplz vs Stripe: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Compare Billplz and Stripe for Malaysian businesses. Discover which payment gateway offers better pricing, payout speed, and local integration for your growth.\n","dateModified":"2026-04-27T07:43:06.232Z","datePublished":"2025-11-06T06:35:12.424Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison","@type":"WebPage"}}},"blocks":[{"id":395,"body":"**Key Takeaways**\n\n* Billplz offers a local-first setup thatâs easy to start, cost-efficient, and tailored to Malaysian SMEs, NGOs, and online sellers.\n* Stripe excels in international capabilities, supporting multi-currency, global cards, and advanced developer tools.\n* Billplz supports key Malaysian payment methods like FPX, DuitNow QR, and local e-walletsâgiving customers flexible options.\n* Stripe provides deeper customisation for global merchants but has slower onboarding and higher fees for local transactions.\n* Payout speed is faster with Billplz, offering next-business-day or real-time settlements via DuitNow for Enterprise users.\n* For businesses focused on growing within Malaysia, Billplz provides a simpler, faster, and more transparent way to scale.\n\n## Introduction\n\nChoosing the right payment gateway is crucial for Malaysian SMEs, startups, and online sellers. It impacts how fast you get paid, what fees you incur, and how easily your business can grow.\n\nTwo popular options stand out:\n\n* **Billplz**: A Malaysian-first payment gateway built for local needs, fast payouts, and low-cost integration.\n* **Stripe**: A global payment processor with strong developer tools and support for international expansion.\n\nThis guide compares features, pricing, supported methods, and more to help you decide which fits your business better.\n\n## Overview of both platforms\n\n### What is Billplz?\n\n[Billplz](https://main.billplz.com/) is a local payment gateway designed for Malaysian SMEs, startups, NGOs, and social sellers. It's known for simple onboarding, low fees, and full support for local payment methods like FPX, DuitNow QR, and popular e-wallets. \n\nIf your business is focused on growth within Malaysia and wants a low-barrier, high-reward payment solution, Billplz fits the bill.\n\n### What is Stripe?\n\n[Stripe](https://stripe.com/en-my) is a global payment processor that excels in flexibility, developer-friendliness, and international coverage. With built-in tools for subscriptions, multi-currency handling, and custom integrations, it caters to businesses aiming for regional or global scale.\n\n## Key comparison table: Billplz vs Stripe\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eStripe\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTarget Users\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDesigned for Malaysian SMEs, startups, and local-first businesses.\u003c/td\u003e\u003ctd\u003eBuilt for global businesses, high-volume operations, and developer teams.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment Methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eSupports FPX, DuitNow, major e-wallets, cards, and BNPL options.\u003c/td\u003e\u003ctd\u003eOffers cards, FPX (in Malaysia), Apple/Google Pay, wallets, ACH, and more.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSetup Cost\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFree to start with no setup or annual fees under the Basic plan.\u003c/td\u003e\u003ctd\u003eNo setup fees, but onboarding for local features may involve more steps.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTransaction Fees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLow flat FPX fee; predictable for local payments. See \u003ca href=\"https://main.billplz.com/pricing\"\u003epricing page\u003c/a\u003e for current rates.\u003c/td\u003e\u003ctd\u003eTypically ~3% + fixed fee per transaction; varies by payment method.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayout Speed\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNext business day (T+1) for FPX; real-time payouts via DuitNow for Enterprise.\u003c/td\u003e\u003ctd\u003eStandard payouts in 3â7 days; Instant Payouts available in some regions.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eMulti-Currency\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003ePrimarily supports MYR for Malaysian transactions.\u003c/td\u003e\u003ctd\u003eStrong multi-currency capabilities for global sales.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eIntegrations \u0026amp; Tools\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eAPI access, webhooks, and plugins for Shopify, WooCommerce, and EasyStore.\u003c/td\u003e\u003ctd\u003eAdvanced API, recurring billing, fraud tools, and wide platform support.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupport\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLocal Malaysian support with faster, market-specific assistance.\u003c/td\u003e\u003ctd\u003e24/7 global support; local experience may vary depending on region.\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Fees \u0026 pricing\n\nBillplz keeps pricing simple. The basic plan is free to start with no setup or annual fees â you only pay per transaction. FPX payments are charged at a low flat rate, while e-wallet and card payments are available at competitive percentages through partners. A paid plan is available for businesses that need additional features.\n\nStripe uses a percentage-based model with no setup or monthly fees, but transaction fees are typically higher â especially for international and multi-currency payments.\n\nIf your business is focused on local MYR payments, Billplz offers clearer value and easier cost control. It's ideal for Malaysian SMEs looking to scale without pricing surprises.\n\nCheck the latest rates on the [_Billplz pricing_](https://main.billplz.com/pricing) page.\n\n### Payment methods supported\n\nBillplz supports [FPX](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide), DuitNow QR, major e-wallets (TNG, GrabPay, ShopeePay), [BNPL](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz), and local card payments via partners. Itâs built for local usage.\n\nStripe supports credit/debit cards globally, Apple Pay, Google Pay, ACH, and supports FPX in Malaysia. It offers multi-currency and a growing list of local options, but with added complexity.\n\n### Features \u0026 integrations\n\nBillplz offers practical tools designed for fast-growing local businesses. You get auto-invoicing, payment links, and recurring billing features out of the box. It integrates easily with platforms like Shopify, WooCommerce, and EasyStore. \n\nDevelopers can tap into its clean API and webhooks, while finance teams benefit from team dashboards, split payments, and real-time payouts via DuitNow.\n\nStripe, on the other hand, is built for flexibility at scale. It supports advanced use cases like global subscriptions, fraud prevention, and highly custom checkout flows. \n\nIts developer ecosystem is one of the most mature in the industry, making it a favourite for complex integrations and international setups.\n\nIf your focus is local growth with plug-and-play ease, Billplz gets you up and running quickly. For more advanced, multi-market requirements, Stripe provides broader tools with a steeper setup curve.\n\n_Read more about_ [_Billplz integrations_](https://main.billplz.com/integrations) _here._\n\n_Also read:_ [_Shopify vs WooCommerce (WordPress): An updated, comprehensive comparison_](https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison)\n\n### Billplz vs Stripe: Payout speed\n\nBillplz settles FPX payments as early as the next business day, making it ideal for local businesses that rely on steady cash flow. For even faster access, enterprise users can use DuitNow Transfer to receive real-time payouts.\n\nStripe, on the other hand, typically takes between 3 to 7 days for standard payouts. The first payout can take even longer, up to 7 to 14 days, especially for new accounts going through the verification process. \n\nWhile Stripe does offer Instant Payouts, availability is limited by country and comes with an extra fee.\n\n### Customer support \u0026 local presence\n\nBillplz provides Malaysian-based support, offering quick and localised assistance that fits the needs of SMEs and growing businesses. The team understands local payment contexts, making troubleshooting and setup smoother for Malaysian users.\n\nStripe offers 24/7 global support along with extensive documentation and an active developer community. However, its local presence and on-ground responsiveness in Malaysia can vary.\n\nFor businesses that value direct, local support and faster resolution, Billplz provides a more hands-on experience.\n\n## Which payment gateway is best in Malaysia?\n\n\n\n##### Cho
1ose Billplz if:\n\n* You're a Malaysian SME, NGO, or online seller.\n* You want transparent pricing and local payment coverage.\n* You need fast onboarding and predictable cash flow.\n\n##### Choose Stripe if:\n\n* You're expanding globally or handling international customers.\n* You need multi-currency support and deep integration options.\n* Youâre building complex, custom payment flows.\n\nBillplz is a better fit if you're focused on growing locally. It simplifies payments, keeps costs low, and supports your business as it scales. With local methods like FPX and DuitNow, plus fast onboarding and transparent pricing, itâs a practical choice for Malaysian SMEs.\n\n## How scalable is Billplz?\n\nBillplz is built to support Malaysian businesses as they grow, from first transactions to full-scale operations. It offers:\n\n* **Transparent pricing**: No setup or monthly fees. Just straightforward, per-transaction costs.\n* **Fast onboarding**: Accept FPX payments in just a few days. _Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide).\n* **Built-in tools**: Access to invoicing, bulk disbursements, webhooks, and developer-friendly APIs.\n* **Easy integrations**: Works seamlessly with WooCommerce, Shopify, and more.\n* **Local-first foundation**: Designed for Malaysian banks, MYR settlements, and compliance needs.\n\nWhether youâre running an online store, NGO, or SME, Billplz gives you the flexibility, control, and cost-efficiency to scale with confidence.\n\n---\n\n## FAQ\n\n### Is Billplz safe to use?\n\nYes. Billplz complies with Malaysian financial regulations and is trusted by thousands of SMEs, NGOs, and digital platforms across the country.\n\n### Is Stripe allowed in Malaysia?\n\nYes. Stripe supports Malaysian businesses and enables FPX, card payments, and more once local verification is complete.\n\n### Is Billplz free to start?\n\nYes. The Basic plan has no setup or annual fee. You pay per transaction.\n\n### Which has better payout speed?\n\nBillplz offers faster FPX and real-time DuitNow payouts. Stripe is slower unless you opt for Instant Payouts.\n\n### Does Billplz support local e-wallets better than Stripe?\n\nYes. Billplz integrates directly with Malaysian wallets like GrabPay and TNG.\n\n### Which gateway is easier to integrate?\n\nBillplz is simpler for local platforms. Stripe offers deeper customisation for global tools.\n\n### Are there hidden fees?\n\nBillplz has no hidden setup or annual fees in the Basic plan. Stripe is transparent but may incur higher costs for international or card-based transactions.\n\n---\n\n## Conclusion\n\nBillplz and Stripe both offer reliable ways to collect payments online, but they serve different needs. Billplz is a strong fit for Malaysian SMEs that want fast setup, low fees, and seamless support for local payment methods.\n\nStripe suits businesses operating at a global scale with more complex infrastructure and multi-currency needs. \n\nFor most brands focused on the Malaysian market, [Billplz](https://main.billplz.com/) delivers better cash flow, simpler integration, and a clearer path to growth.\n\nFor more information about Billplz, read:\n\n* [SenangPay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n* [Billplz vs Curlec: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n* [iPay88 vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [Toyyibpay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":432,"documentId":"vbu653r4eurqjws78bp1q2jw","title":"Billplz vs iPay88: Which payment gateway should you choose?","slug":"billplz-vs-ipay88-payment-gateway-malaysia","createdAt":"2025-11-06T03:39:46.736Z","updatedAt":"2026-07-03T08:16:07.779Z","publishedAt":"2026-07-03T08:16:07.932Z","publishDate":"2025-11-06T03:39:46.736Z","cover":{"id":104,"documentId":"r6xol7x3wichba7mq4nked8s","name":"Hero Image copy.webp","alternativeText":null,"caption":null,"width":1802,"height":1002,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_Hero_Image_copy_5e91efa840.webp","hash":"large_Hero_Image_copy_5e91efa840","mime":"image/webp","name":"large_Hero Image copy.webp","path":null,"size":14.95,"width":1000,"height":556,"sizeInBytes":14954},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_copy_5e91efa840.webp","hash":"small_Hero_Image_copy_5e91efa840","mime":"image/webp","name":"small_Hero Image copy.webp","path":null,"size":6.85,"width":500,"height":278,"sizeInBytes":6846},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_copy_5e91efa840.webp","hash":"medium_Hero_Image_copy_5e91efa840","mime":"image/webp","name":"medium_Hero Image copy.webp","path":null,"size":11.02,"width":750,"height":417,"sizeInBytes":11016},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_copy_5e91efa840.webp","hash":"thumbnail_Hero_Image_copy_5e91efa840","mime":"image/webp","name":"thumbnail_Hero Image copy.webp","path":null,"size":3.13,"width":245,"height":136,"sizeInBytes":3126}},"hash":"Hero_Image_copy_5e91efa840","ext":".webp","mime":"image/webp","size":30.19,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_copy_5e91efa840.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-12T01:57:30.198Z","updatedAt":"2025-11-12T01:57:30.198Z","publishedAt":"2025-11-12T01:57:30.199Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":159,"metaTitle":"Billplz vs iPay88: Which payment gateway should you choose?","metaDescription":"Comparing Billplz and iPay88? Discover which Malaysian payment gateway fits your business from pricing and payment methods to features, integrations, and growth.\n","metaKeywords":"Billplz and iPay88, Billplz, iPay88, malaysia payment gateway","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_copy_5e91efa840.webp","@type":"ImageObject","width":1802,"height":1002},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Billplz vs iPay88: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Comparing Billplz and iPay88? Discover which Malaysian payment gateway fits your business from pricing and payment methods to features, integrations, and growth.\n","dateModified":"2026-04-27T07:35:53.302Z","datePublished":"2025-11-06T03:39:46.736Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia","@type":"WebPage"}}},"blocks":[{"id":407,"body":"**Key takeaways:**\n\n* Billplz offers a faster, lower-cost entry point for Malaysian SMEs and startups, with no setup or annual fees in its basic plan.\n* iPay88 provides broader payment options (including multi-currency and BNPL) suited for larger or regionally expanding businesses.\n* Billplz supports scalability with features like FPX real-time settlement, APIs, and integrations with Shopify, WooCommerce, and EasyStore.\n* iPay88 excels in complex infrastructure, offering advanced features like fraud tools, subscription billing, and cross-border support.\n* For businesses focused on local growth, Billplzâs transparent pricing, ease of setup, and Malaysian-first support offer strong long-term value.\n* Choosing the right gateway depends on your priorities. Go with Billplz for simplicity and local scale.\n\n## Introduction\n\nPayment gateways play a crucial role for SMEs, startups, and online sellers in Malaysia. They donât just move money; they support business growth, impact customer trust, and affect operational flow.\n\nTwo well-known names in Malaysia are iPay88 and Billplz:\n\n* **iPay88**: A veteran provider with comprehensive payment support and infrastructure for high-volume merchants.  \n* **Billplz**: A newer platform focused on local businesses, transparency, and scale-readiness.\n\nThis guide compares both solutions across fees, features, integrations, and scalability to help you choose the better fit.\n\n## Overview of both platforms\n\n### What is Billplz?\n\n[Billplz](https://main.billplz.com/) is a homegrown payment gateway built for Malaysian businesses of all sizes. Billplz focuses on FPX as its core service, which keeps things simple and cost-effective.  \n\nYou can also add on e-wallets and card payments through partners. Itâs built to help growing businesses manage payments smoothly while staying in control as things scale up.\n\n### What is iPay88?\n\n[iPay88](https://www.ipay88.com/) launched in 2006 and quickly became a major player in Malaysia and Southeast Asia. It supports a wide range of payment options, including credit and debit cards, e-wallets, Buy Now Pay Later (BNPL), and multi-currency processing.\n\nBuilt for volume and expansion, it is often used by larger merchants or businesses looking to sell across borders.\n\n## Key comparison table: Billplz vs iPay88\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eiPay88\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTarget Users\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eDesigned for startups and SMEs that want a fast, straightforward setup with low entry costs.\u003c/td\u003e\u003ctd\u003eSuited for mid to large businesses expanding regionally or managing complex operations.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment Methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFocuses on FPX as its core service, with cards, e-wallets, and BNPL available.\u003c/td\u003e\u003ctd\u003eSupports FPX, cards, e-wallets, BNPL, and multi-currency transactions for wider regional coverage.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePricing / Fees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFlat FPX rates with no setup or annual fees in the basic plan.\u003c/td\u003e\u003ctd\u003eSetup and annual fees apply, with percentage-based charges that vary by volume and payment type.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSettlement Time\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX payments settle the next business day, with real-time options for enterprise users.\u003c/td\u003e\u003ctd\u003eSettlement time varies and may take longer depending on payment method and volume.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeatures \u0026amp; Integrations\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eIncludes API, webhooks, team dashboards, and plugins.\u003c/td\u003e\u003ctd\u003eOffers subscriptions, analytics, fraud management, and multi-channel support.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eScalability\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eScales easily for SMEs, providing flexible tools for automation and growth.\u003c/td\u003e\u003ctd\u003eBuilt for high-volume, multi-currency, and cross-border transactions.\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupport \u0026amp; Ecosystem\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eProvides local support and a transparent onboarding process tailored to Malaysian businesses.\u003c/td\u003e\u003ctd\u003eBacked by a long-standing reputation and a broad network of regional merchants.\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Fees \u0026 pricing\n\nBillplz offers a simple, transparent structure. The basic plan has no setup or annual fees â you only pay per transaction. FPX transactions are charged at a low flat rate, while card and e-wallet payments are available through partners at competitive percentages. For businesses that need more features, a paid plan is available with additional tools and support.\n\niPay88 follows a more traditional pricing model, which typically includes setup fees, annual maintenance fees, and percentage-based charges per transaction across online banking, cards, and e-wallets.\n\nFor smaller businesses or startups processing moderate volumes, Billplz tends to offer a more cost-efficient entry point. It's easier to start with and keeps ongoing costs predictable.\n\n_Check the latest rates on the_ [_Billplz pricing_](https://main.billplz.com/pricing) _page._\n\n### Payment methods\n\nBillplz supports FPX as its core, with optional add-ons for cards, DuitNow QR, and major e-wallets. It works well across online stores, invoices, and payment links.\n\niPay88 offers more variety, like FPX, cards (local and international), e-wallets, BNPL, and multi-currency supp
1ort. This is great if you need flexibility or plan to sell regionally.\n\nFor businesses focused on Malaysia, Billplz keeps things simple and efficient. If you're looking for broader coverage and more payment options, iPay88 offers a greater variety. \n\nUltimately, the right choice depends on whether you value straightforward local support or need the flexibility to serve wider markets.\n\n### Features \u0026 integrations\n\nBillplz comes with API access, webhooks, multi-user dashboards, and split payments. It also integrates easily with Shopify, WooCommerce, EasyStore, and more.\n\niPay88 offers advanced tools like subscriptions, fraud detection, multi-currency, and deeper analytics.\n\nIf you need to scale quickly and prefer automation, Billplz offers essential tools without the overhead. For businesses needing deep feature customisation, iPay88 may suit better.\n\n_Read more about_ [_Billplz integrations_](https://main.billplz.com/integrations) _here!_\n\n### Reliability, scalability \u0026 support\n\nBillplz settles FPX payments by the next business day, with real-time payout available for enterprise users. Itâs built for high-volume FPX transactions and offers a stable, local-first infrastru
1cture that works well for growing Malaysian SMEs.\n\niPay88 has served large merchants across Southeast Asia for over a decade. Its system supports high volumes, multi-currency, and cross-border payments.\n\nBoth platforms are reliable. If you're scaling regionally with complex needs, iPay88 is a strong fit. But for local growth with a simpler, more transparent setup, Billplz is the better match.\n\n## Billplz vs iPay88: Which is right for your business?\n\n\n\n##### Choose Billplz if:\n\n* You're a startup, SME, NGO, or side business looking for a low-barrier entry into digital payments.\n* Your focus is mainly on local payments like FPX, DuitNow QR, and e-wallets, with a need for reliable, fast settlement.\n* You prefer flat pricing, simple setup, and tools that grow with you. This includes APIs, payment links, and eCommerce integrations like Shopify or WooCommerce.\n* You want better control over cash flow and the ability to scale without being locked into complex fee structures.\n* You want better control over cash flow and a payment system that scales easily without complex or costly fee structures.\n\n##### Choose iPay88 if:\n\n* You're operating a large or high-volume eCommerce business with international ambitions.\n* You need to offer a broader set of payment methods, including multi-currency cards, BNPL, and a wider range of e-wallets.\n* You're ready to invest in advanced tools like fraud protection, subscription billing, and regional scalability.\n* You require deep customisation, complex settlement flows, or long-term infrastru
1cture to support multiple markets.\n\nBillplz is built for modern Malaysian businesses that want to grow without unnecessary complexity. Its local-first design, flat pricing, and fast setup make it especially suitable for SMEs, startups, NGOs, and online sellers looking for transparency, speed, and flexibility.\n\niPay88 remains a solid option for enterprises with international ambitions and complex payment needs. But for most local businesses aiming to scale efficiently, Billplz offers a clearer, more cost-effective path forward.\n\n### How scalable is Billplz?\n\nBillplz is designed to grow with your business. Hereâs how it supports scalability at every stage:\n\n* Transparent pricing: No setup or annual fee for the basic plan, so you only pay per transaction.\n* Quick start: You can go live with FPX and start accepting payments within days, not weeks. _Read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n* Strong integrations: Supports Shopify, WooCommerce, EasyStore and offers REST APIs and webhooks for custom needs.\n* Growth tools built in: Features like split payments, multiâuser dashboards, and bulk disbursements (Payment Order API) help manage expanding operations.\n* Malaysianâfirst focus: Designed for local regulations (MYR payments), local bank settlement flows, and a payment ecosystem suited to Malaysian businesses.\n\n---\n\n## FAQ\n\n### Is iPay88 a reliable payment gateway?\n\nYes. iPay88 has been around since 2006 and is trusted by many large merchants across Malaysia and Southeast Asia.\n\n### Which payment gateway is best in Malaysia?\n\nIt depends on your business needs. Billplz is ideal for SMEs and startups looking for fast setup, clear pricing, and local payment support. iPay88 is more suited for larger businesses with complex requirements and regional goals.\n\n### How much does iPay88 charge?\n\niPay88 charges a setup fee and an annual maintenance fee, with transaction rates that vary by payment method. Check iPay88's published pricing for current figures.\n\n### Is Billplz free?\n\nYes. Billplz offers a free Basic plan with no setup or annual fee. You only pay a flat fee per FPX transaction; current rates are on the [pricing page](https://main.billplz.com/pricing).\n\n### What payment methods does iPay88 support?\n\niPay88 supports FPX, local and international cards, major e-wallets (TNG, Boost, GrabPay), Buy Now Pay Later (BNPL) options, and multi-currency processing.\n\n### What payment methods does Billplz support?\n\nBillplz supports FPX as its core. Billplz also supports credit/debit cards, e-wallets (like GrabPay, Touch 'n Go, Boost, and ShopeePay), and Buy Now Pay Later (BNPL) services (such as Grab PayLater and Atome). \n\n### Can both integrate with WooCommerce or Shopify?\n\nYes. Both Billplz and iPay88 offer plugins and API options to connect with popular eCommerce platforms like WooCommerce and Shopify.\n\n_Also read:_ [_Shopify vs WooCommerce (WordPress): An updated, comprehensive comparison_](https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison)\n\n---\n\n## Conclusion\n\nBillplz and iPay88 are both reliable payment gateways, but they serve different goals.\n\nBillplz is ideal for businesses that prioritise fast setup, transparent pricing, and local payment methods. It offers scalable tools like FPX, payment links, API access, and eCommerce integrations. This makes it a practical choice for SMEs and startups focused on growing within Malaysia.\n\niPay88 suits larger businesses with complex needs such as multi-currency support, international cards, and advanced features for regional expansion.\n\nIf you're looking for a gateway that grows with your business while keeping things lean and local, [Billplz](https://main.billplz.com/) offers the clarity and flexibility to move forward with confidence.\n\nFor more information about Billplz, read:\n\n* [SenangPay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)\n* [Billplz vs Stripe: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [Billplz vs Curlec: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [Toyyibpay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":429,"documentId":"zd1jup0qx3dt6s5i7luc3qny","title":"Senangpay vs Billplz: Which payment gateway should you choose?","slug":"senangpay-vs-billplz-payment-gateway-comparison","createdAt":"2025-11-06T03:29:53.176Z","updatedAt":"2026-07-03T08:06:37.627Z","publishedAt":"2026-07-03T08:06:37.808Z","publishDate":"2025-11-06T03:29:53.176Z","cover":{"id":105,"documentId":"xa3bqsyi14zd11iwncx6qmp2","name":"Hero Image copy.webp","alternativeText":null,"caption":null,"width":1818,"height":1018,"formats":{"large":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/large_Hero_Image_copy_30bf03aa86.webp","hash":"large_Hero_Image_copy_30bf03aa86","mime":"image/webp","name":"large_Hero Image copy.webp","path":null,"size":17.34,"width":1000,"height":560,"sizeInBytes":17340},"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_Hero_Image_copy_30bf03aa86.webp","hash":"small_Hero_Image_copy_30bf03aa86","mime":"image/webp","name":"small_Hero Image copy.webp","path":null,"size":7.14,"width":500,"height":280,"sizeInBytes":7138},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_Hero_Image_copy_30bf03aa86.webp","hash":"medium_Hero_Image_copy_30bf03aa86","mime":"image/webp","name":"medium_Hero Image copy.webp","path":null,"size":11.91,"width":750,"height":420,"sizeInBytes":11906},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_Hero_Image_copy_30bf03aa86.webp","hash":"thumbnail_Hero_Image_copy_30bf03aa86","mime":"image/webp","name":"thumbnail_Hero Image copy.webp","path":null,"size":2.51,"width":245,"height":137,"sizeInBytes":2510}},"hash":"Hero_Image_copy_30bf03aa86","ext":".webp","mime":"image/webp","size":44.66,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_copy_30bf03aa86.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-11-12T01:58:40.756Z","updatedAt":"2025-11-12T01:58:40.756Z","publishedAt":"2025-11-12T01:58:40.757Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":156,"metaTitle":"Senangpay vs Billplz: Which payment gateway should you choose?","metaDescription":"Compare Billplz vs SenangPay on pricing, features, and support. Find out which Malaysian payment gateway fits your business needs best.\n","metaKeywords":"Billplz vs SenangPay, Billplz, SenangPay","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/Hero_Image_copy_30bf03aa86.webp","@type":"ImageObject","width":1818,"height":1018},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Senangpay vs Billplz: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Compare Billplz vs SenangPay on pricing, features, and support. Find out which Malaysian payment gateway fits your business needs best.\n","dateModified":"2026-01-02T01:07:23.517Z","datePublished":"2025-11-06T03:29:53.176Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison","@type":"WebPage"}}},"blocks":[{"id":404,"body":"**Key takeaways**\n\n* SenangPay offers quick setup and broad payment method coverage, ideal for early-stage businesses and social sellers.\n* Billplz provides scalable infrastructure with full API access, multi-channel support, and transparent pricing, making it better suited for growth.\n* Billplz's Basic plan has no setup or annual fee, with flat FPX transaction rates. Current rates are on the [pricing page](https://main.billplz.com/pricing).\n* SenangPay has a minimum settlement amount and higher transaction-based fees, especially for cards and BNPL.\n* Both platforms support major Malaysian payment methods, including FPX, cards, e-wallets, and BNPL options.\n* Billplz supports more advanced features like webhooks, split payments, and integration with Shopify/WooCommerce â useful for teams ready to automate.\n\n## Introduction\n\nPayment gateways are essential for Malaysian businesses of all sizes, including SMEs, NGOs, and online stores. They provide a secure, convenient way to accept digital payments, especially as Malaysia shifts toward cashless transactions.\n\nTwo popular local options are SenangPay and Billplz. Both support key local payment methods and serve a wide range of business types. However, they differ in their pricing models, scalability, and integration options.\n\nThis guide compares their features, fees, use cases, and support for growing businesses, helping you decide which fits your current needs and long-term plans.\n\n## Overview of both platforms\n\n### What is SenangPay?\n\n[SenangPay](https://senangpay.com/) is a Malaysian payment gateway designed for small businesses. It supports FPX, cards, e-wallets, and BNPL options. Known for its quick setup, it works well for social sellers, startups, and micro-enterprises.\n\n### What is Billplz?\n\n[Billplz](https://main.billplz.com/) is a payment platform built for Malaysian businesses at different growth stages. It offers features such as invoice-to-payment links, FPX support, API integrations, and a free basic plan. \n\nIts strength lies in transparent pricing and channel flexibility, supporting both current needs and future growth.\n\n## Key comparison table: SenangPay vs Billplz\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eSenangPay\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTarget users\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eStartups, micro-businesses, social sellers\u003c/td\u003e\u003ctd\u003eStartups, SMEs, growing businesses\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX, cards, e-wallets, BNPL\u003c/td\u003e\u003ctd\u003eFPX, cards, e-wallets, DuitNow QR, BNPL\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePricing/fees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eAnnual fee applies; fees vary by method\u003c/td\u003e\u003ctd\u003eBasic plan has no setup or annual fee; flat FPX rates \u003ca href=\"https://main.billplz.com/pricing\"\u003esee pricing page\u003c/a\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSettlement / payout time\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX: Next business day; others: twice weekly\u003c/td\u003e\u003ctd\u003eFPX: Next business day; some real-time payouts available\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeatures \u0026amp; integrations\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eRecurring payments, plugins, and basic analytics\u003c/td\u003e\u003ctd\u003eAPI, team dashboard, split payments, recurring payments, webhooks\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eScalability/growth\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eEnterprise plans available\u003c/td\u003e\u003ctd\u003eDesigned for scale with real-time FPX and SME features\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupport \u0026amp; ecosystem\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e24/7 customer support\u003c/td\u003e\u003ctd\u003eFull support across plans, ecosystem for growing businesses\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Fees and pricing\n\nSenangPay charges an annual fee, with FPX, card, and BNPL rates that vary by method and a minimum settlement amount. Check SenangPay's published pricing for current figures.\n\nBillplz offers a Basic plan with
1no setup or annual fees. FPX transactions are charged a flat rate per transaction, and Card and Wallet transactions are processed through partners at a percentage rate. Current rates for every plan are on the [pricing page](https://main.billplz.com/pricing).\n\nThe Standard plan is a paid annual plan with lower FPX rates and a low withdrawal minimum.\n\n_Read more on_ [_Billplz pricing_](https://main.billplz.com/pricing) _here!_\n\n### Payment methods\n\nSenangPay supports FPX, cards, and a broad range of e-wallets, including Touch ân Go, Boost, GrabPay, and ShopeePay. It also offers access to multiple BNPL providers, giving businesses flexibility in how they accept payments.\n\nBillplz also covers a similarly comprehensive set of payment methods. This includes FPX, DuitNow QR, e-wallets, BNPL options, and card payments. \n\nThese methods work across various channels like online stores, invoices, and payment links, so businesses can manage transactions in one place with less manual work.\n\n### Features and integrations\n\nSenangPay focuses on simplicity. It supports recurring billing, standard eCommerce plugins, and one-click payment links, which are especially useful for social sellers and micro-businesses.\n\nBillplz is built for scale. It offers a wider suite of tools, including API access, webhooks, multi-user dashboards, and support for split payments. \n\nBusinesses can also integrate Billplz with Shopify, WooCommerce, or custom platforms, allowing more automation and control as operations grow.\n\n_Read more about_ [_Billplz integrations_](https://main.billplz.com/integrations) _here!_\n\n### Reliability, scalability, and support\n\nSenangPay settles FPX payments by the next business day. Cards and other methods typically settle twice a week. This setup suits businesses with predictable, lower-volume transactions.\n\nBillplz also settles FPX payments by the next business day, with real-time payout options available for enterprise users. Its platform is built to support high-volume FPX flows and maintains a strong uptime record. \n\nFor businesses expecting to grow, Billplz provides a stable, scalable infrastructure with room to evolve.\n\n## Which payment gateway is better for small businesses in Malaysia: SenangPay or Billplz?\n\n\n\n**Choose SenangPay if:**\n\n* You run a small business, side hustle, or are just starting out.\n* You prefer a simple setup with essential features.\n* You mostly sell through social channels or have lower transaction volume.\n\n**Choose Billplz if:**\n\n* You are a small business planning to scale or need better cash flow visibility.\n* You require more flexibility with payment channels and integrations.\n* You want infrastructure that supports growth without adding cost complexity.\n\nWhile both platforms serve small businesses well, Billplz may be the more future-ready choice for teams planning to scale.\n\n## How does Billplz support your growth?\n\nBillplz helps businesses scale by offering clear, flat-fee pricing and tools that grow with your operations. You can get started quickly with FPX and local payment methods. \n\nAs your business expands, you gain access to APIs, dashboard management, and plugin integrations with Shopify, WooCommerce, and more.\n\nFeatures like multi-user access, recurring billing, and real-time FPX payouts help streamline workflows and improve operational efficiency. Whether youâre handling 50 or 5,000 transactions monthly, Billplz is structured to grow with you without adding unnecessary costs.\n\n_Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n\n---\n\n## FAQ\n\n### Does SenangPay require SSM registration to sign up?\n\nYes. SSM registration is generally required to activate a SenangPay merchant account.\n\n### Which payment methods does Billplz support?\n\nBillplz supports FPX, DuitNow, DuitNow QR, e-wallets (TNG, GrabPay, Boost), cards, and BNPL integrations.\n\n### Can SenangPay integrate with WooCommerce or Shopify?\n\nYes, SenangPay provides plugins for both WooCommerce and Shopify.\n\n### Can Billplz integrate with Shopify and WooCommerce Malaysia?\n\nYes. Billplz provides both plugin and API options for Shopify, WooCommerce, and custom setups.\n\n### Which payment gateway has faster settlement for Malaysian merchants: Sen
1angPay or Billplz?\n\nBoth offer next business day FPX settlement, but Billplz supports real-time payouts for enterprise merchants.\n\n### Which payment gateway is better for growing an eCommerce business in Malaysia?\n\nBillplz is more suitable for growing eCommerce businesses due to its API integrations, dashboard features, and scalable plans.\n\n### What are the hidden fees, if any?\n\nBillplz has no setup or annual fees in its basic plan. SenangPay includes annual fees and minimum settlement requirements depending on the package.\n\n### Is Billplz suitable for NGOs/microâbusinesses?\n\nYes. Billplz offers a free basic plan with low per-transaction costs, making it suitable for NGOs, community groups, and small teams.\n\n---\n\n## Conclusion\n\nBoth Billplz and SenangPay are viable payment gateways for businesses in Malaysia.\n\nSenangPay is ideal for small or early-stage businesses that need something simple and ready to go. \n\nBillplz, on the other hand, is a strong choice for businesses planning to scale, offering better control, integration flexibility, and transparent pricing.\n\nChoosing the right gateway depends on your current stage and future plans. For businesses ready to grow with greater control and automation, Billplz provides a reliable path forward.\n\nExplore how [Billplz](https://main.billplz.com/) supports Malaysian SMEs at every stage of growth. \n\nFor more information about Billplz, read:\n\n* [iPay88 vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [Billplz vs Stripe: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [Billplz vs Curlec: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [Toyyibpay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":495,"documentId":"fpllqdeoaookznh00nvwanxc","title":"POS system Malaysia: how to choose one and what it cost","slug":"pos-system-malaysia-guide","createdAt":"2025-11-06T02:39:10.507Z","updatedAt":"2026-07-16T05:11:39.653Z","publishedAt":"2026-07-16T05:11:39.773Z","publishDate":"2025-11-06T02:39:10.507Z","cover":{"id":140,"documentId":"r0cs738nz4dy3r7lr02jq1yp","name":"260716_03_01.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_260716_03_01_78432f1b6f.webp","hash":"small_260716_03_01_78432f1b6f","mime":"image/webp","name":"small_260716_03_01.webp","path":null,"size":8.01,"width":500,"height":278,"sizeInBytes":8010},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_260716_03_01_78432f1b6f.webp","hash":"medium_260716_03_01_78432f1b6f","mime":"image/webp","name":"medium_260716_03_01.webp","path":null,"size":12.62,"width":750,"height":417,"sizeInBytes":12620},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_260716_03_01_78432f1b6f.webp","hash":"thumbnail_260716_03_01_78432f1b6f","mime":"image/webp","name":"thumbnail_260716_03_01.webp","path":null,"size":3.32,"width":245,"height":136,"sizeInBytes":3322}},"hash":"260716_03_01_78432f1b6f","ext":".webp","mime":"image/webp","size":17.73,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_03_01_78432f1b6f.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2026-07-16T05:10:37.895Z","updatedAt":"2026-07-16T05:10:37.895Z","publishedAt":"2026-07-16T05:10:37.895Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":222,"metaTitle":"POS system Malaysia: how to choose one and what it cost","metaDescription":"Compare Malaysian POS systems by type, features, and price (StoreHub, Slurp, iCHEF and more), and see how to take local payments alongside your POS.","metaKeywords":"PO
1S system in Malaysia","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/260716_03_01_78432f1b6f.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"POS system Malaysia: how to choose one and what it cost","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Compare Malaysian POS systems by type, features, and price (StoreHub, Slurp, iCHEF and more), and see how to take local payments alongside your POS.","dateModified":"2026-07-16T05:11:38.290Z","datePublished":"2025-11-06T02:39:10.507Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/pos-system-malaysia-guide","@type":"WebPage"}}},"blocks":[{"id":470,"body":"**Key takeaways:** \n\n* POS systems help businesses manage sales, inventory, and customer data in one place.\n* Choose a POS that supports Malaysian payment methods like FPX, DuitNow QR, and Wallet payments.\n* Different types of POS systems suit different needs, such as retail, cafes, restaurants, and mobile setups.\n* Important features include inventory tracking, payment options, CRM tools, cloud access, and offline mode.\n* Start by identifying your business type, payment needs, and integration requirements before comparing options.\n* Industry use cases show how POS systems improve efficiency across sectors like F\u0026B, retail, and eCommerce.\n* Billplz handles online collections and QR payments alongside your POS; in-person card payments run through your POS provider's terminal.\n\n## Introduction\n\nManaging payments, tracking inventory, and maintaining customer records used to be done separately. \n\nToday, Point-of-Sale (POS) systems bring all of that into one place. \n\nWhether you're running a kedai runcit, a retail outlet, or a fast-growing cafe, choosing the right POS system can simplify your operations and help your business scale.\n\nLetâs understand what POS systems are, why they matter in the Malaysian context, how to evaluate one, and where Billplz fits into your payment ecosystem.\n\n## What is a POS system, and how does it work?\n\nA POS system is the technology businesses use to complete sales transactions. It typically includes:\n\n* **Hardware**: Terminal, receipt printer, barcode scanner, cash drawer.\n* **Software**: Interface for processing sales, updating inventory, and managing reports.\n\nWhen a customer makes a purchase, the POS system records the sale, processes the payment, deducts inventory, and updates reports. \n\nMost in-person payments run through the POS provider's own terminal or QR integration, while online payment gateways handle your web and social sales separately.\n\n## Why do businesses in Malaysia need a POS system?\n\nAs Malaysia continues to move toward digitalisation and cashless transactions, POS systems offer several essential benefits:\n\n* **Real-time tracking**: Monitor sales and stock levels as they happen.\n* **Multiple payment support**: Accept [FPX](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide), e-wallets, credit cards, and QR payments.\n* **Simplified reporting**: Generate tax-ready sales and expense reports.\n* **Improved customer experience**: Speed up checkout and offer more payment options.\n\n## Types of POS systems\n\n\n\nChoosing the right POS setup starts with understanding the different types:\n\n* **Traditional POS**: Installed on-site using dedicated hardware. Common in large retail.\n* **Cloud-based POS**: Accessible through browsers or apps; suitable for businesses with online and offline operations.\n* **Mobile POS (mPOS)**: Tablet or smartphone-based systems; great for stalls, pop-ups, or food trucks.\n* **Self-service POS**: Kiosks and QR-based ordering; popular in cafes and quick-service restaurants.\n\n## Named POS options in Malaysia and what they cost\n\nPublished pricing as listed on each provider's website on 3 July 2026. Plans change, so confirm on the provider's page before deciding.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003ePOS system\u003c/td\u003e\u003ctd\u003eBest for\u003c/td\u003e\u003ctd\u003ePublished pricing (as of July 2026)\u003c/td\u003e\u003ctd\u003ePayments supported\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://www.storehub.com/my/pricing\"\u003eStoreHub\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eRetail and F\u0026amp;B\u003c/td\u003e\u003ctd\u003eFrom MYR 122/month (Starter) to MYR 471/month (Pro); hardware sold separately\u003c/td\u003e\u003ctd\u003eIntegrated card payments; confirm QR and Wallet options with the provider\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://getslurp.com/pricing/\"\u003eSlurp!\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eRestaurants and cafes\u003c/td\u003e\u003ctd\u003eOne-time packages from MYR 1,290 (Snack) to MYR 6,490 (Feast)\u003c/td\u003e\u003ctd\u003eIntegrated Maybank QR and Touch 'n Go on higher tiers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://www.ichefpos.com/en-my/pricing\"\u003eiCHEF\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eF\u0026amp;B, iPad-based\u003c/td\u003e\u003ctd\u003eMYR 119/month (Lite) or MYR 229/month (Unlimited); extra device MYR 75/month\u003c/td\u003e\u003ctd\u003eNot published; GrabFood, foodpanda, and Xero connections on Unlimited\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://www.epos.com/my/epos360/\"\u003eEPOS360\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eMicro and small retail\u003c/td\u003e\u003ctd\u003eFrom MYR 39/month plus device\u003c/td\u003e\u003ctd\u003eDuitNow QR (static and dynamic), Touch 'n Go eWallet; card payments rolling out\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://loyverse.com/pricing\"\u003eLoyverse\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eSmall retail and F\u0026amp;B on a budget\u003c/td\u003e\u003ctd\u003eFree core app; paid add-ons priced in USD\u003c/td\u003e\u003ctd\u003eCard brands vary by country; no Malaysia-specific list published\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://qashier.com/my/\"\u003eQashier\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eRetail and F\u0026amp;B\u003c/td\u003e\u003ctd\u003eSee qashier.com for current plans\u003c/td\u003e\u003ctd\u003eTerminal advertises cards, DuitNow QR, and major Wallet payments\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003ca href=\"https://www.xilnex.com/\"\u003eXilnex\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eRetail and F\u0026amp;B, multi-outlet\u003c/td\u003e\u003ctd\u003ePricing on request\u003c/td\u003e\u003ctd\u003eNot published\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## What are the key features to look for in a POS system?\n\nFrom payments to inventory tracking, hereâs what to look for in a POS system that fits your business.\n\n* **Payment integration**: Must support local methods like FPX, DuitNow QR, e-wallets, and Billplz.\n* _**Inventory management**_: Auto-deducts stock, notifies of low inventory.\n* **Reporting \u0026 anal
1ytics**: View sales trends, taxes, and performance in dashboards.\n* **Customer management (CRM)**: Loyalty programs and purchase history tracking.\n* **Multi-outlet support**: Centralised view across multiple branches.\n* **Cloud storage**: Access data anytime, anywhere.\n* **Offline mode**: Keep operations running even during internet outages.\n\n## How to choose the right POS system for your business?\n\nFor Malaysian businesses, choosing a POS system means balancing features, cost, and local payment integration. Hereâs a step-by-step approach to help you make a confident, practical decision:\n\n* **Step 1: Identify your business type**: The right features depend on what you do. Restaurants may need table management and kitchen displays, while retail stores often prioritise barcode scanning and inventory control.\n* **Step 2: Decide on your payment ecosystem**: Make sure the POS supports local payment methods like FPX, DuitNow QR, and major e-wallets. For seamless transactions, look for integration with trusted gateways.\n* **Step 3: Evaluate integration needs**: Consider what tools you already use. A good POS should connect easily with platforms like Shopify, WooCommerce, and your accounting software to streamline operations.\n* **Step 4: Compare costs**: Understand whether you're paying a one-time license or a monthly subscription. Donât forget to factor in setup fees, future upgrades, and support services.\n* **Step 5: Consider scalability and after-sales support**: As your business grows, your POS should grow with you. Choose a provider that offers reliable after-sales support and flexibility to add more features or outlets over time.\n\n## POS system examples and use cases by industry\n\n### POS system for restaurants\n\nRestaurants often require a full-service POS that can handle both front-of-house and kitchen operations.\n\n* Manage table reservations, kitchen orders, and bill splitting efficiently to reduce errors and wait times.\n* Integrate with QR ordering systems and food delivery platforms like GrabFood or Foodpanda, allowing customers to place orders directly from their smartphones.\n* Track menu items, customise modifiers (like âno onionsâ), and coordinate between the service floor and the kitchen seamlessly.\n* Some systems even provide real-time kitchen performance analytics to help optimise prep time and reduce food waste.\n\n### POS system for retail\n\nRetail POS systems are built to handle high transaction volume and detailed product management.\n\n* Scan barcodes, manage discounts, and track inventory across multiple branches in real time.\n* Support for SKU-level tracking and stock alerts helps avoid overstocking or stockouts.\n* Enable loyalty programs and cashless checkout, encouraging repeat visits and faster transactions.\n* Some systems allow product bundling, seasonal promotions, and customer purchase history tracking.\n\n### POS system for cafes\n\nCafes typically need fast, efficient systems that can handle high foot traffic during peak hours.\n\n* Simplify counter service and queue management with touch-based ordering and quick payment flows.\n* Accept multiple payments easily, including DuitNow QR, e-wallets, and cards to suit customer preferences.\n* Popular features include digital menus, customer tipping options, and daily sales summaries.\n* Integration with QR table ordering is increasingly common in modern cafe setups.\n\n### POS system for small businesses\n\nSmaller operations benefit from easy-to-use, affordable systems that donât require complex setup.\n\n* Easy to set up and cost-effective, with intuitive interfaces suited for first-time users. Cloud-based POS systems allow business owners to manage both physical and online sales from a single dashboard, useful for pasar malam stalls, home-based businesses, or weekend bazaars.\n* Features like cash flow tracking and basic CRM tools help build better customer relationships without needing separate software.\n\n### Shopify POS\n\nShopify POS is ideal for businesses that already run a Shopify online store and want to expand into physical retail.\n\n* Combines your online and in-person sales, creating a seamless experience for both the merchant and customer.\n* Shared customer and inventory data across channels ensures consistent product availability and personalised
1service.\n* You can run promotions that apply online and in-store, offer local pickup options, and use one dashboard for everything.\n* Works with Malaysian payment gateways like Billplz for the online-store side of your sales.\n\n_Also read:_ [_Shopify payment gateway in Malaysia with local payment methods_](https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods)\n\n## Where Billplz fits alongside your POS\n\nA POS system runs your counter operations. Billplz handles payment collection, and the two work side by side rather than as one integrated system. There is no pre-built Billplz plugin for POS software today: Billplz plugins cover eCommerce platforms such as Shopify, WooCommerce, and OpenCart, and the REST API covers custom builds.\n\nWhat you can do today:\n\n\\* **Accept QR payments at the counter.** Generate a static DuitNow QR code or payment link from your Billplz dashboard and display it where customers pay.\n\n\\* **Unify your online collections.** If your POS brand also runs your online store (for example Shopify POS with a Shopify store), Billplz plugins handle the online checkout while the POS terminal handles in-person cards.\n\n\\* **Reconcile online collections in one place.** Payments collected through Billplz sit in one dashboard with transaction records for accounting.\n\nTo connect Billplz to your setup, see the [Billplz integrations](https://main.billplz.com/integrations) page for the API and supported plugins.\n\n---\n\n## FAQ\n\n### Whatâs the difference between a POS system and a payment gateway?\n\nA POS system manages sales, inventory, and reporting, while a payment gateway handles the actual transaction processing. They often integrate together.\n\n### How much does a POS system cost in Malaysia?\n\nCloud subscriptions run from about MYR 39 to MYR 471 per month depending on provider and plan, and one-time hardware-inclusive packages range from about MYR 1,290 to MYR 6,490 (provider pricing as of July 2026). See the comparison table above.\n\n### Can a POS system work without the internet?\n\nYes. Many offer an offline mode where transactions are queued and sync later.\n\n### What is the best POS system for restaurants in Malaysia?\n\nLook for systems with kitchen display support, order tracking, and QR integration. Options like StoreHub or Slurp! are popular. \n\n### Which POS system for retail supports e-wallet payments?\n\nMany cloud-based POS providers support Wallet payments through their own payment terminals. See the payments column in the comparison table above.\n\n### Is there an affordable POS system for small businesses in Malaysia?\n\nYes. mPOS and cloud-based setups offer affordable monthly plans with essential features.\n\n### Whatâs the difference between a POS system for a cafe and a restaurant POS?\n\nCafe systems focus on fast counter service, while restaurant systems handle table management, kitchen coordination, and multiple orders.\n\n### Can Shopify POS integrate with Malaysian payment gateways like Billplz?\n\nBillplz connects to your Shopify online store through its plugin, handling your online checkout. In-person payments taken at a Shopify POS terminal are processed by the POS's own payment provider.\n\n### How do I integrate my POS system with eCommerce platforms like Shopify or WooCommerce?\n\nUse POS systems that offer native plugins or API support for seamless integration with online stores.\
1n\n### Are POS systems in Malaysia secure, and how do they protect customer data?\n\nYes. Most modern POS systems in Malaysia comply with PCI DSS (Payment Card Industry Data Security Standards) to ensure all card transactions are encrypted and tokenised. Reputable providers also use SSL encryption, role-based access controls, and regular software updates to protect both business and customer data. \nFor added security, choose POS systems and payment providers that maintain PCI DSS compliance; Billplz, for example, maintains PCI DSS compliance and PayNet certification.\n\n---\n\n## Conclusion\n\nChoosing the right POS system comes down to your business needs, budget, and local payment preferences. Pick one that covers the payment methods your customers use at the counter. For online sales and QR collections, pair it with a payment gateway like Billplz.\n\n_Explore_ [_Billplz integrations_](https://main.billplz.com/integrations) _to see the plugins and API that connect your online sales._","__component":"shared.rich-text"}]},{"id":422,"documentId":"ypmk7ccs31lsn6rop4m5phjf","title":"Toyyibpay vs Billplz: Which payment gateway should you choose?","slug":"toyyibpay-billplz-payment-gateway-comparison","createdAt":"2025-10-15T05:12:48.768Z","updatedAt":"2026-04-27T07:55:51.158Z","publishedAt":"2026-04-27T07:55:51.347Z","publishDate":"2025-10-15T05:12:48.768Z","cover":{"id":69,"documentId":"yj08p427tfkid5cg3nt9m8lz","name":"251015_01_01_img.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_01_01_img_7f57c54a1b.webp","hash":"small_251015_01_01_img_7f57c54a1b","mime":"image/webp","name":"small_251015_01_01_img.webp","path":null,"size":6.71,"width":500,"height":278,"sizeInBytes":6706},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_01_01_img_7f57c54a1b.webp","hash":"medium_251015_01_01_img_7f57c54a1b","mime":"image/webp","name":"medium_251015_01_01_img.webp","path":null,"size":10.28,"width":750,"height":417,"sizeInBytes":10278},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_01_01_img_7f57c54a1b.webp","hash":"thumbnail_251015_01_01_img_7f57c54a1b","mime":"image/webp","name":"thumbnail_251015_01_01_img.webp","path":null,"size":2.99,"width":245,"height":136,"sizeInBytes":2994}},"hash":"251015_01_01_img_7f57c54a1b","ext":".webp","mime":"image/webp","size":13.1,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_01_01_img_7f57c54a1b.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-26T06:26:17.155Z","updatedAt":"2025-10-26T06:26:17.155Z","publishedAt":"2025-10-26T06:26:17.155Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":149,"metaTitle":"Toyyibpay vs Billplz: Which payment gateway should you choose?","metaDescription":"Compare Toyyibpay and Billplz for Malaysian businesses. Explore fees, payment methods, eCommerce integrations, scalability, and why Billplz is ideal for long-term growth.","metaKeywords":"Toyyibpay vs Billplz, payment gateway comparison Malaysia, Malaysian payment gateway, FPX payment gateway, Billplz review, Toyyibpay review, payment gateway for SME Malaysia, online payment Malaysia, payment gateway fees Malaysia","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_01_01_img_7f57c54a1b.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Toyyibpay vs Billplz: Which payment gateway should you choose?","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Toyyibpay and Billplz for Malaysian businesses. Explore fees, payment methods, eCommerce integrations, scalability, and why Billplz is ideal for long-term growth.","dateModified":"2026-04-27T07:55:48.978Z","datePublished":"2025-10-15T05:12:48.768Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison","@type":"WebPage"}}},"blocks":[{"id":397,"body":"**Key takeaways:**\n\n* Toyyibpay is ideal for NGOs, micro-businesses, and simple payment needs, offering a Shariah-compliant setup and flat FPX rates.\n* Billplz supports a wider range of payment options, including FPX, DuitNow, QR, e-wallets, and BNPL â built for SMEs and scaling enterprises.\n* Pricing: Toyyibpay offers low-cost entry, while Billplz provides transparent, competitive rates with feature-rich plans.\n* Integrations: Billplz connects directly with Shopify, WooCommerce, and custom APIs; Toyyibpay offers limited e-commerce plugin support.\n* Settlement speed: Billplz offers faster payouts (next-day for FPX, real-time for DuitNow) compared to Toyyibpay's 1â4 business day timeline.\n* Scalability: Billplz provides a professional-grade infrastructure with tools like split payments, dashboards, and catalog tools â ideal for high-volume or multi-channel businesses.\n\n## Introduction\n\nPayment gateways are essential for Malaysian businesses, especially for SMEs, NGOs, and online sellers. Two popular options in the local market are Toyyibpay and Billplz â both offering strong capabilities for accepting online payments.\n\nThis article provides a detailed comparison of both platforms, including features, pricing, and use cases, to help you decide the right fit.\n\n## Overview of both platforms\n\nBoth Toyyibpay and Billplz serve as essential online payment solutions in Malaysia, but they cater to different types of users and business growth stages.\n\n### What is Toyyibpay?\n\n[Toyyibpay](https://toyyibpay.com/) is a Shariah-compliant online payment gateway popular among NGOs, micro-businesses, and crowdfunding initiatives. Itâs widely used for its simplicity and minimal setup requirements.\n\nThe platform allows businesses and nonprofits to generate payment links and collect payments via FPX or cards with low fees.\n\nIts straightforward interface and ease of use make it appealing to first-time sellers or organisations looking to accept basic online payments quickly.\n\n### What is Billplz?\n\n[Billplz](https://main.billplz.com/) is a leading Malaysian payment gateway trusted by SMEs and enterprises for its reliability, scalability, and developer-friendly features. Designed to support growing businesses, it offers a powerful suite of tools including a real-time dashboard, advanced APIs, and seamless plugin integrations.\n\nWith support for a wide range of local payment methods, including FPX, DuitNow, e-wallets, and Buy Now Pay Later (BNPL), Billplz helps businesses streamline transactions and enhance customer convenience.\n\nIts transparent, cost-effective pricing and scalable infrastructure make it easy for businesses to grow efficiently.\n\n## Key comparison table: Billplz vs. Toyyibpay\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eToyyibpay\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eBillplz\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eTarget Users\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNGOs, micro-businesses, and small sellers\u003c/td\u003e\u003ctd\u003eSMEs, e-commerce, and enterprises\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment Methods\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFPX, and Credit/Debit Cards\u003c/td\u003e\u003ctd\u003eFPX, DuitNow, QR, E-wallets (GrabPay, TNG, ShopeePay), BNPL (Atome, Grab PayLater), and cards\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePricing\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFlat per-transaction fees for B2C and B2B (Standard Plan)\u003c/td\u003e\u003ctd\u003eTransparent flat pricing per FPX transaction. See \u003ca href=\"https://main.billplz.com/pricing\"\u003epricing page\u003c/a\u003e for current rates\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSettlement\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e1â4 business days\u003c/td\u003e\u003ctd\u003eNext business day (FPX), real-time for DuitNow transfer\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeatures\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBill link generation and recurring payments\u003c/td\u003e\u003ctd\u003eFull dashboard, split payments, API, and plugins\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eScalability\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBest for small-scale transactions\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eHigh-volume, multi-channel support\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupport\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBasic customer service\u003c/td\u003e\u003ctd\u003eDedicated local team, enterprise-grade reliability\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eIntegrations\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLimited e-commerce plugins\u003c/td\u003e\u003ctd\u003eShopify, WooCommerce, custom APIs, and enterprise tools\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Fees and pricing\n\nToyyibpay is known for very low startup fees and flat per-transaction pricing. It's ideal for micro-sellers and NGOs due to the low entry barrier.\n\nBillplz also offers flat, transparent pricing. The free Basic plan charges a slightly higher per-transaction rate, while the annual Standard plan brings that cost down â balancing affordability with a more powerful, feature-rich platform.\n\nFor very small businesses with minimal volume, Toyyibpay may be the cheapest start. For scaling businesses, Billplz's professional plans offer a lower cost per transaction, balanced with superior reliability and features.\n\n_Check the latest rates on the_ [_Billplz pricing_](https://main.billplz.com/pricing) _page._\n\n### Payment methods\n\nToyyibpay primarily supports FPX and local credit/debit card payments, making it a suitable choice for basic online transactions and straightforward payment collection.\n\nBillplz offers a significantly wider range of local payment options, including FPX, DuitNow Transfer (Real-time payout), DuitNow QR, major E-wallets (GrabPay, Touch 'n Go, ShopeePay, Boost), and BNPL providers (Atome, Grab PayLater).\n\nThis wider coverage makes Billplz more future-proof, ensuring you can accept payments via your customers' preferred method, which is crucial for modern e-commerce growth.\n\n_Also read:_ [_Shopify payment gateway in Malaysia with local payment methods_](https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods)\n\n### Features \u0026 integrations\n\n#### Toyyibpay:\n\n* Simple bill link generation and QR code creation.\n* Recurring billing (popular for subscriptions/donations).\n* Easy-to-use for small, single-channel projects.\n\n#### Billplz
1:\n\n* Rich feature set like split payments, payout management, and team permissions (Single Sign-On or SSO).\n* Developer-first with a robust API and webhooks, allowing custom, complex integrations.\n* Direct integrations with major e-commerce platforms like Shopify and WooCommerce, plus a library of over 30 prebuilt plugins for quick setup.\n* Real-time dashboard for detailed analytics and efficient reconciliation.\n\n_Read more about_ [_Billplz integrations_](https://main.billplz.com/integrations) _here!_\n\n### Reliability \u0026 scalability\n\nToyyibpay works well for micro/SME sellers but may face limitations when handling the high volume, complex payment routing, or multi-channel operations required by a scaling business.\n\nBillplz is built for enterprise reliability, offering a 99.999% historical API uptime and faster settlements. Its infrastructure supports high-volume processing and provides advanced features like dedicated support and H2H (Host-to-Host) integration for corporations. \n\nBusinesses aiming to scale their e-commerce operations or expand across channels will find Billplz more future-proof and sustainable.\n\n## Which should you choose: Billplz or Toyyibpay?\n\n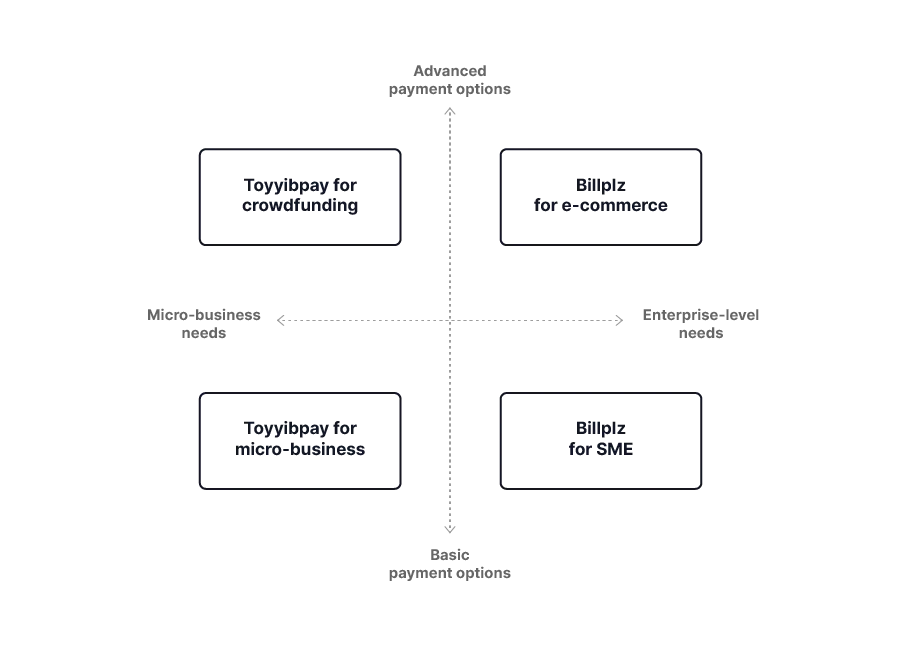\n\n##### Choose Billplz if:\n\n* You are scaling beyond small payments into SME or enterprise levels.\n* You want the widest variety of local payment options: FPX, DuitNow, e-wallets, and BNPL.\n* You run an e-commerce store like Shopify and need robust, official plugins.\n* You require faster settlements and enterprise-level reliability.\n* You need advanced operational features like split payments or multi-user access for your team.\n\n##### Choose Toyyibpay if:\n\n* You are a micro-business, NGO, or crowdfunding project and need a quick, low-cost setup with simple payment links.\n* Your customer payments are primarily limited to FPX or card, and transaction volume is low.\n\nThink of Toyyibpay as your initial launchpad for simple transactions. If you plan to scale, Billplz provides the reliable, feature-rich infrastructure that moves you beyond the basics to handle multi-channel sales, complex payment flows, and high volume efficiently.\n\n## How does Billplz support your growth?\n\nWhile Toyyibpay is excellent for getting started, offering immediate simplicity and low entry costs, Billplz is engineered to grow with your business, providing the robust infrastru
1cture needed to handle future complexity and high transaction volumes.\n\nBillplz offers a professional, scalable infrastructure:\n\n* **Fast payouts:** FPX funds are paid out on the next business day, with DuitNow Transfers settled in real-time, dramatically improving cash flow efficiency.\n* **Flat, transparent pricing:** Predictable costs that simplify budgeting and ensure that transaction costs scale predictably as your volume increases.\n* **Real-time dashboard \u0026 analytics:** Provides a complete, consolidated view of all transactions, enabling faster reconciliation, data-driven decisions, and real-time monitoring of business health.\n* **Robust API \u0026 30+ plugins:** Offers a powerful REST API for custom integrations and numerous prebuilt plugins for major platforms like Shopify and WooCommerce.\n* **Split payments:** Automatically distribute funds between multiple accounts, perfect for marketplace models or managing multiple revenue streams.\n* **Commerce tools (Catalog):** Includes Catalog Payment Form (prebuilt payment links for services/fundraising) and Catalog Store (a simple online storefront), extending your sales capabilities without requiring a developer.\n* **Enterprise-ready security:** Maintains Bank-level security and PCI DSS compliance, ensuring a protected environment as your transaction volume and data complexity increase.\n\n---\n\n## FAQ\n\n### Is Toyyibpay Shariah-compliant?\n\nYes. Toyyibpay was designed with Shariah-compliant principles and is widely used by NGOs and Islamic-based institutions.\n\n### Does Billplz support FPX payments?\n\nYes. FPX (online bank transfer) is Billplz's core service. Flat per-transaction fees apply, and payouts are guaranteed on the next business day. See the [pricing page](https://main.billplz.com/pricing) for current rates.\n\n_Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n\n### Which payment gateway is better for small businesses in Malaysia?\n\nToyyibpay is great for starting out. But if your business is growing, Billplz offers more features, integrations, and reliability.\n\n### Can Toyyibpay and Billplz integrate with Shopify or WooCommerce?\n\nBillplz does. It has official integrations with Shopify and WooCommerce. Toyyibpay has limited support for e-commerce platforms.\n\n### Which has faster settlements: Toyyibpay or Billplz?\n\nBillplz generally offers faster settlements, including next-day FPX payout. Toyyibpay payouts typically take 1â4 business days.\n\n---\n\n## Conclusion\n\nIn the Malaysian market, both Toyyibpay and Billplz offer reliable payment collection services.\n\nFor entry-level users, small NGOs, and simple payment link needs, Toyyibpay provides immediate ease and affordability.\n\nBut for any business with growth ambitions, from SMEs to larger enterprises, Billplz delivers greater long-term value. It not only matches Toyyibpay on core FPX efficiency but significantly extends capabilities with multi-user access, dedicated e-commerce plugins, and a wide array of payment methods, ensuring a seamless experience as you expand.\n\nThe choice is between simplicity today and scalability tomorrow.\n\nFor more information about Billplz, read:\n\n* [iPay88 vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-ipay88-payment-gateway-malaysia)\n* [Billplz vs Stripe: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-stripe-malaysia-payment-gateway-comparison)\n* [Billplz vs Curlec: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/billplz-vs-curlec-payment-gateway-comparison)\n* [SenangPay vs Billplz: Which payment gateway should you choose?](https://main.billplz.com/blog/insights/senangpay-vs-billplz-payment-gateway-comparison)","__component":"shared.rich-text"}]},{"id":401,"documentId":"eoybfgwkblcsyrsax8p3lqky","title":"Shopify vs WooCommerce (WordPress): An updated comprehensive comparison","slug":"shopify-vs-woocommerce-comparison","createdAt":"2025-10-15T04:53:47.058Z","updatedAt":"2026-01-02T01:07:12.302Z","publishedAt":"2026-01-02T01:07:12.358Z","publishDate":"2025-10-15T04:53:47.058Z","cover":{"id":46,"documentId":"dspw0np53rdygi2eftophthv","name":"251015_06_01_img.webp","alternativeText":"Shopify vs WooCommerce","caption":"Shopify vs WooCommerce","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_06_01_img_bf7df99ffe.webp","hash":"small_251015_06_01_img_bf7df99ffe","mime":"image/webp","name":"small_251015_06_01_img.webp","path":null,"size":11.92,"width":500,"height":278,"sizeInBytes":11920},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_06_01_img_bf7df99ffe.webp","hash":"medium_251015_06_01_img_bf7df99ffe","mime":"image/webp","name":"medium_251015_06_01_img.webp","path":null,"size":22.16,"width":750,"height":417,"sizeInBytes":22158},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_06_01_img_bf7df99ffe.webp","hash":"thumbnail_251015_06_01_img_bf7df99ffe","mime":"image/webp","name":"thumbnail_251015_06_01_img.webp","path":null,"size":3.45,"width":245,"height":136,"sizeInBytes":3452}},"hash":"251015_06_01_img_bf7df99ffe","ext":".webp","mime":"image/webp","size":42.79,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_06_01_img_bf7df99ffe.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-22T08:30:29.252Z","updatedAt":"2025-10-22T08:30:42.236Z","publishedAt":"2025-10-22T08:30:29.253Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":128,"metaTitle":"Shopify vs WooCommerce (WordPress): An updated comprehensive comparison","metaDescription":"Compare Shopify vs WooCommerce for Malaysian businesses in 2025. Learn setup costs, payment gateway options like Billplz, scalability, SEO tools, and more.","metaKeywords":"Shopify vs WooCommerce, WordPress eCommerce, eCommerce platform comparison, Shopify Malaysia, WooCommerce Malaysia, self-hosted eCommerce, hosted eCommerce platform, online store Malaysia, Shopify WooCommerce comparison 2025","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_06_01_img_bf7df99ffe.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Shopify vs WooCommerce (WordPress): An updated comprehensive comparison","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Shopify vs WooCommerce for Malaysian businesses in 2025. Learn setup costs, payment gateway options like Billplz, scalability, SEO tools, and more.","dateModified":"2026-01-02T01:02:49.356Z","datePublished":"2025-10-15T04:53:47.058Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/shopify-vs-woocommerce-comparison","@type":"WebPage"}}},"blocks":[{"id":376,"body":"**Key takeaways:**\n\n* Shopify is a fully hosted platform ideal for beginners and businesses seeking a quick, low-maintenance setup with predictable monthly costs and built-in security.\n* WooCommerce is a self-hosted WordPress plugin offering complete control, unlimited customization, and better scalability for content-heavy or highly tailored eCommerce needs.\n* Shopify prioritizes ease of use, while WooCommerce prioritizes flexibility and ownership â your choice depends on your technical comfort and business goals.\n* WooCommerce supports all major local Malaysian payment gateways, including FPX, DuitNow, and e-wallets â directly and with full control.\n* Choose Shopify if you value speed and simplicity. Choose WooCommerce if you want flexibility, customization, and control over your infrastructure.\n* Billplz integrates seamlessly with both Shopify and WooCommerce, making it easy for Malaysian sellers to offer secure, local payment options no matter which platform they use.\n\n## Introduction\n\n[Shopify](https://www.shopify.com/) and [WooCommerce](https://woocommerce.com/) are two of the most popular eCommerce platforms globally and among Malaysian businesses. Both have powered millions of online stores, but they represent fundamentally different approaches to building an online business.\n\nShopify is a fully hosted, subscription-based platform (Software as a Service, or SaaS). Itâs an all-in-one solution that takes care of everything from hosting to security.\n\nWooCommerce, on the other hand, is a free, open-source plugin that transforms a self-hosted [WordPress](https://wordpress.com/) website into a comprehensive online store.\n\nIn this guide, weâll provide a side-by-side comparison of Shopify and WooCommerce to help Malaysian sellers decide which is the better fit for their needs.\n\n## Overview of each platform\n\nHere is a quick look at the two dominant e-commerce solutions, Shopify and WooCommerce.\n\n### What is Shopify?\n\nShopify is a fully hosted, subscription-based e-commerce platform. It provides a complete, turn-key solution, meaning the company manages all the technical aspects, including server maintenance, hosting, security (SSL), and software updates.\n\nThe platform is renowned for its ease of use and speed to launch. Merchants, even those with no technical background, can set up a professional online store in a matter of hours.\n\nWhile the core functionality is robust, the platform also offers a vast App Store ecosystem to scale features like inventory management, marketing, and advanced analytics. Itâs also mobile-optimized and supports a variety of sales channels, including social media.\n\n_Also read:_ [_Shopify payment gateway in Malaysia with local payment methods_](https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods)\n\n### What is WooCommerce (WordPress)?\n\nWooCommerce is a free WordPress plugin that turns any WordPress site into a fully functional online store. It's ideal for users who are already familiar with WordPress or who want more control over their siteâs functionality and design.\n\nAlthough the WooCommerce plugin itself is free, running a WooCommerce store requires separate web hosting, domain registration, SSL, and often premium themes or plugins.\n\nHowever, it offers unparalleled flexibility and is popular among developers, content-heavy brands, and custom-built websites.\n\n## Shopify vs WooCommerce â Key comparison\n\nBoth Shopify and WooCommerce power thousands of online stores in Malaysia, but their approach to eCommerce are fundamentally different. Hereâs how they compare:\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eShopify\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eWooCommerce (WordPress)\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eType\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eFully hosted SaaS\u003c/td\u003e\u003ctd\u003eOpen-source plugin for WordPress\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eEase of Setup\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eQuick setup, user-friendly, no coding\u003c/td\u003e\u003ctd\u003eRequires hosting + WordPress knowledge, more steps\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCost\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMonthly subscription + app/transaction fees\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eFree plugin, mandatory costs for hosting/domain/theme/plugins\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eDesign \u0026amp; Themes\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eShopify Theme Store (premium focus)\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eVast WordPress themes + WooCommerce themes (free/paid)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment Options\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eShopify Payments (not in MY) + 3rd-party (like Billplz, PayPal, etc)\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eWide gateway support (Billplz, Stripe, PayPal, etc.)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eScalability\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eHigh, managed hosting \u0026amp;
1 infrastructure\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eHigh, but performance depends on hosting quality \u0026amp; optimization\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSecurity\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eBuilt-in SSL, PCI compliant, managed by Shopify\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eRequires the user to manage hosting security \u0026amp; updates\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCustomization\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLimited without coding, depends on the theme structure\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eExtremely flexible, full control over code and themes\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSupport\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e24/7 official Shopify support\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eCommunity-driven + hosting provider support\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Pricing \u0026 costs\n\nShopify operates on a tiered monthly subscription model, plus additional transaction fees if you don't use their proprietary payment gateway, or if you are in a region where it is not available (like Malaysia). Merchants must also budget for paid applications to add specific functionality. The pricing is predictable and includes hosting.\n\nWooCommerce is free, but youâll need to pay for a domain, hosting, SSL, and premium plugins or themes. While initial costs may seem lower, scaling can introduce complexity.\n\n### Ease of use\n\nShopify is fundamentally designed for the non-technical user. Its setup process is a simple step-by-step wizard, and its dashboard is intuitive for daily store management. It offers a fast route to market.\n\nWooCommerce requires more technical familiarity, primarily with setting up and managing a WordPress site and web hosting. The initial setup time is longer due to the multiple steps (installing WordPress, installing WooCommerce, and setting up hosting).\n\nHowever, for anyone already comfortable with the WordPress interface, the daily management is flexible.\n\n### Design \u0026 customization\n\nShopify provides access to the Shopify Theme Store, offering high-quality, conversion-optimized, yet somewhat restrictive, pre-set templates. Customization is handled through a drag-and-drop editor, offering limited backend control without advanced coding.\n\nWooCommerce offers complete, unlimited customization. You can choose from thousands of WordPress and WooCommerce themes and tweak every element via code or page builders like [Elementor](https://elementor.com/).\n\n### Payment gateways\n\nIn Malaysia, Shopify relies entirely on third-party payment providers like Billplz, Stripe, or PayPal for local payment processing. As the proprietary Shopify Payments is currently unavailable in Malaysia, merchants must rely on third-party payment gateways. This can incur additional transaction fees in some cases.\n\nWooCommerce benefits from being open-source and has direct support for virtually all major Malaysian payment gateways. This allows merchants to natively accept methods like FPX, DuitNow, and all major e-wallets. This flexibility enables businesses to choose the provider with the best rates and most comprehensive feature set.\n\nBillplz integrates seamlessly with both Shopify and WooCommerce. It offers Malaysian businesses a unified, hassle-free way to accept essential local payment methods such as FPX, DuitNow, e-wallets, and BNPL.\n\n_Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n\n### Marketing \u0026 SEO tools\n\nShopify has robust built-in SEO features like automatic sitemaps and customizable meta tags, and a large app store of marketing tools. However, its blog and content management capabilities are relatively basic.\n\nWooCommerce runs on WordPress â the worldâs most SEO-friendly CMS. Merchants can leverage powerful plugins like [Yoast SEO](https://yoast.com/) or [RankMath](https://rankmath.com/), making it the superior choice for businesses planning a content-heavy strategy to drive organic traffic.\n\n### Scalability \u0026 performance\n\nShopify handles scalability automatically. Its managed infrastru
1cture is designed to handle massive traffic spikes, like during major sales events, without the merchant having to worry about upgrading servers or configuration.\n\nWooCommerce is highly scalable, but its performance is entirely dependent on the quality of the web hosting and how well the store is configured and optimized. A high-traffic WooCommerce store requires premium managed hosting, caching, and regular maintenance.\n\n### Seller \u0026 buyer experience\n\nShopify offers a famously fast and streamlined checkout process. The user experience (UX) is highly consistent, mobile-optimized, and designed for high conversion across all stores.\n\nWooCommerce offers more flexibility, but the seller and buyer experience will depend heavily on the chosen theme, plugins, and setup quality.\n\nA well-built WooCommerce store can match or exceed Shopifyâs UX, but a poorly configured one can result in slower loading times and a complicated checkout process.\n\n## Which is better for your business: Shopify or WooCommerce?\n\nChoosing between the two ultimately depends on your resources, goals, and technical comfort level.\n\n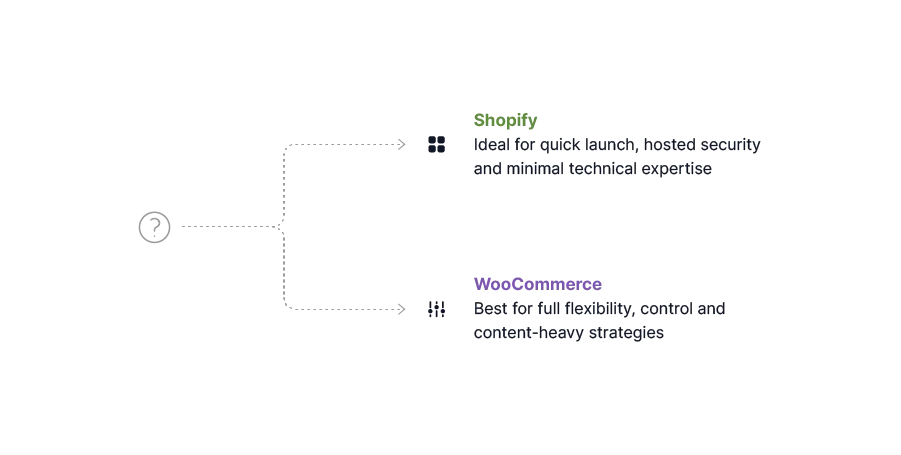\n\n#### Choose Shopify if:\n\n* You want a quick launch with minimal technical overhead.\n* You prioritize hosted security and guaranteed performance.\n* You have minimal to no technical expertise and don't want to manage hosting or updates.\n* Your primary goal is transactional e-commerce without a complex content strategy.\n\n#### Choose WooCommerce if:\n\n* You want full flexibility and control over every aspect of your store.\n* You are comfortable managing a WordPress site and web hosting, or have a technical team.\n* You plan to implement a deep, content-heavy marketing strategy.\n* You are looking for potentially lower long-term costs and prefer to own your entire platform.\n\n## How do you choose the right platform for your products?\n\nThe decision factors should be weighted according to your business needs:\n\n* **Budget**: Is predictable monthly spending better than varied, long-term costs?\n* **Technical expertise**: Do you have the skills or budget for a developer, or do you need a no-code solution?\n* **Product range \u0026 inventory**: Does your business require specific, niche inventory management features, or is the standard e-commerce flow sufficient?\n* **Content strategy**: Is your storeâs success tied to blogging and content marketing? If so, WordPress/WooCommerce is the stronger choice.\n\nRegardless of which platform you chooseâShopify or WooCommerceâsecuring a reliable, local payment integration is essential for high conversion in Malaysia.\n\nPayment solutions like [Billplz](https://main.billplz.com/collection) seamlessly bridge the gap, enabling your customers to pay using preferred local methods like FPX, DuitNow, BNPL, and popular e-wallets, ensuring a smooth and trusted transaction experience on both platforms.\n\nWith Billplz, you get a secure platform that simplifies payment reconciliation and improves the overall checkout experience.\n\n---\n\n## FAQ\n\n### Is Shopify or WooCommerce better for small businesses in Malaysia?\n\nShopify is generally better for the smallest businesses (solopreneurs, micro-businesses) due to its simplicity, quick setup, and included hosting.\n\nWooCommerce becomes viable and often better for small businesses that have a budget for quality hosting and want more control and flexibility to grow into a complex store.\n\n### Which is cheaper: Shopify or WooCommerce?\n\nWooCommerce can be cheaper initially, but long-term costs vary depending on hosting and plugin usage. Shopify has predictable monthly pricing but higher fees in Malaysia due to limited native payment options.\n\n### Does Shopify support FPX payments in Malaysia?\n\nYes, Shopify supports FPX payments in Malaysia indirectly through third-party payment gateways (like Billplz) that integrate with the platform.\n\n### Can WooCommerce integrate with Billplz?\n\nYes, WooCommerce integrates seamlessly with Billplz. Billplz provides official plugins that allow merchants to accept payments like FPX, DuitNow, and e-wallets directly within their WooCommerce checkout process.\n\n### Which platform is better for SEO: Shopify or WooCommerce?\n\nWooCommerce (with WordPress) is generally considered better for SEO. This is due to the platform's superior content management capabilities and the availability of powerful, specialized SEO plugins like Yoast SEO and RankMath.\n\nShopify has good built-in SEO, but its content features are more limited.\n\n---\n\n## Conclusion\n\nThereâs no one-size-fits-all solution. Shopify and WooCommerce serve different needs. Shopify offers convenience and fast launch capabilities. WooCommerce excels in customization and long-term flexibility.\n\nThe ultimate goal, regardless of the platform, is to sell effectively.\n\nBillplz powers both Shopify and WooCommerce with seamless, local payment solutions for Malaysian businesses. Whether you're a beginner or a scaling enterprise, Billplz helps ensure your payment operations are secure, affordable, and fully integrated.","__component":"shared.rich-text"}]},{"id":484,"documentId":"y5pdslf5vk27lwodn41sgamj","title":"Lazada vs Shopee vs TikTok Shop Malaysia: fees and best fit","slug":"lazada-vs-shopee-vs-tiktok-shop-malaysia","createdAt":"2025-10-15T04:26:22.384Z","updatedAt":"2026-07-04T02:59:02.681Z","publishedAt":"2026-07-04T02:59:02.836Z","publishDate":"2025-10-15T04:26:22.384Z","cover":{"id":58,"documentId":"im61qf65sox65z39w5gdzm1z","name":"251015_07_01_img.webp","alternativeText":"Lazada vs Shopee vs TikTok shop","caption":"Lazada vs Shopee vs TikTok shop","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_07_01_img_2d6262d6b7.webp","hash":"small_251015_07_01_img_2d6262d6b7","mime":"image/webp","name":"small_251015_07_01_img.webp","path":null,"size":6.39,"width":500,"height":278,"sizeInBytes":6392},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_07_01_img_2d6262d6b7.webp","hash":"medium_251015_07_01_img_2d6262d6b7","mime":"image/webp","name":"medium_251015_07_01_img.webp","path":null,"size":9.63,"width":750,"height":417,"sizeInBytes":9630},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_07_01_img_2d6262d6b7.webp","hash":"thumbnail_251015_07_01_img_2d6262d6b7","mime":"image/webp","name":"thumbnail_251015_07_01_img.webp","path":null,"size":2.98,"width":245,"height":136,"sizeInBytes":2976}},"hash":"251015_07_01_img_2d6262d6b7","ext":".webp","mime":"image/webp","size":12.35,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_07_01_img_2d6262d6b7.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-23T07:10:58.794Z","updatedAt":"2025-10-23T07:11:14.440Z","publishedAt":"2025-10-23T07:10:58.795Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":211,"metaTitle":"Lazada vs Shopee vs TikTok Shop Malaysia: fees and best fit","metaDescription":"Compare Lazada, Shopee, and TikTok Shop seller fees, audiences, and logistics, and see when selling on your own store with Catalog makes sense.","metaKeywords":"Lazada vs Shopee, TikTok Shop Malaysia, eCommerce platform comparison, online selling Malaysia, marketplace comparison Malaysia, Lazada seller guide, Shopee seller guide, TikTok Shop seller, marketplace seller fees Malaysia","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_07_01_img_2d6262d6b7.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Lazada vs Shopee vs TikTok Shop Malaysia: fees and best fit","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Compare Lazada, Shopee, and TikTok Shop seller fees, audiences, and logistics, and see when selling on your own store with Catalog makes sense.","dateModified":"2026-07-04T02:53:40.639Z","datePublished":"2025-10-15T04:26:22.384Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/lazada-vs-shopee-vs-tiktok-shop-malaysia","@type":"WebPage"}}},"blocks":[{"id":459,"body":"**Key takeaways:**\n\n* Lazada, Shopee, and TikTok Shop dominate Malaysiaâs e-commerce landscape, each offering unique strengths for sellers.\n* Lazada is ideal for branded goods and premium products, thanks to its strong logistics and brand-focused experience.\n* Shopee is the market leader, best suited for mass-market, price-sensitive items with strong promotions and ad tools.\n* TikTok Shop excels in lifestyle and trend-driven categories, using content creators and live selling to drive impulse purchases.\n* Sellers should consider multi-platform strategies to maximize reach and reduce dependency on a single platform.\n* Sellers expanding beyond marketplaces can open their own store with Catalog and accept FPX, Wallet, and Card payments through Billplz.\n\n## Introduction\n\nMalaysia's e-commerce market continues to grow, led by three major players. For years, the market was primarily dominated by [Lazada](https://www.lazada.com.my/) and [Shopee](https://shopee.com.my/). However, the fast-rising emergence of [TikTok Shop](https://seller-my.tiktok.com/university) has dramatically reshaped the competitive dynamics, compelling sellers to reconsider their platform strategy for maximum reach and profitability.\n\nThis guide provides an updated, side-by-side comparison of Lazada, Shopee, and TikTok Shop to help Malaysian sellers choose the right platform and develop a winning strategy.\n\n## Overview of each platform\n\nMalaysia's e-commerce scene is dominated by three major players: Lazada, Shopee, and the fast-rising TikTok Shop, each with unique strengths, audiences, and seller opportunities.\n\nHere's what you need to know about them:\n\n### What is Lazada?\n\nFounded in 2012 and backed by the massive Chinese tech conglomerate Alibaba Group, Lazada is one of Southeast Asia's longest-standing e-commerce marketplaces. It has consistently focused on creating a superior shopping environment, particularly for brand-conscious consumers.\n\nLazada boasts a strong, integrated logistics ecosystem, [Lazada Logistics](https://www.logistics.lazada.com/), which allows for robust fulfillment and reliable delivery, even for bulky items. This strong infrastructure makes it popular with merchants selling mid-to-high range products and established brands.\n\nCategories where Lazada maintains a strong presence include electronics, home appliances, and fashion. The platform emphasizes its [LazMall](https://pages.lazada.com.my/wow/gcp/route/lazada/my/upr_1000345_lazada/channel/my/upr-router/my?spm=a2o4k.tm80363352.menu.1.37916e5aRnWkoP\u0026hybrid=1\u0026data_prefetch=true\u0026prefetch_replace=1\u0026at_iframe=1\u0026wh_pid=/lazada/channel/my/lazmall-channel/lazmall-channel-pc) for official brand stores to ensure authenticity.\n\n### What is Shopee?\n\nShopee is currently the largest platform by market share in Malaysia and the wider Southeast Asian region, holding an estimated 52% of the total Gross Merchandise Value (GMV) in Southeast Asia as of 2024 (Source: [\\[New report\\] S
1outheast Asiaâs Platform E-commerce GMV Reaches US$128.4B](https://thelowdown.momentum.asia/new-report-southeast-asias-platform-ecommerce-gmv-reaches-us128-4b/#:~:text=Shopee%20expanded%20its%20lead%20with,GMV%20and%20regional%20market%20share.))\n\nKnown for its flash sales, extensive use of vouchers, and mobile-first experience, Shopee attracts price-sensitive shoppers looking for deals on everything from fashion to groceries. It's ideal for mass-market sellers and SMEs aiming to reach a wide audience.\n\nIts wide reach makes it a default starting point for many Small and Medium-sized Enterprises (SMEs) looking to penetrate the online market. The platform heavily utilizes its own logistics arm, [Shopee Xpress](https://spx.com.my/en), alongside numerous third-party partners.\n\n_Also read:_ [_Shopify payment gateway in Malaysia with local payment methods_](https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods)\n\n### What is TikTok Shop?\n\nA game-changer in recent years, TikTok Shop integrates e-commerce directly within TikTok's entertainment-driven platform. It leverages the \"discovery commerce\" model, where users discover and purchase products seamlessly while scrolling their 'For You Page' (FYP) or watching livestreams.\n\nIn just the first half of 2025, TikTok Shopâs GMV in Malaysia surged by 150%, catapulting it past Lazada to become the second-largest e-commerce player in Southeast Asia (Source: [TikTok Shop Doubles Global GMV in 2025](https://www.marketmaze.me/p/tiktok-shop-is-a-global-rocket)).\n\nIt enables creators and sellers to promote products via short videos, livestreams, and interactive content. Particularly effective with Gen Z and millennials, it is driving impulse purchases and viral sales in lifestyle, beauty, and fashion categories.\n\n## Lazada vs Shopee vs TikTok Shop: key comparison\n\nEach platform brings its own strengths, target audiences, and selling strategies. Here's how Lazada, Shopee, and TikTok Shop compare at a glance.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eLazada\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eShopee\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eTikTok Shop\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eMarket Position\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eEstablished, strong logistics\u003c/td\u003e\u003ctd\u003eMarket leader in Malaysia \u0026amp; SEA\u003c/td\u003e\u003ctd\u003eFastest-growing platform, social disruptor\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eUser Base\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMid-income \u0026amp; brand-oriented\u003c/td\u003e\u003ctd\u003eMass market, price-driven\u003c/td\u003e\u003ctd\u003eYounger, content-driven shoppers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFees\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eCommission + payment fee\u003c/td\u003e\u003ctd\u003eCommission + transaction fee\u003c/td\u003e\u003ctd\u003eCommission + service fees\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eMarketing Tools\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLazLive, sponsored ads, LazMall branding\u003c/td\u003e\u003ctd\u003eShopee Ads, vouchers, bundles, Shopee Live\u003c/td\u003e\u003ctd\u003eTikTok Ads, creator collabs, live commerce\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eLogistics\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLazada Logistics (integrated, reliable)\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eShopee Xpress + partners (Affordable, wide network)\u003c/td\u003e\u003ctd\u003e3PL (third-party logistics)+ in-app seller fulfillment (Less mature, but fast)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eProduct Focus\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eElectronics, branded goods, home appliances\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eGeneral marketplace, low-to-mid price items\u003c/td\u003e\u003ctd\u003eFashion, beauty, lifestyle, viral/trend-driven goods\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSeller Support\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eLazada University\u003c/td\u003e\u003ctd\u003eSeller Education Hub\u003c/td\u003e\u003ctd\u003eTikTok Shop Academy, Creator Marketplace, analytics\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Fees and commission structure\n\nAll three platforms charge a commission plus a payment or transaction fee on every order, and the rates change often, sometimes twice a year. Figures below are as published on each platform's official seller pages on 3 July 2026. Confirm current rates in your seller portal before planning margins.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u0026nbsp;\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eLazada\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eShopee\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eTikTok Shop\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eCommission\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eCategory-based; revised effective 21 May 2026; rates shown inside \u003ca href=\"https://sellercenter.lazada.com.my/helpcenter/s/faq/\"\u003eSeller Center\u003c/a\u003e\u003c/td\u003e\u003ctd\u003eMarketplace sellers 0% to 17% by category, or 0% to 12% on the Cashback Programme; Mall rates higher. Effective 21 May 2026, plus 8% SST \u003ca href=\"https://seller.shopee.com.my/edu/article/3503\"\u003eShopee Seller Education Hub\u003c/a\u003e\u003c/td\u003e\u003ctd\u003e0% to 18.9% by subcategory and programme tier, SST inclusive. Effective 13 September 2025 \u003ca href=\"https://seller-my.tiktok.com/university/essay?knowledge_id=6907739532281602\"\u003eTikTok Shop Academy\u003c/a\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePayment / transaction fee\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNot published publicly\u003c/td\u003e\u003ctd\u003e3.78% of order value, SST inclusive\u
1003c/td\u003e\u003ctd\u003e3.78% of subtotal, SST inclusive\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePer-order platform fee\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNot published publicly\u003c/td\u003e\u003ctd\u003eMYR 0.54 per completed order, SST inclusive\u003c/td\u003e\u003ctd\u003eMYR 0.54 per delivered order, SST inclusive\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eNew-seller relief\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eCommission-free for the first 120 days\u003c/td\u003e\u003ctd\u003eCommission-free until 120 days after first listing or 100 completed orders\u003c/td\u003e\u003ctd\u003e30-day platform-fee exemption for new sellers registering from 1 April 2026\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eRegistration\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eNot published publicly\u003c/td\u003e\u003ctd\u003eFree: 0% registration and listing fees\u003c/td\u003e\u003ctd\u003eNo registration fee stated\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n### Marketing \u0026 seller tools\n\n* **Lazada:** Focuses on brand exposure with LazMall, targeted marketing through Sponsored Discovery Ads, and engaging live selling via LazLive. Its affiliate program also encourages external promotion.\n* **Shopee:** Excels at in-app mechanisms like vouchers, bundle deals, and Flash Sales that leverage its large, engaged user base. Shopee Ads are essential for visibility.\n* **TikTok Shop:** Its key strength is content-driven sales. Sellers thrive by running TikTok Ads, collaborating with content creators/influencers, and utilizing live streaming sessions to generate viral, impulse purchases.\n\n### Logistics \u0026 fulfillment\n\n* **Lazada:** Lazada Logistics provides a strong, integrated system with a high degree of control over the delivery process. This integrated model makes it particularly reliable for handling bulky or higher-value items.\n* **Shopee:** Utilizes Shopee Xpress (SPX Express) along with a wide network of third-party logistics (3PL) partners. This hybrid approach allows for an affordable and extensive network, handling the large volume of smaller parcels typical of its mass-market sales.\n* **TikTok Shop:** Primarily relies on third-party logistics partners for fulfillment. While delivery speed is fast and the network is growing, its logistics ecosystem is less mature than the established integrated systems of Lazada and Shopee, requiring sellers to manage fulfillment surges from live commerce more actively.\n\n### Seller experience\n\nAll three platforms provide extensive resources to help sellers succeed. [Lazada University](https://university.lazada.com.my/) and Shopeeâs [Seller Education Hub](https://seller.shopee.com.my/edu/home) are robust training portals offering courses on everything from listing optimization to campaign participation.\n\n[TikTok Shop Academy](https://www.google.com/aclk?sa=L\u0026ai=DChsSEwipi8qx_oSQAxXeo2YCHdIkFqEYACICCAEQARoCc20\u0026co=1\u0026ase=2\u0026gclid=CjwKCAjwxfjGBhAUEiwAKWPwDomAwom-GO62vwu1yWk-pgLyZ1HJa8L87fuV9Lo3kF2Ks_1C2G9m3BoCrSkQAvD_BwE\u0026cid=CAASQ-Ro5O3Smyvh_dps2j244NaIMezKSdRULZ9YjbvQcAzbnV_YbCOR1zqaATNAhT6LYobQVo4AL_vvJFe9LPzep_rcOKI\u0026cce=2\u0026category=acrcp_v1_32\u0026sig=AOD64_0dJgn-oLrkQgv38cxq4gIDue1FtQ\u0026q\u0026nis=4\u0026adurl\u0026ved=2ahUKEwjX6MOx_oSQAxXd2TgGHRWNCa4QqyQoAHoECBUQDQ) focuses heavily on mastering content creation, live streaming, and utilizing the Creator Marketplace for partnerships.\n\nSeller dashboards and reporting tools are available on all three, though the focus varies: Lazada emphasizes brand performance, Shopee focuses on volume/promotions, and TikTok Shop prioritizes content and audience analytics.\n\n### Buyer experience\n\nThe shopping journey is vastly different across the three platforms.\n\n* **Lazada:** Offers a strong, streamlined experience preferred for branded goods, focusing on product authenticity via LazMall and reliable delivery.\n* **Shopee:** Known for heavy promotions, daily vouchers, and \"gam
1ification\" (like Shopee Games) that make shopping entertaining and price-competitive.\n* **TikTok Shop:** Provides an entertaining, discovery-first shopping experience, where the purchase decision is often driven by captivating short videos and live streams rather than a deliberate product search\n\n## Which is better for sellers in Malaysia?\n\nThere is no single \"best\" platform; the ideal choice depends entirely on your product, brand, and selling style.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eBest For\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eLazada\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eShopee\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eTikTok Shop\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eProduct Types\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eElectronics, branded goods, home \u0026amp; living, premium products\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eGeneral items, budget-friendly goods, daily necessities, high-volume items\u0026nbsp;\u003c/td\u003e\u003ctd\u003eLifestyle, fashion, beauty, viral gadgets, and content-driven impulse buys\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eSeller Profile\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eEstablished brands, high-ticket sellers, or sellers with strong supply chains\u0026nbsp;\u003c/td\u003e\u003ctd\u003eSMEs, mass-market sellers, merchants focused on volume/price\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eNew sellers, content creators, and brands targeting young consumers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eAudience\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMid-to-high income, brand-loyal shoppers\u0026nbsp;\u003c/td\u003e\u003ctd\u003ePrice-sensitive mass market\u003c/td\u003e\u003ctd\u003eYounger (Gen Z, Millennials), highly engaged, discovery-led shoppers\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\nBased on the market dynamics, here is a quick guide to choosing your primary focus:\n\n* Choose Lazada if you sell branded, higher-ticket, or electronics/home goods. Your priority is maintaining a premium brand image, assuring quality, and leveraging integrated logistics for reliable delivery. Lazada rewards trust and a high average order value.\n* Choose Shopee if you seek mass-market reach and thrive in competitive, price-sensitive categories. Your strength lies in managing high sales volume efficiently through aggressive promotions, competitive pricing, and extensive ad spending to secure visibility. Â \n* Choose TikTok Shop if your products are highly visual, such as fashion, beauty, or lifestyle items, and you are prepared to leverage short videos and content creators to drive sales through virality and impulse buying. TikTok Shop is the channel for trend-setters and discovery.\n\n## Multi-platform strategy: Can you sell on Shopee, Lazada, and TikTok Shop at the same time?\n\nYes, absolutely. Many successful Malaysian sellers adopt a multi-platform strategy to maximize their reach and de-risk their business. This approach is widely used by established sellers:\n\n\n\n* **Use TikTok Shop for awareness + content-driven sales:** Leverage its algorithm to make products go viral and drive impulsive sales, especially among the younger demographic.\n* **Use Shopee for mass market penetration:** Use its sheer volume and promotional power to capture the bulk of the price-sensitive market.\n* **Use Lazada for premium/bulkier items:** Utilize its robust logistics for higher-ticket, branded items where buyer trust and reliable delivery are paramount.\n\n## Selling beyond the marketplaces: your own store\n\nEvery platform above takes a commission plus a transaction fee on each order, and those rates move regularly. The fourth channel worth considering is one you own: your own online store, where there is no marketplace commission and you keep the customer relationship.\n\n[Catalog](https://catalog.billplz.com/) lets Malaysian sellers set up an online store or payment form without coding, with payments collected through Billplz (FPX, Wallet, Card, and Instalments). Your marketplace stores keep their own settlement; Catalog runs your direct channel separately.\n\n* **Keep your margins.** No per-order commission on direct sales; you pay payment processing fees, and Catalog has a free tier to start.\n* **Own your customer data.** On marketplaces, the platform owns the buyer relationship; on your store, you do.\n* **Share one link anywhere.** Put your store or payment form link in your TikTok bio, Instagram profile, and WhatsApp chats.\n\n## How do I choose the best e-commerce platform for my products?\n\nTo make the final decision, consider these 3â4 decision factors:\n\n1. **Product type \u0026 price point:** Does your product suit high-volume, low-margin, high-value, branded, or trend-driven, visual appeal?\n2. **Marketing ability:** Are you excellent at running ads and managing promotions, or are you skilled/willing to invest in creating video content and collaborating with creators?\n3. **Logistics needs:** Do you require robust, integrated fulfillment for bulky/delicate items, or are standard, affordable courier services sufficient for small parcels?\n4. **Target audience:** Are you selling to price-sensitive families, brand-conscious adults, or young, trend-following shoppers?\n\nEach marketplace handles its own payment settlement. To track earnings, review each platform's seller dashboard for payout schedules and transaction reports. If you also sell through your own website, [Catalog](https://catalog.billplz.com/) lets you set up an online store, while [Billplz](https://main.billplz.com/) handles payment forms and direct transactions, both with real-time tracking and local bank settlement.\n\n_Also read:_ [_Toyyibpay vs Billplz: Which payment gateway should you choose?_](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)\n\n---\n\n## FAQ\n\n### Which is more profitable for sellers: Lazada or Shopee?\n\nIt depends on your niche. Lazada may offer better margins for branded products, while Shopee provides higher sales volume for fast-moving or budget-friendly items.\n\n### Is TikTok Shop reliable in Malaysia?\n\nYes. TikTok Shop has rapidly scaled with growing user trust. It's effective for impulse buying and trending products, especially for fashion and beauty.\n\n### Can I use the same inventory across Lazada, Shopee, and TikTok Shop?\n\nYes, but youâll need to manage it carefully. Manual syncing or using a third-party inventory management system is recommended to avoid stock inconsistencies and overselling.\n\n### How can I manage payments across multiple platforms?\n\nEach marketplace handles its own payment settlement. To track earnings, review each platform's seller dashboard for payout schedules and transaction reports. If you also sell through your own website, a local payment gateway like Billplz can handle those transactions separately with real-time tracking and local bank settlement.\n\n### Which has faster delivery, Shopee or Lazada?\n\nBoth offer competitive delivery times, but they vary by product type and location. Shopee tends to be faster for smaller parcels via Shopee Xpress, while Lazadaâs logistics are more reliable for bulkier or premium items through Lazada Logistics.\n\n### Is Lazada or Shopee better in Malaysia?\n\nShopee dominates in user base and promotional reach, making it ideal for mass-market sellers. Lazada appeals more to mid-to-high-income customers and is better suited for branded goods and electronics.\n\n### Is it better to sell on TikTok or Shopee?\n\nIt depends on your marketing strengths. TikTok Shop is great for visual, trend-driven products and works well if you can leverage content creators. Shopee is better for high-volume sales and traditional product listings.\
1n\n---\n\n## Conclusion\n\nThe Malaysian e-commerce landscape is a dynamic triangle. There is no single âbestâ platform; the winning strategy depends on your products, budget, and target audience.\n\nSmart sellers should leverage the strengths of each platform: utilizing TikTok Shop for brand discovery and impulse buys, Shopee for mass market penetration, and Lazada for branded premium sales.\n\nWhichever mix you choose, each marketplace settles its own payments. For your own store or payment links, Catalog and Billplz run the direct channel with local bank settlement and real-time tracking.","__component":"shared.rich-text"}]},{"id":427,"documentId":"cx0acutlmrprt9tg1vfzt4ko","title":"Shopify payment gateway in Malaysia with local payment methods","slug":"shopify-payment-gateway-malaysia-local-payment-methods","createdAt":"2025-10-15T04:10:19.966Z","updatedAt":"2026-07-03T07:54:59.426Z","publishedAt":"2026-07-03T07:54:59.578Z","publishDate":"2025-10-15T04:10:19.966Z","cover":{"id":43,"documentId":"upwk1zeb764fot7udq3g08vc","name":"251015_05_01_img.webp","alternativeText":"Shopify payment gateway","caption":"Shopify payment gateway","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_05_01_img_2b3f284a51.webp","hash":"small_251015_05_01_img_2b3f284a51","mime":"image/webp","name":"small_251015_05_01_img.webp","path":null,"size":6.73,"width":500,"height":278,"sizeInBytes":6730},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_05_01_img_2b3f284a51.webp","hash":"medium_251015_05_01_img_2b3f284a51","mime":"image/webp","name":"medium_251015_05_01_img.webp","path":null,"size":11.02,"width":750,"height":417,"sizeInBytes":11018},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_05_01_img_2b3f284a51.webp","hash":"thumbnail_251015_05_01_img_2b3f284a51","mime":"image/webp","name":"thumbnail_251015_05_01_img.webp","path":null,"size":2.52,"width":245,"height":136,"sizeInBytes":2516}},"hash":"251015_05_01_img_2b3f284a51","ext":".webp","mime":"image/webp","size":18.2,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_05_01_img_2b3f284a51.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-22T06:28:01.511Z","updatedAt":"2025-10-22T06:28:30.207Z","publishedAt":"2025-10-22T06:28:01.511Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":154,"metaTitle":"Shopify payment gateway in Malaysia with local payment methods","metaDescription":"Power your Malaysian Shopify store with FPX, DuitNow, e-wallets, and BNPL. Discover how Billplz helps you lower fees, boost conversions, and simplify payments.","metaKeywords":"Shopify payment gateway Malaysia, Shopify Malaysia, local payment methods Malaysia, FPX Shopify, DuitNow Shopify, e-wallet Malaysia, Shopify Payments alternative, Malaysian payment gateway, Billplz Shopify integration","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_05_01_img_2b3f284a51.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Shopify payment gateway in Malaysia with local payment methods","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Power your Malaysian Shopify store with FPX, DuitNow, e-wallets, and BNPL. Discover how Billplz helps you lower fees, boost conversions, and simplify payments.","dateModified":"2026-01-02T01:07:17.908Z","datePublished":"2025-10-15T04:10:19.966Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods","@type":"WebPage"}}},"blocks":[{"id":402,"body":"**Key takeaways:**\n\n* Shopify Payments is not available in Malaysia, so merchants must use third-party payment gateways like Billplz, PayPal, or iPay88.\n* Local payment methods matter. Malaysian consumers prefer FPX, DuitNow, e-wallets, and BNPL over international options like PayPal or credit cards.\n* Billplz is a local payment gateway offering seamless Shopify integration, with flat-fee FPX plus Wallet, Card, and Instalments (BNPL) support. Current rates are on the [pricing page](https://main.billplz.com/pricing).\n* Using a local gateway improves conversion rates, lowers fees, and increases customer trust, thanks to familiar payment methods and faster settlements.\n* Setting up a gateway on Shopify is simple, and Billplz offers tools for real-time reconciliation, secure transactions, and trusted infrastructure.\n\n## Introduction\n\nShopify is one of the most widely used eCommerce platforms for businesses in Malaysia, offering a powerful and user-friendly way to build an online store. However, unlike in some other countries, Shopifyâs native payment processor, Shopify Payments, is **not available** in Malaysia.\n\nTo accept payments on Shopify, Malaysian merchants must integrate their stores with a third-party payment gateway such as PayPal, Stripe, Billplz, or iPay88. These gateways are essential bridges that process transactions securely.\n\nThis article explores how Malaysian Shopify stores can set up third-party gateways, why local payment methods matter, and why Billplz is one of the most trusted and cost-effective options available.\n\n## Why you need a third-party payment gateway in Malaysia\n\nBecause Shopify Payments is not available locally, a third-party payment gateway is a non-negotiable requirement for any Malaysian Shopify store that wants to process transactions.\n\nThese gateways are the engine that allows you to accept a wide variety of payment methods that Malaysian consumers know and trust, including credit/debit cards, popular e-wallets, and direct online bank transfers via FPX.\n\nWithout offering these familiar, local payment options, you risk a high rate of cart abandonment. Customers who don't see their preferred payment method are likely to leave your site and purchase from a competitor who does.\n\nIntegrating a reliable gateway ensures a smooth checkout experience, building customer confidence and boosting your sales.\n\n## Popular payment gateway options for Shopify Malaysia\n\nShopify merchants in Malaysia can choose from a range of international and local payment gateways.\n\n* Â **International gateways**: These include globally recognized names like [PayPal](https://www.paypal.com/), [Stripe](https://www.google.com/aclk?sa=L\u0026ai=DChsSEwjUzNjjx_-PAxUyLoMDHdo1G4oYACICCAEQABoCc2Y\u0026co=1\u0026ase=2\u0026gclid=Cj0KCQjw3OjGBhDYARIsADd-uX7IG35-oqnHvrceJgz2L5oQuKEwpkw4NN8xTaz_StJ7lpZ61JjEMZgaAl2vEALw_wcB\u0026cid=CAASQuRo4oY0vtO0YdFqh71BTx-Xkmh044E-T3JcihKb-l1fFyIWpPJfODacHijHicQ2g75jnNGG3LJ6cNqQL81Ly4y0lA\u0026cce=2\u0026category=acrcp_v1_32\u0026sig=AOD64_105kDGLOAeeODV2I4bwjzdQxsayg\u0026q\u0026nis=4\u0026adurl\u0026ved=2ahUKEwif7c3jx_-PAxXHwjgGHfYABcUQ0Qx6BAgLEAE), [Adyen](https://www.adyen.com/), and [WorldPay](https://www.worldpay.com/). They are excellent for businesses with a large international customer base, but can have higher fees and slower settlement times for Malaysian transactions.\n* **Local gateways**: These providers are specifically tailored for the Malaysian market. Key players include [Billplz](https://main.billplz.com/), ADAPTIS (formerly iPay88), GrabPay, and more. They excel in offering local payment methods like FPX and DuitNow QR, often with lower fees and faster payout schedules.\n\nWhile international gateways offer global reach, local gateways are often better suited to Malaysian shoppers. They provide faster settlements, lower fees, and support for payment methods Malaysians trust, like FPX and DuitNow.\n\n
1It's important to note that all transaction fees are charged by the payment gateway provider, not by Shopify.\n\n## Key considerations when choosing a gateway\n\nWhen selecting a payment gateway for your Shopify store in Malaysia, consider:\n\n* **Payment methods**: Ensure the gateway supports the methods your customers prefer. Choose a gateway that supports cards (Visa/Mastercard), FPX bank transfers, top e-wallets (GrabPay, Touch ân Go, Boost), and BNPL services.\n* **Fees**: Transaction fees can be either a flat rate per transaction or a percentage of the total sale amount. Carefully evaluate the fee structure to understand how it will impact your profit margins.\n* **Integration**: All official Shopify-approved providers offer seamless integration. The setup is typically straightforward and can be completed within your Shopify admin dashboard under Settings \u003e Payments.\n* **Settlement speed**: How quickly will you receive your money? Local gateways that process FPX and DuitNow payments often settle funds by the next business day. International gateways may take 3-7 business days or longer.\n* **Customer trust**: Malaysians are comfortable and familiar with local payment systems. Displaying these options at checkout can significantly increase customer trust and conversion rates compared to offering only international card options.\n\n## Local payment methods Malaysian shoppers prefer\n\nMalaysian consumers favour instant, secure, and familiar payment methods. These include:\n\n* [**FPX payments**](https://paynet.my/personal-fpx.html): The Financial Process Exchange (FPX) is a secure online payment system operated by [PayNet](https://paynet.my/index.html), Malaysia's national payments network. It allows customers to make payments by logging into their bank account, offering instant transfers with very low fees for merchants.\n* [**DuitNow**](https://www.duitnow.my/) **\u0026** [**DuitNow QR**](https://www.duitnow.my/QR/index.html): DuitNow enables instant, real-time fund transfers between bank accounts and e-wallets using just a mobile number or national ID. DuitNow QR provides a universal QR code that customers can scan with their preferred mobile banking or e-wallet app to make a payment.\n* **Wallets**: Digital wallets are extremely popular. The most widely used in Malaysia include DuitNow QR, [GrabPay](https://www.grab.com/my/pay/), [Touch ân Go eWallet](https://www.touchngo.com.my/ewallet?srsltid=AfmBOopv3VBIfLxqMLvLiMYuad0EIuqxirnpkWDpor5JmcgyFwpaSQQh), [Boost](https://myboost.co/), and [ShopeePay](https://shopeepay.com.my/en).\n* **BNPL providers**: Buy Now, Pay Later services like [Atome](https://www.atome.my/) and [Grab PayLater](https://www.grab.com/my/finance/pay-later/?gad_source=7) are gaining traction, allowing customers to split their purchases into interest-free installments.\n* **Debit \u0026 credit cards**: Visa and Mastercard remain a staple payment method. [MyDebit](https://paynet.my/personal-mydebit.html) is the national debit card scheme that allows for direct bank account deductions.\n\n### Benefits of using local payment gateways on Shopify\n\nChoosing a local payment gateway can give your Shopify store a strategic edge in the Malaysian market:\n\n* **Higher customer trust:** Presenting familiar payment options builds immediate credibility and increases adoption.\n* **Lower transaction fees:** Local gateways often have more competitive pricing, especially for FPX transactions, compared to the percentage-based fees of international providers.\n* **Faster settlements:** Quicker access to your funds significantly improves business cash flow.\n* **Support for local ecosystems:** These gateways are deeply integrated with Malaysian banks and e-wallet providers.\n* **Regulatory compliance:** Local gateways operate under the oversight of Bank Negara Malaysia (BNM) and adhere to the standards set by PayNet, ensuring security and compliance.\n\n_Also read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n\n## Shopify payment gateway: Local vs international options\n\nHereâs a quick side-by-side comparison of local and international gateways:\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eFeature\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eLocal Gateways\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eInternational Gateways\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003ePayment Methods\u003c/td\u003e\u003ctd\u003eFPX, DuitNow, local e-wallets, BNPL, cards\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003ePrimarily credit/debit cards, PayPal balance\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFees\u003c/td\u003e\u003ctd\u003eLower (often flat or local percentage rates)\u003c/td\u003e\u003ctd\u003eHigher (often USD-based with currency conversion charges)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eSettlement\u003c/td\u003e\u003ctd\u003eFast, often next business day (for FPX, DuitNow)\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eSlower, typically 3â7 days, potential for FX delays\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eCustomer Trust\u
1003c/td\u003e\u003ctd\u003eHigh, due to familiarity with local methods\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u0026nbsp;\u003c/td\u003e\u003ctd\u003eModerate, as not all Malaysians use PayPal or Stripe\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## Why use Billplz as a Shopify payment gateway in Malaysia?\n\n[Billplz](https://main.billplz.com/) is designed specifically for the Malaysian market, offering merchants a seamless, locally optimized solution for accepting online payments. It is trusted by businesses across industries for its cost-effectiveness, reliability, and support for all major Malaysian payment methods.\n\nHere are the **top 3 reasons** Billplz is ideal for your Shopify store:\n\n* **Specialises in Malaysian payment methods**: Billplz supports FPX, DuitNow QR, e-wallets, and card payments â giving customers the flexibility to pay the way they prefer.\n* **Flat FPX fee**: Billplz charges a flat fee per successful FPX transaction, with no percentage cut of your sale. Current rates are on the [pricing page](https://main.billplz.com/pricing).\n* **Easy Shopify integration**: Setup is quick and straightforward, just enter your credentials, and you're ready to go in minutes.\n\nBeyond the top advantages, Billplz also supports BNPL and major Malaysian e-wallets, giving customers more ways to pay and reducing the chances of abandoned checkouts.\n\nIts real-time dashboard simplifies payment tracking and reconciliation, while transparent pricing and 99.9% historical uptime help keep your store running smoothly.\n\nIn short, Billplz isnât just a payment gateway. Itâs a complete payment solution tailored for Malaysian businesses on Shopify.\n\n_Also read:_ [_BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026Â offerings_](https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz)\n\n## Conclusion\n\nIf you're running a Shopify store in Malaysia, integrating a third-party payment gateway is essential. While international gateways have their place, local providers offer lower fees, faster payouts, and greater customer trust.\n\nTo win more customers and reduce checkout abandonment, offering local payment methods like FPX, DuitNow, and BNPL is no longer optional, itâs expected.\n\nWith its simple integration, low fees, and trusted local infrastructure, Billplz is the smart solution for Shopify merchants who want to accept payments the Malaysian way.","__component":"shared.rich-text"}]},{"id":503,"documentId":"w04etyfq69at6lupt94qkt4n","title":"BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings","slug":"bnpl-malaysia-comparison-integration-billplz","createdAt":"2025-10-15T03:56:39.198Z","updatedAt":"2026-07-17T05:02:02.271Z","publishedAt":"2026-07-17T05:02:02.395Z","publishDate":"2025-10-15T03:56:39.198Z","cover":{"id":48,"documentId":"vq5h3bzi6zb1sd4vj87a07lw","name":"251015_08_01_img.webp","alternativeText":"BNPL Malaysia \u0026 Billplz","caption":"BNPL Malaysia \u0026 Billplz","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_08_01_img_01c22287f8.webp","hash":"small_251015_08_01_img_01c22287f8","mime":"image/webp","name":"small_251015_08_01_img.webp","path":null,"size":10.32,"width":500,"height":278,"sizeInBytes":10322},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_08_01_img_01c22287f8.webp","hash":"medium_251015_08_01_img_01c22287f8","mime":"image/webp","name":"medium_251015_08_01_img.webp","path":null,"size":16.27,"width":750,"height":417,"sizeInBytes":16270},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_08_01_img_01c22287f8.webp","hash":"thumbnail_251015_08_01_img_01c22287f8","mime":"image/webp","name":"thumbnail_251015_08_01_img.webp","path":null,"size":3.64,"width":245,"height":136,"sizeInBytes":3644}},"hash":"251015_08_01_img_01c22287f8","ext":".webp","mime":"image/webp","size":23.54,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_08_01_img_01c22287f8.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-22T14:28:57.566Z","updatedAt":"2025-10-23T06:31:33.432Z","publishedAt":"2025-10-22T14:28:57.566Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44
1:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":230,"metaTitle":"BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings","metaDescription":"Explore Malaysiaâs top BNPL providers, how Buy Now Pay Later works, and how Billplz simplifies BNPL integration for businesses with seamless checkout and tracking.","metaKeywords":"BNPL Malaysia, Buy Now Pay Later, Atome Malaysia, Grab PayLater, Shopee SPayLater, Boost PayFlex, installment payment Malaysia, BNPL comparison, BNPL integration, payment installment Malaysia","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_08_01_img_01c22287f8.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"Explore Malaysiaâs top BNPL providers, how Buy Now Pay Later works, and how Billplz simplifies BNPL integration for businesses with seamless checkout and tracking.","dateModified":"2026-07-17T05:02:00.299Z","datePublished":"2025-10-15T03:56:39.198Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/bnpl-malaysia-comparison-integration-billplz","@type":"WebPage"}}},"blocks":[{"id":478,"body":"**Key takeaways:**\n\n* BNPL (Buy Now, Pay Later) is a fast-growing payment method in Malaysia, with over RM7.1 billion spent in H2 2024 by more than 5 million users.\n* It allows customers to split payments into instalments, often interest-free, making it ideal for both essential and discretionary purchases.\n* Major BNPL players in Malaysia include Atome, Grab PayLater, Shopee SPayLater, Boost PayFlex, and others: each offering unique features and plans.\n* BNPL helps businesses boost sales, increase Average Order Value (AOV), reduce cart abandonment, and reach credit-averse customers.\n* Compared to traditional methods like FPX, credit cards, and e-wallets, BNPL offers unmatched flexibility for consumers.\n* Billplz integrates with top BNPL providers, enabling businesses to offer BNPL at checkout with a centralised dashboard, real-time tracking, and simplified payout management.\n* Billplzâs platform is scalable, secure, easy to integrate, and trusted by businesses across retail, healthcare, education, and travel industries.\n\n## Introduction\n\nBuy Now, Pay Later (BNPL) has quickly become a popular way to pay in Malaysia. What started as a niche option is now widely used, especially by those who prefer flexible payment plans over traditional credit cards.\n\nIn the second half of 2024 alone, more than 5.1 million Malaysians used BNPL services, spending over RM7.1 billion (Source: [5.1 Million Malaysians Now Use BNPL, Most Earning Below RM5,000](https://fintechnews.my/48573/fintech-lending-malaysia/malaysia-bnpl/)).\n\nItâs no longer just for luxury items. Many people now rely on BNPL for everyday needs and unexpected expenses.\n\nIn this guide, weâll explain how BNPL works in Malaysia, compare the top providers, and show how Billplz helps businesses easily integrate BNPL into their checkout process for a smoother, smarter experience.\n\n## What is Buy Now, Pay Later (BNPL)?\n\nBNPL is a short-term financing option that allows consumers to make a purchase immediately and defer the payment, typically splitting the cost into a series of smaller, manageable instalments over a short period (usually 3 to 6 months).\n\nSome plans are interest-free, while others may include small service fees depending on the duration and provider.\n\n### How BNPL works?\n\nBNPL simplifies the purchasing process by breaking payments into instalments while ensuring merchants get paid upfront. Here's how it works:\n\n1. **Customer selects BNPL at checkout:** The shopper chooses a BNPL provider (e.g., Atome or Grab PayLater) as their payment option.\n2. **Customer pays in instalments:** The customer pays the BNPL provider in staggered, scheduled payments, often interest-free if they meet all deadlines.\n3. **Merchant receives upfront payment:** The business receives the full transaction amount immediately from the BNPL provider, minus a transaction fee. The merchant assumes zero credit risk associated with the customer's repayments.\n\nBusinesses, both online and physical, are quickly adopting BNPL for powerful commercial advantages:\n\n* **Boost sales conversion:** Offering flexible payment options significantly reduces purchase hesitation, making customers more likely to complete a transaction.\n* **Increase AOV (Average Order Value):** When the total price is broken into smaller chunks (e.g., RM400 becomes 4 monthly payments of RM100), shoppers feel more comfortable buying more, leading to higher basket sizes.\n* **Reduce cart abandonment:** The ability to instantly defer payment overcomes cost barriers at the final checkout stage.\n\n## BNPL in Malaysia â Current landscape\n\nBNPL is now a mainstream financial tool in Malaysia, especially among Gen Z and millennials seeking flexibility over credit cards.\n\n* **Adoption and growth** \n With millions of active users, Malaysia is one of Southeast Asia's fastest-growing BNPL markets. The sheer volume of transactions (RM7.1 billion in H2 2024) demonstrates its market penetration.\n* **Rising consumer demand** \n Demand is high, not just for discretionary spending but also for essentials like groceries, medical bills, and school supplies. BNPL acts as a crucial financial tool for consumers managing liquidity between paychecks. \n Surveys show that BNPL has enabled 63% of users to shift away from riskier informal lenders (Source: [Top 3 BNPLs in Malaysia and Whatâs Next for the Market in 2025](https://fintechnews.my/top-3-bnpls-in-malaysia-and-whats-next-for-the-market/)).\n* **Regulatory environment** \n The proliferation of BNPL services has attracted the attention of regulators. Bank Negara Malaysia (BNM) is actively monitoring the digital credit landscape. \n Crucially, the [Consumer Credit Act](https://ccob.my/wp-content/uploads/2023/04/CP2-Sl
1ides-Summary_110423.pdf) (tabled in 2025) will require all Buy Now, Pay Later (BNPL) providers to be licensed and regulated by the new Consumer Credit Commission. This ensures stronger consumer protection and oversight.\n\n## Popular BNPL providers in Malaysia\n\n*  [**Atome**](https://www.atome.my/) offers 3, 6, or 12-month instalment plans, with some carrying a 1.5% monthly fee. Many merchants offer interest-free options. Itâs widely used in fashion, beauty, lifestyle, fitness, and travel, and includes the Atome+ rewards programme for cashback and promotions.\n* [**Grab PayLater**](https://www.grab.com/my/finance/pay-later/) allows users to split purchases into 4, 8, or 12-month instalments, or consolidate into a single monthly bill. Itâs integrated across the Grab ecosystem (rides, food, shopping) and offers up to 1.5x GrabRewards points on eligible payments.\n* [**Shopee SPayLater**](https://www.google.com/aclk?sa=L\u0026ai=DChsSEwirgvewuv2PAxW5K4MDHdwyEv8YACICCAEQABoCc2Y\u0026co=1\u0026ase=2\u0026gclid=Cj0KCQjw3OjGBhDYARIsADd-uX5fw1s1gWTBB64v5xX5pJG-TveEi7sMs4DeG1oOZ9_fWMi826pwFt8aAnTAEALw_wcB\u0026cid=CAASQuRo39CHHAuumt7aha6ZwXUKIhtMPy3xVSXm_WjQPfrrDzX6MrFmRqhmtvidrmR2jpDILASs_HvPsOdKKrKDo87Q4w\u0026cce=2\u0026category=acrcp_v1_32\u0026sig=AOD64_1XMYT5qPEmLlLzvrl1fItz7eVVRQ\u0026q\u0026nis=4\u0026adurl\u0026ved=2ahUKEwiYxO-wuv2PAxV6yzgGHd5cC3AQ0Qx6BAgYEAE) provides flexible plans from 1 to 24 months, is fully integrated with Shopee and ShopeePay, and is Shariah-compliant. Users can pay via cards, ShopeePay, online banking, or cash.\n* [**Boost PayFlex**](https://myboost.co/feature/boost-payflex) is a Shariah-compliant BNPL solution that stands out for its extensive reach, allowing users to make payments in up to 24-month instalments at over 1.8 million DuitNow QR merchants nationwide, as well as for utility bills and e-wallet top-ups.\n* Other providers like [PAYLATER Malaysia](https://www.paylater.com.my/) and [Moby](https://moby.my/) also offer flexible BNPL options across local and regional retailers.\n\nHereâs a quick side-by-side comparison of Malaysiaâs top BNPL providers, their features, and where they shine.\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eProvider\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eInstalment options\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eInterest\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eKey features\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003ePopular use case\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eAtome\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e3, 6, or 12 months\u003c/td\u003e\u003ctd\u003eSome plans with 1.5% fee; many are interest-free\u003c/td\u003e\u003ctd\u003eAtome+ rewards; strong presence in fashion, beauty, lifestyle, travel\u003c/td\u003e\u003ctd\u003eRetail, fashion, lifestyle\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eGrab PayLater\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e4, 8, or 12 months; or a monthly bill\u003c/td\u003e\u003ctd\u003eInterest-free\u003c/td\u003e\u003ctd\u003eIntegrated into Grab (rides, food, shopping); up to 1.5x GrabRewards\u003c/td\u003e\u003ctd\u003eTransport, food delivery, and eCommerce\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eShopee SPayLater\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e1 to 24 months\u003c/td\u003e\u003ctd\u003eInterest may apply (varies)\u003c/td\u003e\u003ctd\u003eShariah-compliant; linked to Shopee \u0026amp; ShopeePay; multiple payment methods\u003c/td\u003e\u003ctd\u003eOnline shopping via Shopee\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eBoost PayFlex\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eUp to 24 months\u003c/td\u003e\u003ctd\u003eNot specified\u003c/td\u003e\u003ctd\u003eShariah-compliant; accepted at 1.8M+ DuitNow QR merchants; supports bills \u0026amp; top-ups\u003c/td\u003e\u003ctd\u003eBill payments, offline shopping, e-wallet top-ups\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\n## Benefits of BNPL for businesses\n\nImplementing BNPL offers merchants tangible, immediate advantages that go beyond just flexible payments:\n\n* **Increased sales conversion**: By removing the immediate financial hurdle, customers are more likely to finalize their purchase.\n* **Higher basket size**: Splitting payments encourages shoppers to add more items to their cart, significantly boosting the Average Order Value (AOV).\n* **Customer loyalty**: Providing flexible and accommodating payment options enhances the customer experience, fostering trust and encouraging repeat buying.\n* **Instant payout**: The business receives the full transaction amount upfront, ensuring healthy cash flow without exposure to instalment or default risk.\n* **Access to new customer segments**: BNPL appeals to younger, credit-averse consumers who may not use credit cards, helping merchants tap into previously underserved demographics.\n* **Reduced cart abandonment**: Offering BNPL at checkout can reduce friction in the buying process, lowering abandonment rates, especially for high-ticket items.\n* **Marketing \u0026 discovery opportunities**: Being listed on BNPL providersâ platforms (e.g., Atome or Grab PayLater) gives merchants exposure to millions of active users.\n\n## BNPL vs traditional payment methods\n\nHow does BNPL stack up against common payment methods like credit cards, FPX, and e-wallets?\n\n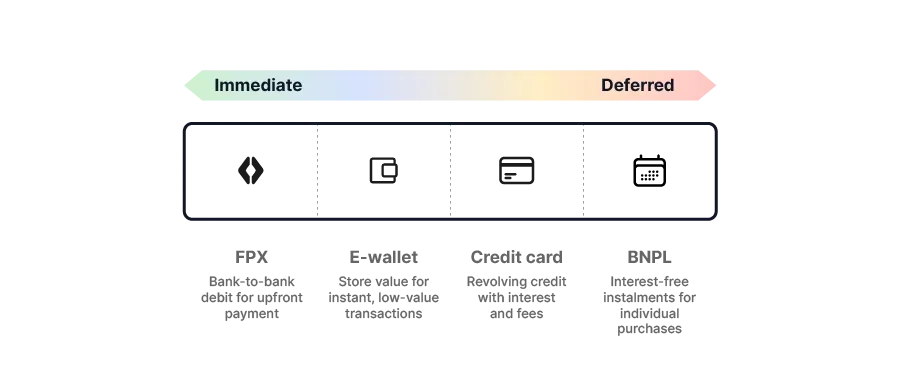\n\nHereâs a quick comparison to help businesses and consumers understand the differences.\n\n### BNPL vs Credit cards\n\nBNPL offers short-term, interest-free instalments (e.g., 4 payments over 6 weeks) tied to individual purchases. It's easy to access, requiring only a soft credit check and appeals to those who prefer flexible, low-risk budgeting tools.\n\nCredit cards, by contrast, are revolving credit lines that allow ongoing borrowing but often come with high interest rates, annual fees, and stricter approval (usually based on credit score). Theyâre valued for universal acceptance, rewards, and credit-building potential.\n\nBNPL is ideal for simplicity and short-term purchases, while credit cards offer more flexibility for ongoing spending and consumer protections.\n\n### BNPL vs FPX\n\n[FPX (Financial Process Exchange)](https://paynet.my/personal-fpx.html) is an immediate bank-to-bank debit, making it a definitive, upfront payment method. BNPL, conversely, is a deferred/split payment, introducing crucial flexibility that FPX cannot offer. \n\nWhile FPX is excellent for immediate settlement and often has lower merchant fees, it does not help customers manage large-ticket purchases.\n\n_For more information on FPX, read:_ [_FPX payment for business: How it works, guides, \u0026 our solutions_](https://main.billplz.com/blog/fpx-payment-malaysia-business-guide)\n\n### BNPL vs E-wallets\n\nE-wallets like [Touch ân Go eWallet](https://www.touchngo.com.my/ewallet?srsltid=AfmBOorNFSwXNF0AwuvVMGAWnB7PqA5e9t3TXDc9AR0ItODdoMAi66Gu) and [ShopeePay](https://shopeepay.com/) are primarily used for daily, low-value transactions, acting as a convenient way to store value or transfer funds instantly. BNPL extends actual credit for higher-value, non-essential purchases, targeting a different c
1onsumer spending behavior.\n\nThe key takeaway is that BNPL complements, not replaces, traditional methods. It is a specialized tool used to unlock high-value purchases that a customer might otherwise abandon.\n\n## Billplz BNPL integrations\n\n[Billplz](https://main.billplz.com/) serves as the unified platform that simplifies digital payment acceptance for Malaysian businesses. By integrating with leading BNPL providers like Atome and Grab PayLater, Billplz ensures that you can offer these high-demand payment options without managing multiple separate vendor accounts.\n\nThrough [Billplz integrations](https://main.billplz.com/integrations), businesses gain powerful features:\n\n* **Centralised dashboard**: Manage and reconcile all payment channels like BNPL, FPX, DuitNow, and cards from a single, unified dashboard.\n* **Seamless checkout experience**: Customers enjoy a clean, frictionless checkout, automatically routed to their chosen BNPL provider upon selection.\n* **Real-time tracking of BNPL transactions**: Monitor BNPL transaction status instantly alongside all other payment methods.\n* **Payout management simplified**: Billplz handles the complex settlement process with the BNPL provider, ensuring funds are transferred to your bank account quickly and clearly.\n\n### Why choose Billplz for BNPL payments?\n\nAs a leading Malaysian payment gateway, [Billplz](https://main.billplz.com/) is uniquely positioned to help local businesses adopt BNPL seamlessly by integrating it directly into its existing robust payment infrastru
1cture.\n\n* **One platform, multiple methods**: Billplz offers a full-stack solution supporting all major payment methods in Malaysia, including FPX, DuitNow, cards, and now, essential BNPL options.\n* **Transparent pricing**: Benefit from Billplzâs transparent pricing model, featuring flat fees and clear settlement terms, allowing for easy cost management.\n* **Easy integration**: Utilize existing Billplz APIs and plugins for popular platforms (Shopify, WooCommerce, etc.) to integrate BNPL with minimal technical effort.\n* **Scalable for SMEs to enterprise**: The platform is built to support businesses of all sizes, from small online sellers to large corporate merchants.\n* **Trusted infrastructure**: Rely on a proven platform with high reliability, featuring 99.9% uptime and backed by PayNet-endorsed infrastructure.\n\n_Also read:_ [_PayNet Malysia: All you need to know about Malaysia's payment network_](https://main.billplz.com/blog/insights/paynet-malaysia-payment-network-guide)\n\n---\n\n## FAQ\n\n### Why has BNPL become popular among consumers?\n\nBNPL offers instant gratification, zero-interest instalments, and budget-friendly flexibility, especially appealing for younger consumers and households managing cash flow between paychecks.\n\n### Is BNPL safe for businesses?\n\nYes, BNPL is very safe for businesses. When a customer selects BNPL, the provider assumes the credit risk. The merchant receives the full purchase amount upfront (minus the merchant fee) from the BNPL provider, regardless of whether the customer completes their instalments.\n\n### How much does BNPL cost merchants compared to FPX?\n\nBNPL typically comes with higher fees than FPX, due to the credit risk and infrastructure involved. However, these are offset by increased sales and order values.\n\n### What are some challenges \u0026 considerations in BNPL?\n\nSome challenges and considerations include:\n\n* **Consumer Overspending Concerns**: BNPL's accessibility raises regulatory concerns about customers falling into debt cycles if not used responsibly.\n* **Merchant Fees**: The processing fees are generally higher than traditional payment options like FPX.\n* **Regulatory Developments in Malaysia**: Businesses must be prepared for the upcoming Consumer Credit Act, which will formalize regulation and oversight.\n* **Choosing the Right BNPL Partner**: Selecting partners whose user base aligns with your product category is crucial.\n\n### How does BNPL benefit eCommerce businesses in Malaysia?\n\nIt leads to higher conversion rates for expensive items, enables significantly larger Average Order Value (AOV), and is highly effective in reducing cart abandonment by lowering the initial financial commitment.\n\n### Can retail stores in Malaysia use BNPL with Billplz?\n\nYes! Through Billplz integrations, retail stores (online or in-person) can easily offer BNPL via supported terminals or platforms.\n\n### What industries in Malaysia benefit most from BNPL adoption?\n\n1. **E-commerce \u0026 retail**: The biggest beneficiaries, seeing higher conversion and bigger basket sizes for general goods, electronics, and fashion.\n2. **Education \u0026 training**: Allows students or parents to pay tuition or course fees in manageable monthly instalments.\n3. **Healthcare \u0026 aesthetics**: Makes treatments, dental procedures, or aesthetic packages more accessible by splitting large, often unexpected, costs.\n4. **Travel \u0026 lifestyle**: Enables customers to book flights, packages, or large purchases like electronics and pay for them over time.\n\n---\n\n## Conclusion\n\nThe evolution of consumer credit in Malaysia shows that BNPL is no longer an optional payment add-on; it is a key driver for both online and offline sales growth. With this flexibility, businesses can capture a massive segment of the market that demands convenient, short-term credit solutions.\n\nBillplz simplifies this integration, offering businesses one unified platform to manage all their payment methods efficiently.\n\nChoosing Billplz means delivering modern, flexible payment options to your customersâwhile ensuring transparency, streamlined reconciliation, and operational efficiency for your business.","__component":"shared.rich-text"}]},{"id":490,"documentId":"to0n67zjpiw17vgyyr258onm","title":"MCC code lookup: find your merchant category code","slug":"merchant-category-codes-mcc-what-are-they-lookup-guide","createdAt":"2025-10-15T03:34:55.969Z","updatedAt":"2026-07-08T13:15:39.052Z","publishedAt":"2026-07-08T13:15:39.161Z","publishDate":"2025-10-15T03:34:55.969Z","cover":{"id":70,"documentId":"sv3jrqke9by84huqzyg2vfsx","name":"251015_04_01_img.webp","alternativeText":null,"caption":null,"width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_04_01_img_3f7a121747.webp","hash":"small_251015_04_01_img_3f7a121747","mime":"image/webp","name":"small_251015_04_01_img.webp","path":null,"size":5.07,"width":500,"height":278,"sizeInBytes":5066},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_04_01_img_3f7a121747.webp","hash":"medium_251015_04_01_img_3f7a121747","mime":"image/webp","name":"medium_251015_04_01_img.webp","path":null,"size":7.64,"width":750,"height":417,"sizeInBytes":7644},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_04_01_img_3f7a121747.webp","hash":"thumbnail_251015_04_01_img_3f7a121747","mime":"image/webp","name":"thumbnail_251015_04_01_img.webp","path":null,"size":2.28,"width":245,"height":136,"sizeInBytes":2278}},"hash":"251015_04_01_img_3f7a121747","ext":".webp","mime":"image/webp","size":10.01,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_04_01_img_3f7a121747.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-26T06:26:35.858Z","updatedAt":"2025-10-26T06:26:35.858Z","publishedAt":"2025-10-26T06:26:35.859Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44
1:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":217,"metaTitle":"MCC code lookup: find your merchant category code","metaDescription":"Look up your MCC in our table of common merchant category codes for Malaysian businesses, see how codes affect card fees, and check yours in 3 steps.","metaKeywords":"Merchant Category Code, MCC code, MCC lookup, credit card classification, interchange fees, merchant classification, payment processing codes, MCC code list, business category codes, card payment categorization","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_04_01_img_3f7a121747.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"MCC code lookup: find your merchant category code","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Look up your MCC in our table of common merchant category codes for Malaysian businesses, see how codes affect card fees, and check yours in 3 steps.","dateModified":"2026-07-08T13:14:18.329Z","datePublished":"2025-10-15T03:34:55.969Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/merchant-category-codes-mcc-what-are-they-lookup-guide","@type":"WebPage"}}},"blocks":[{"id":465,"body":"**Key takeaways:**\n\n* Merchant Category Codes (MCCs) are 4-digit numbers used by card networks to classify businesses by industry type for transactions.\n* MCCs affect interchange fees, credit card rewards, tax reporting, and payment restrictions.\n* They are assigned by acquiring banks or payment processors based on a merchant's primary business activity.\n* Misclassification can lead to higher fees or missed rewards; changing an MCC can be complex and requires approval.\n* Common use cases include cashback categorization, expense tracking, and compliance with tax reporting standards.\n* Businesses can look up MCCs through card network documents, payment gateway dashboards, or by contacting their acquirer.\n* To confirm your MCC, ask your acquiring bank or payment processor: they assign the code to your merchant account.\n\n## Introduction\n\nEvery time a customer pays with a credit or debit card, the transaction is tagged with a four-digit number known as a Merchant Category Code (MCC). These codes classify businesses based on the goods or services they offer and play a significant role in how card payments are processed.\n\nFor businesses, the assigned MCC is a foundational element that determines the cost of accepting card payments. For card networks and financial institutions, MCCs are essential for risk management and tracking spending. For consumers, MCCs directly influence the rewards and benefits they earn.\n\nIn this guide, we'll explain what MCCs are, detailing their use cases and showing how businesses can look them up to better manage their payment operations.\n\n## What Are Merchant Category Codes (MCCs)?\n\nAn MCC is a **four-digit number** assigned by major card networks, such as [Visa](https://www.visa.com.my/), [Mastercard](https://www.mastercard.com.my/en-my.html), and [American Express](https://www.americanexpress.com/). These codes are based on the [ISO 18245](https://www.iso.org/obp/ui/es/#iso:std:iso:18245:ed-2:v1:en) standard that functions as a universal tag for classifying a merchant's primary business activity.\n\nTheir purpose is to precisely identify the exact type of goods or services offered, which is then passed along with every card transaction.\n\nFor example, the code 5411 is used to designate Grocery Stores and Supermarkets, while 5812 is the specific MCC for Eating Places and Restaurants.\n\n_Also read: Paynet Malaysia:_ [_All you need to know about Malaysia's payment network_](https://main.billplz.com/blog/insights/paynet-malaysia-payment-network-guide)\n\n## Why are MCCs important?\n\nMCCs serve a crucial purpose by standardizing transaction data, which impacts compliance, risk, and profitability across the entire payment chain.\n\n* Â **For businesses:** The MCC primarily affects interchange fees, which are the non-negotiable fees a merchant pays to accept a card. High-risk or specialized MCCs may have higher or lower fees, directly impacting a businessâs processing costs and profit margins. It also helps determine tax reporting obligations.\n* **For banks \u0026 payment processors:** MCCs help acquirers and issuers track spending patterns, manage risk, and identify high-risk merchants who may be prone to higher fraud or chargeback rates. Issuers also use MCCs to set spending controls or restrictions on corporate and personal cards. Â \n* **For consumers:** The MCC is the trigger for rewards, cashback categories, and card benefits. If your card offers a bonus on \"gas,\" the transaction must carry the corresponding gas station MCC to qualify. Â \n* **For regulators:** Bank Negara Malaysia (BNM) uses Merchant Category Codes (MCCs) to regulate payment systems under the Payment Card Framework (PCF). MCCs help categorize merchants to control domestic interchange fees, assigning lower rates to sectors like government services, taxes, petrol stations, and charities. This promotes electronic payments, supports economic monitoring, and helps manage financial risks within the payments ecosystem.\n\n## Common use cases of MCCs\n\nThe standardized nature of Merchant Category Codes (MCCs) makes them invaluable across the financial ecosystem for categorizing merchant types.\n\n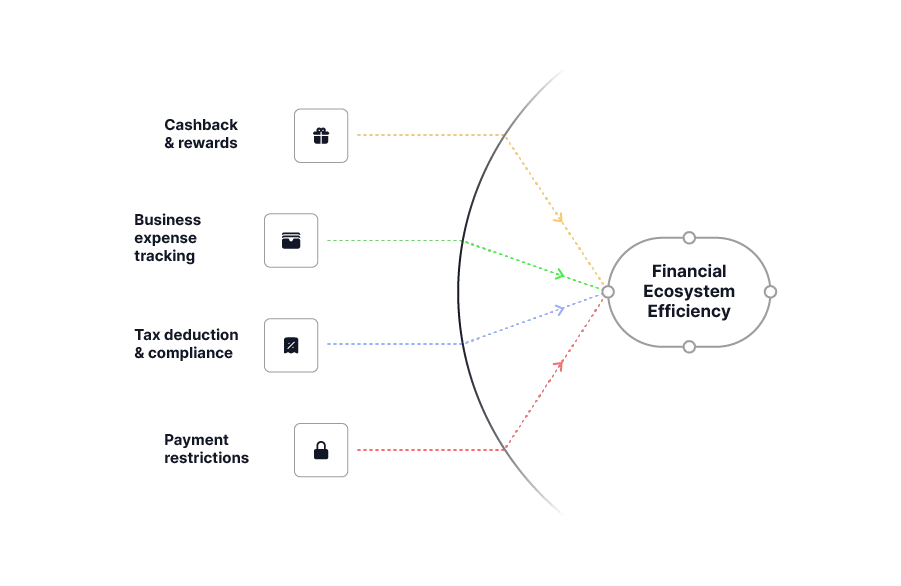\n\nHere are some of the most common uses:\n\n* **Cashback \u0026 rewards:** MCCs determine whether a transaction qualifies for bonus points or cashback offers (e.g., ensuring a transaction carries the Restaurants MCC (5812) to get a dining reward). Â \n* **Business expense tracking:** Companies use MCCs to automatically sort expenses in accounting software, which streamlines bookkeeping and financial reconciliation. Â \n* **Tax deduction \u0026 compliance:** They help identify whether a payment is for services versus merchandise, assisting businesses in meeting specific tax reporting requirements (like filing a Form 1099). Â \n* **Payment restrictions:** Card issuers implement spending controls using MCCs, allowing them to block high-risk transactions (e.g., gambling) or restrict a card's use to a specific category (e.g., travel expenses only).\n\n## How are MCCs assigned?\n\nMCCs are not self-assigned by the merchant.\n\nThe code is assigned by the acquiring bank or payment processor (the institution that manages the merchant's account) when the merchant account is first opened.\n\nThis assignment is based on the merchantâs primary business activity as declared on their application. Once assigned, the unique 4-digit code is transmitted as part of the transaction data for every card payment accepted.\n\n### MCC codes and interchange fees\n\nThe relationship between your MCC and payment costs directly impacts your business's bottom line. The MCC is the key factor that determines the interchange fee: the transaction cost you pay to accept a card.\n\nCard networks establish varying fee schedules based on the perceived risk of the business type. Merchants with MCCs associated with lower fraud or chargeback rates often qualify for lower interchange fees.\
1n\nConversely, high-risk or specialized MCCs incur higher rates. For instance, **Charitable Organizations (MCC 8398)** typically benefit from lower, preferential fees due to the low-risk nature of their transactions.\n\n## How to check your MCC code\n\nYou can confirm your business's MCC in three steps:\n\n1. **Ask your acquiring bank or payment processor.** They assigned the code to your merchant account and can confirm the exact MCC on file. This is the most reliable method.\n2. **Check your payment gateway dashboard.** Some platforms show the MCC in transaction reports or account settings.\n3. **Cross-check the official card network lists.** Visa and Mastercard publish the full MCC listings, such as the [Visa Merchant Data Standards Manual](https://usa.visa.com/content/dam/VCOM/download/merchants/visa-merchant-data-standards-manual.pdf).\n\n## MCC code lookup table for Malaysian businesses\n\nThe table below covers the codes most common among Malaysian businesses and organizations, grouped by industry. Use your browser's find function (Ctrl+F or Cmd+F) to search it. Descriptions follow the Visa Merchant Data Standards Manual (April 2026 edition).\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eGroup\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eMCC\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eOfficial description\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eMalaysian examples\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5411\u003c/td\u003e\u003ctd\u003eGrocery Stores and Supermarkets\u003c/td\u003e\u003ctd\u003eSupermarkets, mini markets, kedai runcit (Mydin, 99 Speedmart)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5499\u003c/td\u003e\u003ctd\u003eMiscellaneous Food Stores: Convenience Stores and Specialty Markets\u003c/td\u003e\u003ctd\u003eConvenience stores (7-Eleven, myNEWS), specialty food shops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5651\u003c/td\u003e\u003ctd\u003eFamily Clothing Stores\u003c/td\u003e\u003ctd\u003eFamily clothing stores, baju kurung and baju Melayu boutiques\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5661\u003c/td\u003e\u003ctd\u003eShoe Stores\u003c/td\u003e\u003ctd\u003eShoe stores\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5732\u003c/td\u003e\u003ctd\u003eElectronics Stores\u003c/td\u003e\u003ctd\u003eElectronics and gadget stores, phone shops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5734\u003c/td\u003e\u003ctd\u003eComputer Software Stores\u003c/td\u003e\u003ctd\u003eSoftware and IT licence sellers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5712\u003c/td\u003e\u003ctd\u003eFurniture, Home Furnishings, and Equipment Stores, Except Appliances\u003c/td\u003e\u003ctd\u003eFurniture and home furnishing stores\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5251\u003c/td\u003e\u003ctd\u003eHardware Stores\u003c/td\u003e\u003ctd\u003eHardware stores\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5944\u003c/td\u003e\u003ctd\u003eJewelry Stores, Watches, Clocks, and Silverware Stores\u003c/td\u003e\u003ctd\u003eJewellery and gold shops (Poh Kong, Habib)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5941\u003c/td\u003e\u003ctd\u003eSporting Goods Stores\u003c/td\u003e\u003ctd\u003eSporting goods stores\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5942\u003c/td\u003e\u003ctd\u003eBook Stores\u003c/td\u003e\u003ctd\u003eBookstores (Popular, MPH)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eRetail \u0026amp; grocery\u003c/td\u003e\u003ctd\u003e5999\u003c/td\u003e\u003ctd\u003eMiscellaneous and Specialty Retail Shops\u003c/td\u003e\u003ctd\u003eSpecialty retail without a more specific code (gift shops, pet shops, florists)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFood \u0026amp; beverage\u003c/td\u003e\u003ctd\u003e5812\u003c/td\u003e\u003ctd\u003eEating Places and Restaurants\u003c/td\u003e\u003ctd\u003eRestaurants, kedai makan, mamak, cafes\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFood \u0026amp; beverage\u003c/td\u003e\u003ctd\u003e5814\u003c/td\u003e\u003ctd\u003eFast Food Restaurants\u003c/td\u003e\u003ctd\u003eFast food outlets\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFood \u0026amp; beverage\u003c/td\u003e\u003ctd\u003e5462\u003c/td\u003e\u003ctd\u003eBakeries\u003c/td\u003e\u003ctd\u003eBakeries and cake shops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFood \u0026amp; beverage\u003c/td\u003e\u003ctd\u003e5811\u003c/td\u003e\u003ctd\u003eCaterers\u003c/td\u003e\u003ctd\u003eCaterers for events and kenduri\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eServices\u003c/td\u003e\u003ctd\u003e7230\u003c/td\u003e\u003ctd\u003eBeauty and Barber Shops\u003c/td\u003e\u003ctd\u003eBeauty s
1alons and barbershops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eServices\u003c/td\u003e\u003ctd\u003e7211\u003c/td\u003e\u003ctd\u003eLaundries: Family and Commercial\u003c/td\u003e\u003ctd\u003eLaundry and dry cleaning services\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eServices\u003c/td\u003e\u003ctd\u003e7699\u003c/td\u003e\u003ctd\u003eMiscellaneous Repair Shops and Related Services\u003c/td\u003e\u003ctd\u003eGeneral repair shops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eServices\u003c/td\u003e\u003ctd\u003e7221\u003c/td\u003e\u003ctd\u003ePhotographic Studios\u003c/td\u003e\u003ctd\u003ePhotography studios (weddings, portraits)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eServices\u003c/td\u003e\u003ctd\u003e7338\u003c/td\u003e\u003ctd\u003eQuick Copy, Reproduction, and Blueprinting Services\u003c/td\u003e\u003ctd\u003ePhotocopy and quick-print shops\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eProfessional services\u003c/td\u003e\u003ctd\u003e8111\u003c/td\u003e\u003ctd\u003eLegal Services and Attorneys\u003c/td\u003e\u003ctd\u003eLaw firms\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eProfessional services\u003c/td\u003e\u003ctd\u003e8931\u003c/td\u003e\u003ctd\u003eAccounting, Auditing, and Bookkeeping Services\u003c/td\u003e\u003ctd\u003eAccounting, audit, and bookkeeping firms\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eProfessional services\u003c/td\u003e\u003ctd\u003e7392\u003c/td\u003e\u003ctd\u003eManagement, Consulting, and Public Relations Services\u003c/td\u003e\u003ctd\u003eManagement and PR consultancies\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eProfessional services\u003c/td\u003e\u003ctd\u003e7311\u003c/td\u003e\u003ctd\u003eAdvertising Services\u003c/td\u003e\u003ctd\u003eAdvertising and digital marketing agencies\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eEducation \u0026amp; childcare\u003c/td\u003e\u003ctd\u003e8211\u003c/td\u003e\u003ctd\u003eElementary and Secondary Schools\u003c/td\u003e\u003ctd\u003ePrivate primary and secondary schools\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eEducation \u0026amp; childcare\u003c/td\u003e\u003ctd\u003e8299\u003c/td\u003e\u003ctd\u003eSchools and Educational Services (Not Elsewhere Classified)\u003c/td\u003e\u003ctd\u003eTuition centres, skills and training courses\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eEducation \u0026amp; childcare\u003c/td\u003e\u003ctd\u003e8351\u003c/td\u003e\u003ctd\u003eChild Care Services\u003c/td\u003e\u003ctd\u003eTaska, tadika, and childcare centres\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHealth\u003c/td\u003e\u003ctd\u003e5912\u003c/td\u003e\u003ctd\u003eDrug Stores and Pharmacies\u003c/td\u003e\u003ctd\u003ePharmacies (Guardian, Watsons, independents)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHealth\u003c/td\u003e\u003ctd\u003e8011\u003c/td\u003e\u003ctd\u003eDoctors and Physicians (Not Elsewhere Classified)\u003c/td\u003e\u003ctd\u003eClinics and general practitioners\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHealth\u003c/td\u003e\u003ctd\u003e8021\u003c/td\u003e\u003ctd\u003eDentists and Orthodontists\u003c/td\u003e\u003ctd\u003eDental clinics\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHealth\u003c/td\u003e\u003ctd\u003e8042\u003c/td\u003e\u003ctd\u003eOptometrists and Ophthalmologists\u003c/td\u003e\u003ctd\u003eOptical shops and optometrists\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eHealth\u003c/td\u003e\u003ctd\u003e8062\u003c/td\u003e\u003ctd\u003eHospitals\u003c/td\u003e\u003ctd\u003ePrivate hospitals\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e4722\u003c/td\u003e\u003ctd\u003eTravel Agencies and Tour Operators\u003c/td\u003e\u003ctd\u003eTravel agencies and tour operators\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e7011\u003c/td\u003e\u003ctd\u003eLodging: Hotels, Motels, Resorts (Not Elsewhere Classified)\u003c/td\u003e\u003ctd\u003eHotels, resorts, homestays\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e4121\u003c/td\u003e\u003ctd\u003eTaxicabs and Limousines\u003c/td\u003e\u003ctd\u003eTaxis and e-hailing (Visa includes ride-share here)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e4131\u003c/td\u003e\u003ctd\u003eBus Lines\u003c/td\u003e\u003ctd\u003eExpress and intercity bus operators\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e7523\u003c/td\u003e\u003ctd\u003eParking Lots, Parking Meters and Garages\u003c/td\u003e\u003ctd\u003ePaid parking operators\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eTravel \u0026amp; transport\u003c/td\u003e\u003ctd\u003e5541\u003c/td\u003e\u003ctd\u003eService Stations (With or without Ancillary Services)\u003c/td\u003e\u003ctd\u003ePetrol stations (Petronas, Shell, Petron)\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eDigital \u
10026amp; eCommerce\u003c/td\u003e\u003ctd\u003e4816\u003c/td\u003e\u003ctd\u003eComputer Network/Information Services\u003c/td\u003e\u003ctd\u003eInternet and network service providers, SaaS platforms\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eDigital \u0026amp; eCommerce\u003c/td\u003e\u003ctd\u003e5817\u003c/td\u003e\u003ctd\u003eDigital Goods: Applications (Excludes Games)\u003c/td\u003e\u003ctd\u003eSellers of apps and digital software\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eDigital \u0026amp; eCommerce\u003c/td\u003e\u003ctd\u003e5964\u003c/td\u003e\u003ctd\u003eDirect Marketing: Catalog Merchant\u003c/td\u003e\u003ctd\u003eCatalogue and mail-order sellers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eDigital \u0026amp; eCommerce\u003c/td\u003e\u003ctd\u003e5968\u003c/td\u003e\u003ctd\u003eDirect Marketing: Continuity/Subscription Merchant\u003c/td\u003e\u003ctd\u003eSubscription services with recurring billing\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eCharity \u0026amp; religious\u003c/td\u003e\u003ctd\u003e8398\u003c/td\u003e\u003ctd\u003eCharitable Social Service Organizations\u003c/td\u003e\u003ctd\u003eCharities, NGOs, and welfare fundraising bodies\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eCharity \u0026amp; religious\u003c/td\u003e\u003ctd\u003e8661\u003c/td\u003e\u003ctd\u003eReligious Organizations\u003c/td\u003e\u003ctd\u003eMosques, suraus, churches, temples\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFinancial \u0026amp; insurance\u003c/td\u003e\u003ctd\u003e6300\u003c/td\u003e\u003ctd\u003eInsurance Sales, Underwriting, and Premiums\u003c/td\u003e\u003ctd\u003eInsurance and takaful providers\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003eFinancial \u0026amp; insurance\u003c/td\u003e\u003ctd\u003e6012\u003c/td\u003e\u003ctd\u003eFinancial Institutions: Merchandise, Services, and Debt Repayment\u003c/td\u003e\u003ctd\u003eNon-bank financial institutions, cooperatives, financing\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\nFor the complete listing, consult the [Visa Merchant Data Standards Manual](https://usa.visa.com/content/dam/VCOM/download/merchants/visa-merchant-data-standards-manual.pdf) or Mastercard's Quick Reference Booklet.\n\n### Which MCC applies to charities and zakat organizations?\n\nCard networks do not define a dedicated zakat code, so classification follows the organization's main activity. Fundraising bodies and welfare NGOs are typically classified under 8398 (Charitable Social Service Organizations). Institutions whose core function is worship or religious administration, such as mosques and suraus, fall under 8661 (Religious Organizations). A zakat collection body could sit under either depending on how its predominant activity is registered, so confirm the classification with your acquiring bank.\n\n## Challenges \u0026 considerations with MCCs\n\nWhile MCCs are helpful, theyâre not always perfect:\n\n* **Misclassification:** Being assigned the wrong MCC can lead to higher fees or ineligibility for customer rewards. For example, a specialty caterer misclassified as a general retailer may miss out on dining perks.\n* **Changing MCC:** Though you can request a change, itâs difficult. You must show that your business activity has significantly changed for the acquirer to approve it.\n* **Multiple services:** Businesses with varied offerings (e.g., hotels with restaurants or spas) may be assigned just one MCC, which may not reflect all services, confusing rewards or reporting.\n\n## Where Billplz fits in\n\nMCCs are a card-network mechanism, so they apply to the card payments your business accepts. With Billplz, card transactions are processed through partner acquirers, and the acquirer assigns and holds your MCC when your account is set up. To confirm the code on file, ask the acquirer directly (step 1 above).\n\nWhat Billplz gives you is a single view of all your payments: FPX, Wallet, Card, and Instalments in one dashboard, with transaction records you can use for reconciliation, accounting, and reporting.\n\nIf you are setting up payments for your business, see how [Billplz Collection](https://main.billplz.com/collection) handles payment tracking and reconciliation.\n\n---\n\n## FAQ\n\n### How to find my Merchant Category Code (MCC)?\n\nThe most reliable way is to contact your payment processor or acquiring bank. They can confirm the code they have on file for your merchant account. You can also sometimes find it in your online payment gateway dashboard or detailed transaction reports.\n\n### Can I change my MCC?\n\nIt is possible, but requires a formal request to your acquiring bank or payment processor. The change is typically granted only if your primary business activity has substantially changed and you now qualify for a different, official code.\n\n### Why does my MCC affect my card fees?\n\nMCCs help determine your interchange rate. Lower-risk businesses usually get lower rates, while high-risk MCCs come with higher fees.\n\n### Do MCCs impact customer cashback and rewards?\n\nYes. Card issuers use the MCC to automatically identify the transaction type and determine if it qualifies for bonus rewards (for example, bonus points on travel or cashback on groceries). An incorrect MCC can cause your customers to miss out on rewards.\n\n### Who controls MCC codes?\n\nMCCs are based on ISO standards and are implemented by card networks and acquiring banks.\n\n### Can I use someone else's MCC?\n\nNo. MCCs are tied to your business type and merchant account. Misusing MCCs is against card network rules and may result in penalties.\n\n---\n\n## Conclusion\n\nThe Merchant Category Code (MCC) is far more than a four-digit number, it is a critical piece of infrastru
1cture that influences your processing costs, compliance requirements, and your customers' card benefits.\n\nUnderstanding your MCC is vital for both financial health and reporting accuracy. As a merchant, you should check and confirm your assigned MCC with your provider to ensure it accurately reflects your business.","__component":"shared.rich-text"}]},{"id":469,"documentId":"f72fvkgcl0jdxvi59l1djz5u","title":"What is PayNet? Malaysia's payment network explained","slug":"paynet-malaysia-payment-network-guide","createdAt":"2025-10-15T03:25:08.875Z","updatedAt":"2026-07-03T11:43:06.846Z","publishedAt":"2026-07-03T11:43:06.982Z","publishDate":"2025-10-15T03:25:08.875Z","cover":{"id":40,"documentId":"uz3g1349m79ancos7mnc2d0d","name":"251015_03_01_img.webp","alternativeText":"PayNet Malaysia","caption":"PayNet Malaysia","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_03_01_img_db3b78a810.webp","hash":"small_251015_03_01_img_db3b78a810","mime":"image/webp","name":"small_251015_03_01_img.webp","path":null,"size":6.55,"width":500,"height":278,"sizeInBytes":6550},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_03_01_img_db3b78a810.webp","hash":"medium_251015_03_01_img_db3b78a810","mime":"image/webp","name":"medium_251015_03_01_img.webp","path":null,"size":10.2,"width":750,"height":417,"sizeInBytes":10196},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_03_01_img_db3b78a810.webp","hash":"thumbnail_251015_03_01_img_db3b78a810","mime":"image/webp","name":"thumbnail_251015_03_01_img.webp","path":null,"size":2.78,"width":245,"height":136,"sizeInBytes":2784}},"hash":"251015_03_01_img_db3b78a810","ext":".webp","mime":"image/webp","size":14.52,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_03_01_img_db3b78a810.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-22T04:21:49.305Z","updatedAt":"2025-10-22T04:22:13.877Z","publishedAt":"2025-10-22T04:21:49.306Z","focalPoint":null},"category":{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights"},"seo_meta_tag":{"id":196,"metaTitle":"What is PayNet? Malaysia's payment network explained","metaDescription":"PayNet runs Malaysia's payment rails: FPX, DuitNow, JomPAY, MyDebit, and IBG. See who owns it, what it operates, and how businesses connect through gateways.","metaKeywords":"PayNet Malaysia, Payments Network Malaysia, DuitNow, FPX, IBG Malaysia, JomPAY, MyDebit, payment infrastru
1cture Malaysia, interbank transfer Malaysia, cashless payment Malaysia, Bank Negara payment network","metaSchema":[{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_03_01_img_db3b78a810.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"What is PayNet? Malaysia's payment network explained","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"PayNet runs Malaysia's payment rails: FPX, DuitNow, JomPAY, MyDebit, and IBG. See who owns it, what it operates, and how businesses connect through gateways.","dateModified":"2026-07-03T11:34:16.883Z","datePublished":"2025-10-15T03:25:08.875Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/insights/paynet-malaysia-payment-network-guide","@type":"WebPage"}},{"@type":"FAQPage","@context":"https://schema.org","mainEntity":[{"name":"What does PayNet stand for?","@type":"Question","acceptedAnswer":{"text":"PayNet is short for Payments Network Malaysia Sdn Bhd, the company that operates Malaysia's national payment infrastru
1cture, including FPX, DuitNow, JomPAY, MyDebit, and Interbank GIRO.","@type":"Answer"}},{"name":"Is PayNet a payment gateway?","@type":"Question","acceptedAnswer":{"text":"No. PayNet is the infrastructure layer that connects banks and Wallet providers. Businesses access PayNet-operated services through a payment gateway, which handles onboarding, collection, and reporting.","@type":"Answer"}},{"name":"How can a business accept FPX or DuitNow payments?","@type":"Question","acceptedAnswer":{"text":"Sign up with a payment gateway that offers them. With Billplz, businesses collect FPX payments and generate DuitNow QR codes from one dashboard; current rates are on the pricing page.","@type":"Answer"}}]}]},"blocks":[{"id":444,"body":"**Key takeaways:**\n\n* PayNet (Payments Network Malaysia Sdn Bhd) is Malaysiaâs central payments infrastructure provider, responsible for powering nationwide systems like FPX, DuitNow, IBG, and more.\n* Core services include real-time bank transfers (DuitNow), online payments (FPX), scheduled interbank GIRO (IBG), bill payments (JomPAY), debit card transactions (MyDebit), and cheque clearing (eSPICK).\n* Benefits for businesses include secure and regulated transactions, nationwide acceptance, low fees, interoperability (via DuitNow QR), and support for Malaysiaâs cashless agenda.\n* PayNet is not a customer-facing gateway, but rather the infrastructure. Bu
1sinesses need payment gateways like Billplz to connect to PayNet's services.\n* Gateways simplify access to PayNet-powered services, offering features like flat fees, real-time dashboards, eCommerce integration, and split payments.\n* As Malaysia moves toward a digital economy, businesses access PayNet-powered services through payment gateways such as Billplz.\n\n## Introduction\n\nPayments Network Malaysia Sdn Bhd (PayNet) is the national payments network and central infrastructure for Malaysia's financial markets. From online transactions to bill payments, instant transfers, and debit card usage, PayNet is the backbone behind trusted services like FPX, DuitNow, IBG, and more.\n\nFor businesses and consumers alike, understanding PayNet is essential. While you may never directly interact with PayNet, you benefit from it every time you pay with DuitNow QR, settle bills through JomPAY, or check out online using FPX.\n\n## What is PayNet Malaysia, and how does it work?\n\n[PayNet (Payments Network Malaysia Sdn Bhd)](https://paynet.my/index.html) is the company that builds and operates Malaysia's national payment infrastru
1cture. It runs the rails behind FPX online banking payments, DuitNow transfers and QR, JomPAY bill payments, MyDebit card transactions, and Interbank GIRO, and is owned by Bank Negara Malaysia, its largest shareholder, together with eleven Malaysian financial institutions.\n\nIt was formed from the merger of the Malaysian Electronic Payment System (MEPS) and Malaysian Electronic Clearing Corporation Sdn Bhd (MyClear) in 2017 (Source: [Merger of MyClear and MEPS](https://www.bnm.gov.my/-/merger-of-myclear-and-meps-strengthening-malaysia-s-payments-infrastructure-to-accelerate-migration-to-e-payments)).\n\nWith a mission to modernise and standardise the nationâs payment infrastructure, the organisation ensures that both businesses and consumers benefit from secure, accessible, and seamless financial services. PayNet operates a wide range of services, including retail payments, real-time transfers, and cheque processing.\n\n## Is PayNet owned by Bank Negara?\n\nYes. PayNet is jointly owned by [Bank Negara Malaysia (BNM)](https://www.bnm.gov.my/), its largest shareholder, and eleven Malaysian financial institutions, including Maybank, CIMB, RHB, Public Bank, and Bank Islam [PayNet corporate profile](https://www.paynet.my/about-us/corporate-profile.html).\n\n## What does PayNet Malaysia do: Key services\n\nPayNet reported [8.44 billion digital payment transactions in 2025](https://www.paynet.my/about-us/media-centre/press-release/8-44-billion-transactions-processed-in-2025-as-digital-payments-become-malaysians-preferred-way-to-pay.html), an average of 260 transactions per second (PayNet, April 2026).\n\nPayNet operates the key payment rails that form the backbone of Malaysia's digital payment landscape:\n\n* [**FPX (Financial Process Exchange)**](https://paynet.my/personal-fpx.html)**:** A direct-to-bank online payment gateway that allows customers to make real-time payments using their online banking accounts. It is commonly used in eCommerce, bill payments, and government portals.\n* [**DuitNow**](https://www.duitnow.my/)**:** An instant bank and e-wallet transfer service that allows individuals and businesses to send and receive funds using a DuitNow ID, mobile number, or NRIC. This includes DuitNow QR, a single, interoperable QR code that works across multiple banks and e-wallets.\n* [**IBG (Interbank GIRO)**](https://paynet.my/personal-ibg.html)**:** A scheduled interbank fund transfer system used for bulk and individual credit transfers. Supports fund transfers across 42 banks.\n* [**JomPAY**](https://www.jompay.com.my/)**:** A nationwide bill payment platform where customers can pay any registered biller via internet or mobile banking.\n* [**MyDebit**](https://paynet.my/personal-mydebit.html)**:** Malaysiaâs domestic debit card system, allowing ATM cardholders to make point-of-sale transactions nationwide.\n* **Cheque Processing:** The [eSPICK system](https://paynet.my/fi-eSPICK.html) (Sistem Penjelasan Imej Cek Kebangsaan) is Malaysia's national cheque clearing house.\n\n## Benefits of PayNet services for Malaysian businesses\n\nPayNetâs ecosystem provides significant benefits that drive business growth and enhance operational efficiency, with key advantages including:\n\n* **Gain nationwide acceptance:** Services like FPX and DuitNow are linked with all major banks and e-wallets, providing a wide reach.\n* **Ensure security and regulation:** As the national payments network, PayNet is backed and regulated by Bank Negara Malaysia, offering a high level of security and customer trust.\n* **Benefit from low transaction fees:** Services like FPX and DuitNow often have low, flat-rate transaction fees, especially when compared to other payment options.\n* **Customer trust**: PayNet services are widely recognised and used daily by the Malaysian public, instilling confidence in payment methods.\n* **Enhance interoperability:** DuitNow QR provides a single, unified QR code, eliminating the need for businesses to display multiple QR codes from different providers.\n* **Support cashless adoption:** By using PayNet-powered services, businesses can facilitate the shift from cash, which aligns with Bank Negara Malaysiaâs cashless agenda.\n* **Provi
1des secure, reliable, and regulated payment rails**: Businesses rely on the established infrastructure for stable and trustworthy transactions.\n* **Facilitate financial inclusion:** The broad access across banks and e-wallets makes digital payments accessible to a wider segment of the population.\n\n## How is PayNet different from payment gateways?\n\nPayNet serves as the underlying payment infrastructure: the \"highway\" that connects financial institutions. It is not a customer-facing product.\n\nPayment gateways, like Billplz, on the other hand, are the interface providers that connect businesses to the PayNet network. They are the \"cars and toll booths\" that enable businesses to use services like FPX and DuitNow.\n\nA business needs a payment gateway to seamlessly integrate PayNet's services into its website or point-of-sale system.\n\n## How do businesses use PayNet services?\n\nBusinesses typically use PayNet's services indirectly through their payment gateway partners:\n\n* **Online transactions:** Businesses use a gateway to integrate FPX, allowing customers to pay directly from their bank accounts.\n* **In-store \u0026 online:** Businesses accept DuitNow QR payments in retail or e-commerce settings.\n* **Bill collection:** Businesses leverage JomPAY for easy and widespread bill collection.\n* **Debit card acceptance:** MyDebit facilitates secure and regulated debit card payments.\n\nThese services are often implemented via integration partners and payment gateways, which manage the technical setup and provide user-friendly dashboards.\n\n## Challenges and considerations with PayNet\n\nDespite its strong infrastructure, PayNet's services can be affected by the reliability of individual banks. If a participating bank experiences downtime, services like FPX or DuitNow may be temporarily disrupted.\n\nAdditionally, not all PayNet services operate in real time. IBG and cheque processing, for example, are still subject to processing delays.\n\nFor small and medium businesses, the variety of available services may present a steep learning curve, especially without technical support. This is where integration partners or payment gateways play a crucial role. \n\nThey offer simplified access, clear documentation, and ready-to-use tools to help businesses adopt and manage PayNet-powered payment solutions efficiently.\n\n## Billplzâs role in PayNet-powered solutions\n\nBillplz has processed payments on Malaysia's national rails since 2012, with FPX as its core service. Billplz is a certified PayNet system integrator. Businesses connect through the dashboard or the documented REST API, and [Billplz Payment Order](https://main.billplz.com/payment-order) runs disbursements on DuitNow Transfer infrastructure with fast or real-time payouts.\n\nBy acting as an integration partner, Billplz adds valuable features on top of PayNet's core infrastructure, including:\n\n* Transparent flat fees per FPX transaction (current rates on the [pricing page](https://main.billplz.com/pricing)).\n* Real-time dashboards for monitoring transactions and revenue.\n* API and plugins for easy integration with e-commerce platforms.\n* Features like automated split payments and team management.\n* Enterprise-grade protection for every transaction.\n\n_To learn more about FPX payments, read:_ [_FPX payment for business: How it works, guides \u0026 our solutions_](https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide)\n\n## FAQ\n\n### What does PayNet stand for?\n\nPayNet is short for Payments Network Malaysia Sdn Bhd, the company that operates Malaysia's national payment infrastru
1cture, including FPX, DuitNow, JomPAY, MyDebit, and Interbank GIRO.\n\n### Is PayNet a payment gateway?\n\nNo. PayNet is the infrastructure layer that connects banks and Wallet providers. Businesses access PayNet-operated services through a payment gateway, which handles onboarding, collection, and reporting.\n\n### How can a business accept FPX or DuitNow payments?\n\nSign up with a payment gateway that offers them. With Billplz, businesses collect FPX payments and generate DuitNow QR codes from one dashboard; current rates are on the [pricing page](https://main.billplz.com/pricing).\n\n## Conclusion\n\nAs Malaysia pushes toward a digital-first economy, PayNet continues to play a central role in shaping the future of payments. Its reliable, scalable, and secure infrastructure enables real-time, low-cost payment options for both businesses and consumers.\n\nFor businesses looking to embrace digital transformation, adopting PayNet-powered solutions is essential for serving modern consumers.\n\nBy partnering with trusted gateways like Billplz, businesses can easily access these services and benefit from a modern, efficient, and secure payment experience.","__component":"shared.rich-text"}]},{"id":492,"documentId":"ruq9jxjgks5grbp2nohroulp","title":"FPX payment in Malaysia: how it works and how to accept it","slug":"fpx-payment-malaysia-business-guide","createdAt":"2025-10-15T02:24:04.560Z","updatedAt":"2026-07-15T03:25:20.339Z","publishedAt":"2026-07-15T03:25:20.432Z","publishDate":"2025-10-15T02:24:04.560Z","cover":{"id":45,"documentId":"h31mfe3h9ju84f29j02ulzne","name":"251015_02_01_img.webp","alternativeText":"FPX payment for business","caption":"FPX payment for business","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251015_02_01_img_1dc44d8f2a.webp","hash":"small_251015_02_01_img_1dc44d8f2a","mime":"image/webp","name":"small_251015_02_01_img.webp","path":null,"size":8.81,"width":500,"height":278,"sizeInBytes":8814},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251015_02_01_img_1dc44d8f2a.webp","hash":"medium_251015_02_01_img_1dc44d8f2a","mime":"image/webp","name":"medium_251015_02_01_img.webp","path":null,"size":13.46,"width":750,"height":417,"sizeInBytes":13456},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251015_02_01_img_1dc44d8f2a.webp","hash":"thumbnail_251015_02_01_img_1dc44d8f2a","mime":"image/webp","name":"thumbnail_251015_02_01_img.webp","path":null,"size":3.93,"width":245,"height":136,"sizeInBytes":3928}},"hash":"251015_02_01_img_1dc44d8f2a","ext":".webp","mime":"image/webp","size":20.93,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_02_01_img_1dc44d8f2a.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-22T08:08:09.537Z","updatedAt":"2025-10-22T08:08:34.782Z","publishedAt":"2025-10-22T08:08:09.538Z","focalPoint":null},"category":{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products"},"seo_meta_tag":{"id":219,"metaTitle":"FPX payment in Malaysia: how it works and how to accept it","metaDescription":"FPX lets customers pay straight from their bank accounts. Learn how FPX works, its limits and settlement times, and how to start accepting it with Billplz.","metaKeywords":"FPX payment Malaysia, what is FPX, apa itu FPX, Financial Process Exchange, FPX payment gateway Malaysia, online banking payment, FPX limits, accept FPX payments, Billplz FPX","metaSchema":{"@type":"BlogPosting","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251015_02_01_img_1dc44d8f2a.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"FPX payment in Malaysia: how it works and how to accept it","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"}
1,"name":"Billplz","@type":"Organization"},"description":"FPX lets customers pay straight from their bank accounts. Learn how FPX works, its limits and settlement times, and how to start accepting it with Billplz.","dateModified":"2026-07-15T03:25:19.114Z","datePublished":"2025-10-15T02:24:04.560Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/products/fpx-payment-malaysia-business-guide","@type":"WebPage"}}},"blocks":[{"id":467,"body":"**Key takeaways:**\n\n* FPX (Financial Process Exchange) is Malaysia's real-time online banking payment method, operated by PayNet.\n* Customers pay straight from their bank accounts: personal accounts up to MYR 30,000 per transaction, corporate accounts up to MYR 1,000,000.\n* More than 20 Malaysian banks participate, and payments authenticate through each bank's own login and 2FA.\n* Businesses accept FPX through an acquiring bank, a third party acquirer, or a payment gateway like Billplz, with flat per-transaction fees. Current rates are on the [pricing page](https://main.billplz.com/pricing).\n* FPX has three models: B2C for everyday payments, and B2B1 and B2B2 for corporate flows with dual authorization and batch processing.\n\n## Introduction\n\nMost online purchases in Malaysia are paid through bank transfer, not cards. FPX is the rail that makes that possible: it connects a merchant's checkout to the customer's own internet banking, so payment happens in seconds without a card. This guide explains how FPX works, what it costs, its limits, and how your business can start accepting it.\n\n## What is FPX?\n\nFPX (Financial Process Exchange) is Malaysia's online banking payment system, operated by [PayNet](https://www.paynet.my/business-solutions/fpx.html). It lets customers pay a business directly from their bank account using their own internet banking login. Payments are authorized in real time with the bank's two-factor authentication, and more than 20 Malaysian banks participate.\n\nBecause the customer authenticates with their own bank, no card details or banking credentials are ever shared with the merchant. Funds move directly from the customer's account, which is why FPX is the default payment method across Malaysian eCommerce, government portals, education, and donations.\n\n## How does an FPX payment work?\n\nFrom your customer's side, an FPX payment takes five steps:\n\n1. **Choose FPX at checkout** and select their bank.\n2. **Log in** to their internet banking as usual.\n3. **Review the payment details** shown by their bank.\n4. **Approve the payment**, confirming with the bank's two-factor authentication (for example an app approval or TAC).\n5. **Done.** The bank debits the account in real time and the customer is redirected back to your site with a confirmation.\n\nFor the business, the payment status arrives in real time, which makes reconciliation straightforward: you know immediately which orders are paid.\n\n## The three FPX models: B2C, B2B1, and B2B2\n\nMost guides stop at consumer payments, but FPX officially has three models (per [PayNet's developer documentation](https://docs.developer.paynet.my/docs/fpx/b2c-overview)):\n\n* **B2C** is the everyday model: one person logs in, approves, and pays in a single session. This is what your customers use at checkout.\n* **B2B1** adds dual control for company accounts: one representative (the maker) initiates the payment, and a second (the authorizer) approves it later from the company's corporate banking. Built for organizations where no single person should move money alone.\n* **B2B2** is for volume: businesses submit batches of payments host-to-host for authorization, rather than one browser session per transaction. Suited to large organizations with high payment counts.\n\nIf you are collecting from consumers, B2C is all you need. If you invoice companies with corporate accounts, ask your provider about B2B support: Billplz offers FPX Credit Card Account (CCA) features for B2B collections on Enterprise plans.\n\n## FPX limits, banks, and fees\n\n\u003ctable\u003e\u003ctbody\u003e\u003ctr\u003e\u003ctd\u003e\u0026nbsp;\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003ePersonal (B2C)\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003e\u003cstrong\u003eCorporate (B2B)\u003c/strong\u003e\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003ePer-transaction limit\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eMYR 1.00 to MYR 30,000\u003c/td\u003e\u003ctd\u003eMYR 2.00 to MYR 1,000,000\u003c/td\u003e\u003c/tr\u003e\u003ctr\u003e\u003ctd\u003e\u003cstrong\u003eAuthentication\u003c/strong\u003e\u003c/td\u003e\u003ctd\u003eOwn internet banking login + 2FA\u003c/td\u003e\u003ctd\u003eCorporate banking, with dual authorization available\u003c/td\u003e\u003c/tr\u003e\u003c/tbody\u003e\u003c/table\u003e\n\nLimits are set by PayNet and are subject to each bank's own transfer limits, whichever is lower ([PayNet FPX](https://paynet.my/personal-solutions/fpx.html), as of July 2026). PayNet lists more than 20 participating banks for c
1onsumers, including Maybank, CIMB, Public Bank, RHB, and Hong Leong.\n\n**Fees:** FPX is typically charged as a flat fee per transaction by your bank or gateway, not a percentage of the sale. That is what makes it economical for larger payments. Billplz charges a flat fee per successful FPX transaction; current rates are on the [pricing page](https://main.billplz.com/pricing).\n\n## FPX vs cards, Wallet payments, and DuitNow\n\n* **FPX vs Card:** FPX settles faster to the merchant, carries a flat fee instead of a percentage, and has no card-style chargebacks, since the customer's bank authenticates every payment. Cards suit customers who want instalments or card rewards.\n* **FPX vs Wallet payments:** Wallet apps are convenient for small, on-the-go payments but carry wallet balance limits. FPX covers a broader range of customers through internet banking and supports much higher amounts.\n* **FPX vs DuitNow:** Both are operated by PayNet. FPX handles online checkout payments from bank accounts; DuitNow covers instant transfers by mobile number or NRIC, and DuitNow QR for scan-to-pay. \\[CONFIRM BEFORE PUBLISH â current text claims DuitNow Online Banking/Wallets \"is replacing FPX\"; as PayNet SI you know the actual migration status and timeline. State it accurately here or omit.\\]\n\nAlso read: [DuitNow QR for online businesses](https://main.billplz.com/blog/products/duitnow-qr-for-online-businesses)\n\n## How to start accepting FPX payments\n\nPayNet supports two onboarding routes: directly through an acquiring bank, or through a third party acquirer or payment gateway. For most SMEs the gateway route is fastest:\n\n1. **Choose a payment gateway** that offers FPX, such as Billplz.\n2. **Sign up and verify your business.** You will need your SSM registration details and a bank account for settlement.\n3. **Integrate your checkout.** Use the no-code dashboard (create and send bills), pre-built plugins for platforms like Shopify and WooCommerce, or the API for custom builds.\n4. **Test in sandbox** to confirm the payment flow end to end.\n5. **Go live** and start collecting. FPX payouts reach your account by the next business day, with real-time options for Enterprise users.\n\nAlso read: [Shopify payment gateway in Malaysia with local payment methods](https://main.billplz.com/blog/products/shopify-payment-gateway-malaysia-local-payment-methods)\n\n## Billplz solutions for FPX payments\n\nBillplz has processed payments on Malaysia's national rails since 2012, with FPX as its core service, and is a certified PayNet system integrator.\n\n* Flat fee per successful FPX transaction, with current rates on the [pricing page](https://main.billplz.com/pricing).\n* Next business day payouts, with real-time settlement for Enterprise users.\n* No-code bills, payment links via Catalog Payment Form, plugins, and a documented REST API.\n* Optional split payments for marketplaces, agents, and multi-account flows.\n* 2FA and PCI DSS compliance, with 99.9% historical uptime.\n\nAlso read: [Toyyibpay vs Billplz: which payment gateway should you choose?](https://main.billplz.com/blog/products/toyyibpay-billplz-payment-gateway-comparison)\n\n---\n\n## FAQ\n\n### Apa itu FPX?\n\nFPX (Financial Process Exchange) ialah kaedah pembayaran dalam talian Malaysia yang dikendalikan oleh PayNet. Ia membolehkan pelanggan membayar terus dari akaun bank melalui perbankan internet, dengan pengesahan keselamatan daripada bank sendiri. Had transaksi bagi akaun peribadi ialah sehingga MYR 30,000.\n\n### Is FPX the same as online banking?\n\nNo. Online banking is your bank's own app or website. FPX is the payment rail that connects a merchant's checkout to your online banking, so you can pay a business directly from your account.\n\n### Is FPX the same as DuitNow?\n\nNo. Both are operated by PayNet, but FPX handles online checkout payments from bank accounts, while DuitNow covers instant transfers using a mobile number or NRIC, and DuitNow QR for scan-to-pay payments.\n\n### Why is FPX trusted in Malaysia?\n\nFPX is operated by PayNet, whose largest shareholder is Bank Negara Malaysia, and every transaction is authenticated by the customer's own bank with its standard security controls and 2FA.\n\n### What is the maximum limit for FPX?\n\nFor personal accounts, up to MYR 30,000 per transaction. For corporate accounts, up to MYR 1,000,000 per transaction. Your bank's own transfer limit applies if it is lower (PayNet, as of July 2026).\n\n### What is the minimum amount for FPX?\n\nMYR 1.00 for personal accounts and MYR 2.00 for c
1orporate accounts, per PayNet's published limits.\n\n### How fast is FPX settlement?\n\nThe payment itself is real-time. Merchant payouts are typically settled the next business day, depending on your payment gateway; Billplz offers real-time settlement for Enterprise users.\n\n### Is FPX safe for online business transactions?\n\nYes. Every payment is authenticated by the customer's own bank, including 2FA, and no banking credentials are shared with the merchant.\n\n### What banks are supported under FPX?\n\nMore than 20 Malaysian banks participate, including Maybank, CIMB, Public Bank, RHB Bank, and Hong Leong Bank. PayNet publishes the full list on its [FPX page](https://paynet.my/personal-solutions/fpx.html).\n\n### How much does FPX cost per transaction?\n\nTypically a flat fee set by your payment gateway or bank, rather than a percentage. Billplz charges a flat fee per successful FPX transaction; current rates are on the [pricing page](https://main.billplz.com/pricing).\n\n---\n\n## Conclusion\n\nFPX is the backbone of online payments in Malaysia: real-time, bank-authenticated, and economical at any transaction size. Whether you collect through bills, payment links, plugins, or the API, accepting FPX is usually the single biggest step a Malaysian business can take toward getting paid faster. And as payment habits keep evolving, from FPX to DuitNow QR to Wallet payments, there is always another rail worth understanding next.\n\nAlso read: [Payment link Malaysia: how to create and use one](https://main.billplz.com/blog/insights/payment-link-malaysia-for-business)","__component":"shared.rich-text"}]},{"id":433,"documentId":"rj2lznmr4b9h4g5l333n5clo","title":"Billplz wins IMT-GT Business Excellence Awards 2025","slug":"billplz-wins-imt-gt-business-excellence-awards-2025","createdAt":"2025-10-01T04:13:44.373Z","updatedAt":"2026-07-03T08:48:55.746Z","publishedAt":"2026-07-03T08:48:55.875Z","publishDate":"2025-10-01T04:13:44.373Z","cover":{"id":26,"documentId":"rfosfat8eofvzwqbnjf7woh3","name":"251001_img.webp","alternativeText":"Billplz IMT-GT Business Excellence Awards 2025","caption":"Billplz wins IMT-GT Business Excellence Awards 2025","width":901,"height":501,"formats":{"small":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/small_251001_img_6153659a68.webp","hash":"small_251001_img_6153659a68","mime":"image/webp","name":"small_251001_img.webp","path":null,"size":14.02,"width":500,"height":278,"sizeInBytes":14018},"medium":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/medium_251001_img_6153659a68.webp","hash":"medium_251001_img_6153659a68","mime":"image/webp","name":"medium_251001_img.webp","path":null,"size":23.27,"width":750,"height":417,"sizeInBytes":23272},"thumbnail":{"ext":".webp","url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/thumbnail_251001_img_6153659a68.webp","hash":"thumbnail_251001_img_6153659a68","mime":"image/webp","name":"thumbnail_251001_img.webp","path":null,"size":4.97,"width":245,"height":136,"sizeInBytes":4966}},"hash":"251001_img_6153659a68","ext":".webp","mime":"image/webp","size":33.72,"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251001_img_6153659a68.webp","previewUrl":null,"provider":"strapi-provider-upload-strapi-cloud","provider_metadata":null,"createdAt":"2025-10-01T04:56:39.075Z","updatedAt":"2025-10-22T05:20:01.428Z","publishedAt":"2025-10-01T04:56:39.075Z","focalPoint":null},"category":{"id":9,"documentId":"emor6qktvt2h4bpoaotj6wjs","createdAt":"2025-09-19T14:50:12.726Z","updatedAt":"2026-07-06T01:43:56.037Z","publishedAt":"2026-07-06T01:43:55.916Z","slug":"news"},"seo_meta_tag":{"id":160,"metaTitle":"Billplz wins IMT-GT Business Excellence Awards 2025","metaDescription":"Billplz wins IMT-GT Digital Innovation Award 2025. How 13 years of Malaysia-first focus and MYR 4B+ payment processing earned regional recognition.","metaKeywords":"Billplz, IMT-GT Business Excellence Awards 2025, Malaysian fintech, Digital Innovation Award, payment gateway Malaysia, FPX payment, DuitNow, Bank Negara Malaysia, payment processing Malaysia, fintech awards Malaysia, Malaysian payment infrastru
1cture, regional fintech recognition","metaSchema":{"@type":"NewsArticle","image":{"url":"https://inspiring-reward-2db3274af5.media.strapiapp.com/251001_img_6153659a68.webp","@type":"ImageObject","width":901,"height":501},"author":{"url":"https://main.billplz.com","name":"Billplz","@type":"Organization"},"@context":"https://schema.org","headline":"Billplz wins IMT-GT Business Excellence Awards 2025","publisher":{"logo":{"url":"https://main.billplz.com/logo.png","@type":"ImageObject"},"name":"Billplz","@type":"Organization"},"description":"Billplz wins IMT-GT Digital Innovation Award 2025. How 13 years of Malaysia-first focus and MYR 5B+ payment processing earned regional recognition.","dateModified":"2025-11-06T06:40:01.331Z","datePublished":"2025-10-01T04:13:44.373Z","mainEntityOfPage":{"@id":"https://main.billplz.com/blog/news/billplz-wins-imt-gt-business-excellence-awards-2025","@type":"WebPage"}}},"blocks":[{"id":408,"body":"**KUALA LUMPUR, 26 September 2025 â** Billplz won the Digital Innovation \u0026 Scalability Award at the IMT-GT Business Excellence Awards in Kuala Lumpur. The Indonesia-Malaysia-Thailand Growth Triangle Joint Business Council recognised the 30-person Malaysian fintech among companies across three countries.\n\nAfter 13 years focused exclusively on Malaysian payment infrastru
1cture, the award reflects how depth of market understanding can be as impactful as breadth of regional expansion. Billplz processes over MYR 5 billion annually for Malaysian businesses through infrastructure built specifically for local workflows, regulations, and payment preferences.\n\n## What the IMT-GT Business Excellence Awards recognise\n\nThe Indonesia-Malaysia-Thailand Growth Triangle represents 85 million people across 35 provinces and states. The 2025 awards recognised businesses demonstrating regional economic contribution through innovation, operational scalability, and measurable environmental impact. Deputy Prime Minister Datuk Seri Fadillah Yusof emphasised at the September 2025 gala:\n\n\u003e Under ASEAN Chairmanship 2025, Malaysia emphasizes an inclusive and sustainability agenda aligned with IMT-GT Vision 2036 goals focusing on interconnectivity, trade facilitation, digitalization, and sustainable development.\n\nThe award validates Billplzâs Malaysia-first approach to fintech development. While many payment platforms expand across multiple markets simultaneously, Billplz has spent over a decade building infrastructure for one: Malaysia.\n\n\n\n## How Malaysia-first focus won regional recognition\n\nBillplz operates with 30 people focused on one market. This concentration allows deep integration with Malaysian business infrastructure: understanding FPX adoption patterns, navigating Bank Negara Malaysia requirements, building features around Malaysian tax workflows, and optimising for local internet infrastructure.\n\nThe platform supports the payment methods Malaysian customers use: FPX, Wallet, Card, and Instalments, along with DuitNow QR. All systems maintain certification from PayNet.\n\n## Infrastructure used daily by Malaysian businesses\n\nMalaysian businesses now move over MYR 5 billion annually through Billplz's platform. The infrastructure processes transactions for businesses ranging from individual entrepreneurs to large enterprises. The team operates from Selangor, built around understanding Malaysian market dynamics.\n\nThe award recognizes thirteen years of work, but the Malaysia-first approach continues evolving. DuitNow QR adoption is accelerating among SMEs. E-wallet preferences shift with each generation. Payment infrastru
1cture built for Malaysian businesses still has room to deepen.\n\nThe IMT-GT award confirms this: fintech built for Malaysians can set regional benchmarks.","__component":"shared.rich-text"}]}],"categories":[{"id":9,"documentId":"emor6qktvt2h4bpoaotj6wjs","createdAt":"2025-09-19T14:50:12.726Z","updatedAt":"2026-07-06T01:43:56.037Z","publishedAt":"2026-07-06T01:43:55.916Z","slug":"news","articles":[{"id":433,"documentId":"rj2lznmr4b9h4g5l333n5clo","title":"Billplz wins IMT-GT Business Excellence Awards 2025","slug":"billplz-wins-imt-gt-business-excellence-awards-2025","createdAt":"2025-10-01T04:13:44.373Z","updatedAt":"2026-07-03T08:48:55.746Z","publishedAt":"2026-07-03T08:48:55.875Z","publishDate":"2025-10-01T04:13:44.373Z"}]},{"id":11,"documentId":"p296bzmrzclcapyrs5d7euvf","createdAt":"2025-10-15T07:50:47.109Z","updatedAt":"2026-07-06T01:44:23.334Z","publishedAt":"2026-07-06T01:44:23.247Z","slug":"products","articles":[{"id":503,"documentId":"w04etyfq69at6lupt94qkt4n","title":"BNPL Malaysia \u0026 Billplz: Our integrations, comparisons \u0026 offerings","slug":"bnpl-malaysia-comparison-integration-billplz","createdAt":"2025-10-15T03:56:39.198Z","updatedAt":"2026-07-17T05:02:02.271Z","publishedAt":"2026-07-17T05:02:02.395Z","publishDate":"2025-10-15T03:56:39.198Z"},{"id":492,"documentId":"ruq9jxjgks5grbp2nohroulp","title":"FPX payment in Malaysia: how it works and how to accept it","slug":"fpx-payment-malaysia-business-guide","createdAt":"2025-10-15T02:24:04.560Z","updatedAt":"2026-07-15T03:25:20.339Z","publishedAt":"2026-07-15T03:25:20.432Z","publishDate":"2025-10-15T02:24:04.560Z"},{"id":427,"documentId":"cx0acutlmrprt9tg1vfzt4ko","title":"Shopify payment gateway in Malaysia with local payment methods","slug":"shopify-payment-gateway-malaysia-local-payment-methods","createdAt":"2025-10-15T04:10:19.966Z","updatedAt":"2026-07-03T07:54:59.426Z","publishedAt":"2026-07-03T07:54:59.578Z","publishDate":"2025-10-15T04:10:19.966Z"},{"id":422,"documentId":"ypmk7ccs31lsn6rop4m5phjf","title":"Toyyibpay vs Billplz: Which payment gateway should you choose?","slug":"toyyibpay-billplz-payment-gateway-comparison","createdAt":"2025-10-15T05:12:48.768Z","updatedAt":"2026-04-27T07:55:51.158Z","publishedAt":"2026-04-27T07:55:51.347Z","publishDate":"2025-10-15T05:12:48.768Z"},{"id":417,"documentId":"k7no8rp81m1vpacdi7rqua23","title":"Wise vs PayPal: Which payment gateway should you choose?","slug":"wise-vs-paypal-malaysia-payment-comparison","createdAt":"2025-12-02T04:53:49.867Z","updatedAt":"2026-01-06T01:22:14.942Z","publishedAt":"2026-01-06T01:22:15.006Z","publishDate":"2025-12-02T04:53:49.867Z"},{"id":418,"documentId":"xhp0wa41z27tt9wjzds1sndi","title":"Stripe vs PayPal: Which payment gateway should you choose?","slug":"stripe-vs-paypal-which-should-you-choose","createdAt":"2025-12-02T04:55:39.670Z","updatedAt":"2026-01-06T01:23:08.353Z","publishedAt":"2026-01-06T01:23:08.928Z","publishDate":"2025-12-02T04:55:39.670Z"},{"id":423,"documentId":"u046uh9tsfrnx3b1in1o8clt","title":"Merchant Discount Rate: What is it \u0026 its impact on transactions","slug":"merchant-discount-rate-guide","createdAt":"2025-12-02T05:08:36.640Z","updatedAt":"2026-04-29T03:34:03.613Z","publishedAt":"2026-04-29T03:34:03.777Z","publishDate":"2025-12-02T05:08:36.640Z"},{"id":477,"documentId":"vdwbw9xw97gql4aq8ed4t9dw","title":"Jom DuitNow with Billplz: Solutions for Online Businesses","slug":"duitnow-qr-for-online-businesses","createdAt":"2025-12-02T04:33:05.609Z","updatedAt":"2026-07-03T13:32:54.508Z","publishedAt":"2026-07-03T13:32:54.668Z","publishDate":"2025-12-02T04:33:05.609Z"}]},{"id":12,"documentId":"k725imgzrby8z63a7cwei3od","createdAt":"2025-10-15T07:51:31.276Z","updatedAt":"2026-07-06T01:44:14.136Z","publishedAt":"2026-07-06T01:44:14.090Z","slug":"insights","articles":[{"id":484,"documentId":"y5pdslf5vk27lwodn41sgamj","title":"Lazada vs Shopee vs TikTok Shop Malaysia: fees and best fit","slug":"lazada-vs-shopee-vs-tiktok-shop-malaysia","createdAt":"2025-10-15T04:26:22.384Z","updatedAt":"2026-07-04T02:59:02.681Z","publishedAt":"2026-07-04T02:59:02.836Z","publishDate":"2025-10-15T04:26:22.384Z"},{"id":490,"documentId":"to0n67zjpiw17vgyyr258onm","title":"MCC code lookup: find your merchant category code","slug":"merchant-category-codes-mcc-what-are-they-lookup-guide","createdAt":"2025-10-15T03:34:55.969Z","updatedAt":"2026-07-08T13:15:39.052Z","publishedAt":"2026-07-08T13:15:39.161Z","publishDate":"2025-10-15T03:34:55.969Z"},{"id":469,"documentId":"f72fvkgcl0jdxvi59l1djz5u","title":"What is PayNet? Malaysia's payment network explained","slug":"paynet-malaysia-payment-network-guide","createdAt":"2025-10-15T03:25:08.875Z","updatedAt":"2026-07-03T11:43:06.846Z","publishedAt":"2026-07-03T11:43:06.982Z","publishDate":"2025-10-15T03:25:08.875Z"},{"id":401,"documentId":"eoybfgwkblcsyrsax8p3lqky","title":"Shopify vs WooCommerce (WordPress): An updated comprehensive comparison","slug":"shopify-vs-woocommerce-comparison","createdAt":"2025-10-15T04:53:47.058Z","updatedAt":"2026-01-02T01:07:12.302Z","publishedAt":"2026-01-02T01:07:12.358Z","publishDate":"2025-10-15T04:53:47.058Z"},{"id":429,"documentId":"zd1jup0qx3dt6s5i7luc3qny","title":"Senangpay vs Billplz: Which payment gateway should you choose?","slug":"senangpay-vs-billplz-payment-gateway-comparison","createdAt":"2025-11-06T03:29:53.176Z","updatedAt":"2026-07-03T08:06:37.627Z","publishedAt":"2026-07-03T08:06:37.808Z","publishDate":"2025-11-06T03:29:53.176Z"},{"id":495,"documentId":"fpllqdeoaookznh00nvwanxc","title":"POS system Malaysia: how to choose one and what it cost","slug":"pos-system-malaysia-guide","createdAt":"2025-11-06T02:39:10.507Z","updatedAt":"2026-07-16T05:11:39.653Z","publishedAt":"2026-07-16T05:11:39.773Z","publishDate":"2025-11-06T02:39:10.507Z"},{"id":420,"documentId":"k2m31io2hgt4zpfqc81gldws","title":"Billplz vs Stripe: Which payment gateway should you choose?","slug":"billplz-vs-stripe-malaysia-payment-gateway-comparison","createdAt":"2025-11-06T06:35:12.424Z","updatedAt":"2026-04-27T07:43:08.049Z","publishedAt":"2026-04-27T07:43:08.234Z","publishDate":"2025-11-06T06:35:12.424Z"},{"id":432,"documentId":"vbu653r4eurqjws78bp1q2jw","title":"Billplz vs iPay88: Which payment gateway should you choose?","slug":"billplz-vs-ipay88-payment-gateway-malaysia","createdAt":"2025-11-06T03:39:46.736Z","updatedAt":"2026-07-03T08:16:07.779Z","publishedAt":"2026-07-03T08:16:07.932Z","publishDate":"2025-11-06T03:39:46.736Z"},{"id":496,"documentId":"q9po1dfxpg9imeivylgk7grc","title":"Billplz vs Curlec: Which payment gateway should you choose?","slug":"billplz-vs-curlec-payment-gateway-comparison","createdAt":"2025-11-06T06:40:37.124Z","updatedAt":"2026-07-16T05:12:09.280Z","publishedAt":"2026-07-16T05:12:09.419Z","publishDate":"2025-11-06T06:40:37.124Z"},{"id":494,"documentId":"ynambmx4ch84471zf3nmnrhi","title":"Payment link Malaysia: how to create and use one","slug":"payment-link-malaysia-for-business","createdAt":"2025-12-02T03:30:34.909Z","updatedAt":"2026-07-16T05:11:23.242Z","publishedAt":"2026-07-16T05:11:23.388Z","publishDate":"2025-12-02T03:30:34.909Z"},{"id":552,"documentId":"gujf28ss918hwfvzgw372ijg","title":"Billplz vs HitPay: fees, settlement, and support compared","slug":"billplz-vs-hitpay-malaysia","createdAt":"2026-07-15T02:57:28.830Z","updatedAt":"2026-07-29T07:29:51.877Z","publishedAt":"2026-07-29T07:29:52.052Z","publishDate":"2026-07-29T02:57:00.000Z"},{"id":555,"documentId":"mg46wv90jli2x0e1rjgekhvn","title":"How Malaysian government agencies collect payments online with FPX and DuitNow","
1slug":"government-payment-collection-malaysia-fpx-duitnow","createdAt":"2026-07-16T03:20:00.551Z","updatedAt":"2026-08-11T06:46:35.962Z","publishedAt":"2026-08-11T06:46:36.081Z","publishDate":"2026-08-11T07:03:00.000Z"},{"id":528,"documentId":"hozcxv8dqzmipi4150kn7l27","title":"Is Billplz safe? The security and compliance stack","slug":"is-billplz-safe","createdAt":"2026-07-16T06:04:17.344Z","updatedAt":"2026-07-29T04:08:19.076Z","publishedAt":"2026-07-29T04:08:19.211Z","publishDate":"2026-07-17T06:04:00.000Z"},{"id":527,"documentId":"cos4401y67gclywsau8m028h","title":"MyInvois e-invoicing in Malaysia: what you need to know and how payments connect","slug":"myinvois-e-invoicing-malaysia","createdAt":"2026-07-17T04:38:27.331Z","updatedAt":"2026-07-29T04:07:30.530Z","publishedAt":"2026-07-29T04:07:30.677Z","publishDate":"2026-07-21T04:38:00.000Z"},{"id":571,"documentId":"ndbado2ticzh9m0hvn8wj0ty","title":"Zakat and religious collection in Malaysia: how institutions accept payments online","slug":"zakat-religious-collection-malaysia","createdAt":"2026-08-11T07:04:46.265Z","updatedAt":"2026-09-08T02:58:54.752Z","publishedAt":"2026-09-08T02:58:54.915Z","publishDate":"2026-08-14T09:00:00.000Z"},{"id":568,"documentId":"d58fugngdby4tuewahms6unr","title":"Education fee collection in Malaysia: FPX and DuitNow for schools, colleges, and universities","slug":"education-fee-collection-malaysia-fpx-duitnow","createdAt":"2026-08-25T06:22:13.087Z","updatedAt":"2026-09-01T06:29:33.338Z","publishedAt":"2026-09-01T06:29:33.450Z","publishDate":"2026-08-25T06:22:13.087Z"},{"id":569,"documentId":"kl4x2kdaebgx5ngxzfunnwxx","title":"Malaysia is phasing out proprietary QR codes: what merchants need to know","slug":"qr-interoperability-malaysia-duitnow","createdAt":"2026-09-01T05:56:52.853Z","updatedAt":"2026-09-01T06:39:52.364Z","publishedAt":"2026-09-01T06:39:52.464Z","publishDate":"2026-09-01T06:25:00.000Z"},{"id":574,"documentId":"xp72f9q9dvae059dmlylkqov","title":"538 digital payments per person: Malaysia's 2025 cashless data","slug":"digital-payments-malaysia-statistics-2025","createdAt":"2026-09-08T02:07:16.038Z","updatedAt":"2026-09-08T03:32:14.364Z","publishedAt":"2026-09-08T03:32:14.473Z","publishDate":"2026-09-08T02:07:16.038Z"},{"id":584,"documentId":"bg39su92m8jyofzdmj69ft9k","title":"Malaysia built its own payment system. Here is what that took.","slug":"malaysia-payment-infrastructure-independence","createdAt":"2026-09-14T04:14:20.255Z","updatedAt":"2026-09-14T07:40:49.300Z","publishedAt":"2026-09-14T07:40:49.419Z","publishDate":"2026-09-14T04:14:20.255Z"},{"id":587,"documentId":"pdsa2du1b1ih9d56xlbfhk2o","title":"How to accept credit card payments in Malaysia (2026)","slug":"accept-credit-card-payments-malaysia","createdAt":"2026-09-22T05:56:23.774Z","updatedAt":"2026-09-22T06:28:40.799Z","publishedAt":"2026-09-22T06:28:40.890Z","publishDate":"2026-09-22T05:56:23.774Z"},{"id":590,"documentId":"q9hpi7q4yh0ecztjmm31vvht","title":"FPX vs DuitNow: Malaysia's two payment rails explained","slug":"fpx-vs-duitnow-malaysia","createdAt":"2026-09-28T05:13:56.123Z","updatedAt":"2026-09-28T05:47:44.931Z","publishedAt":"2026-09-28T05:47:45.018Z","publishDate":"2026-09-28T05:13:56.123Z"}]}]},"__N_SSG":true},"page":"/blog","query":{},"buildId":"build-TfctsWXpff2fKS","isFallback":false,"isExperimentalCompile":false,"gsp":true,"scriptLoader":[]}</script>
1</body></html>
Line numbers count LF bytes from the start of the resource, as the search results do. Vendor segments are library code the classifier recognised; they are stored but not indexed. Bytes are shown as Latin1 characters, one per byte.